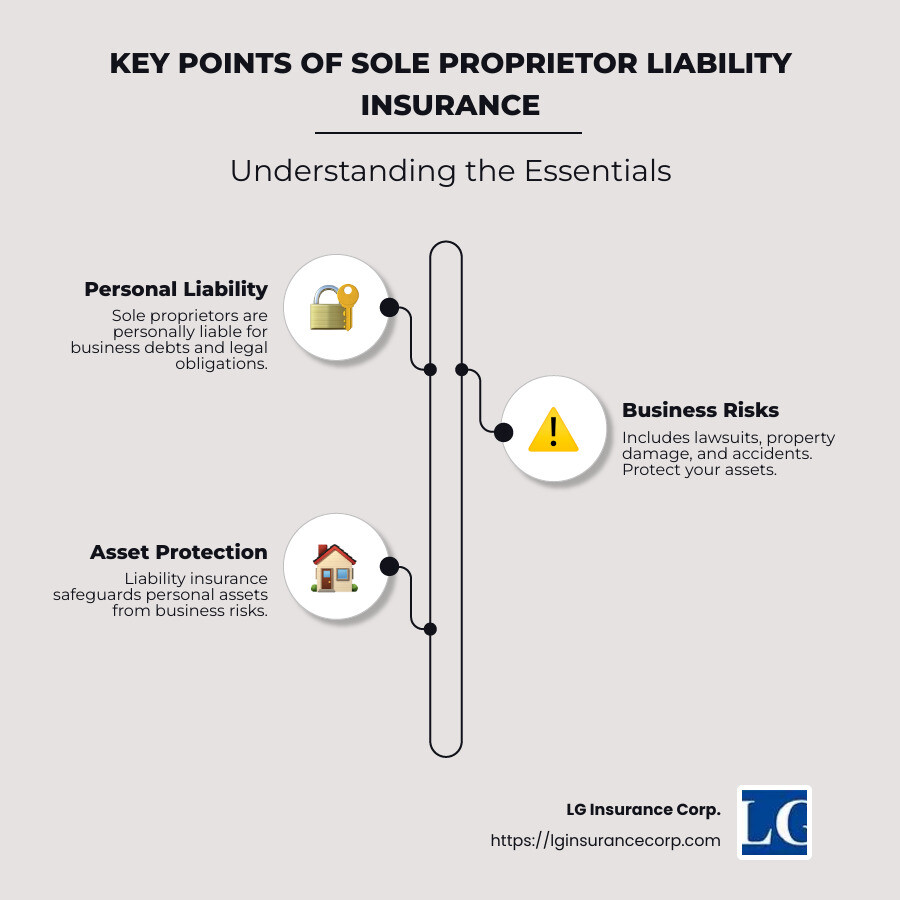
Sole proprietor liability insurance is crucial for those who run their own business, as it offers a safety net against the personal liabilities and business risks that come with sole proprietorship. As a sole proprietor, you’re responsible for all business debts and legal obligations, meaning your personal assets could be at stake if anything goes wrong. Having the right insurance can protect you from costly lawsuits and financial hardships.
Key Points:
- Personal liability is a significant concern for sole proprietors.
- Business risks can include lawsuits, property damage, and accidents.
- Without liability insurance, personal assets might be at risk.
My name is Leonard Garcia, and I am the owner of LG Insurance Agency with over 20 years of experience in the insurance industry. Through my work, I’ve helped many sole proprietors in Miami and across South Florida to secure the protection they need with comprehensive sole proprietor liability insurance options.
Handy sole proprietor liability insurance terms:
– personal liability insurance
– public liability insurance for individuals
– personal liability insurance quote
Understanding Sole Proprietorship
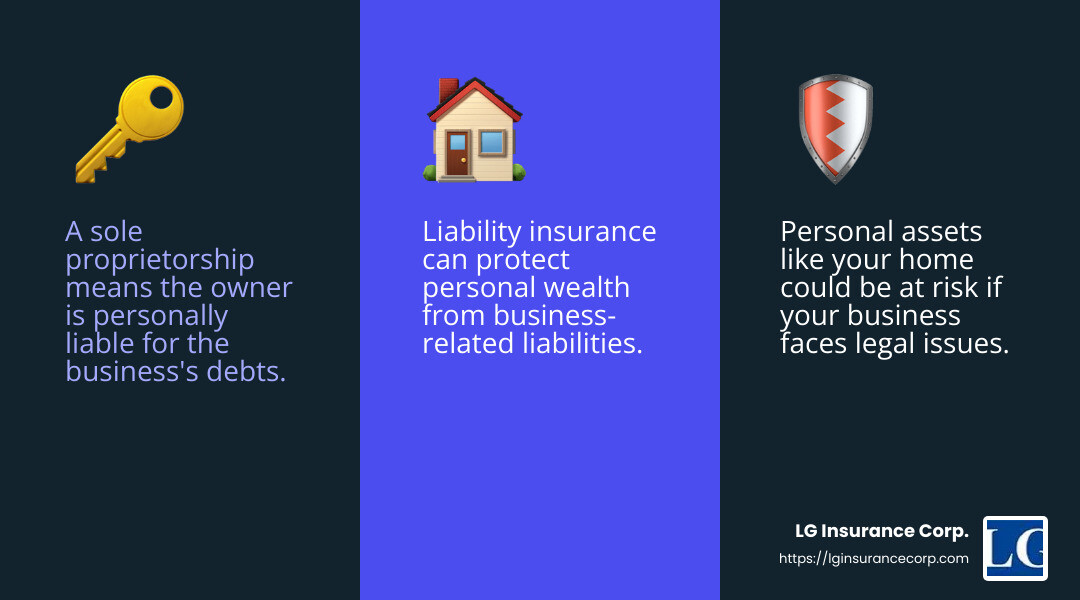
A sole proprietorship is the simplest form of business structure. It’s owned and operated by a single person, and there’s no legal distinction between the owner and the business. This means that the owner is personally responsible for all the business’s debts, taxes, and legal obligations.
Business Structure
In a sole proprietorship, you have complete control over your business. You make all the decisions, and you get all the profits. But this also means you bear all the risks. Unlike a corporation or an LLC, a sole proprietorship doesn’t offer any legal protection for your personal assets.
Owner Liability
One of the biggest drawbacks of a sole proprietorship is owner liability. If your business faces a lawsuit or owes money, you are personally liable. This means that your personal assets, like your home or savings, could be used to settle business debts.
For example, if a customer slips and falls in your store and sues you, you could be responsible for all the legal fees and any compensation required. Without the right insurance, these costs can be overwhelming.
Personal Assets
Protecting your personal assets should be a top priority for any sole proprietor. While the simplicity of a sole proprietorship is appealing, the lack of separation between personal and business assets poses a risk.
To mitigate these risks, many sole proprietors opt for sole proprietor liability insurance. This insurance can cover legal fees, settlements, and other costs that might otherwise come out of your pocket. It’s an essential step in safeguarding your personal wealth from business-related liabilities.
In summary, while sole proprietorships offer simplicity and control, they also come with significant personal liability risks. Understanding these risks and taking steps to protect yourself with the right insurance can make all the difference in ensuring the longevity and success of your business.
Importance of Sole Proprietor Liability Insurance
Running a business as a sole proprietor comes with many perks—simplicity, control, and direct access to profits. But it also comes with risks that can affect not just your business, but your personal finances too. That’s where sole proprietor liability insurance steps in, acting as a safety net for various potential pitfalls.
Lawsuits
Lawsuits can be costly and stressful. As a sole proprietor, you don’t have the luxury of separating your business assets from your personal ones. This means that if your business is sued, your personal savings and property could be at risk. For example, imagine a scenario where a customer claims they were injured on your business premises. The legal fees alone could be overwhelming, not to mention any potential settlements.
Sole proprietor liability insurance can cover these costs, helping you avoid financial ruin.
Property Damage
Accidents happen, and when they do, the cost of repairs can be substantial. Whether it’s a fire, flood, or vandalism, property damage can disrupt your business operations and lead to significant expenses. With the right insurance, you can get coverage for repairs and replacements, allowing you to get back to business as usual without a massive hit to your finances.
Auto Accidents
If your business involves driving—perhaps for deliveries or client meetings—commercial auto insurance is essential. Personal auto insurance may not cover accidents that occur during business activities. Imagine being involved in a fender bender while transporting goods. Without the right coverage, you could be responsible for repair costs and medical expenses.
Financial Protection
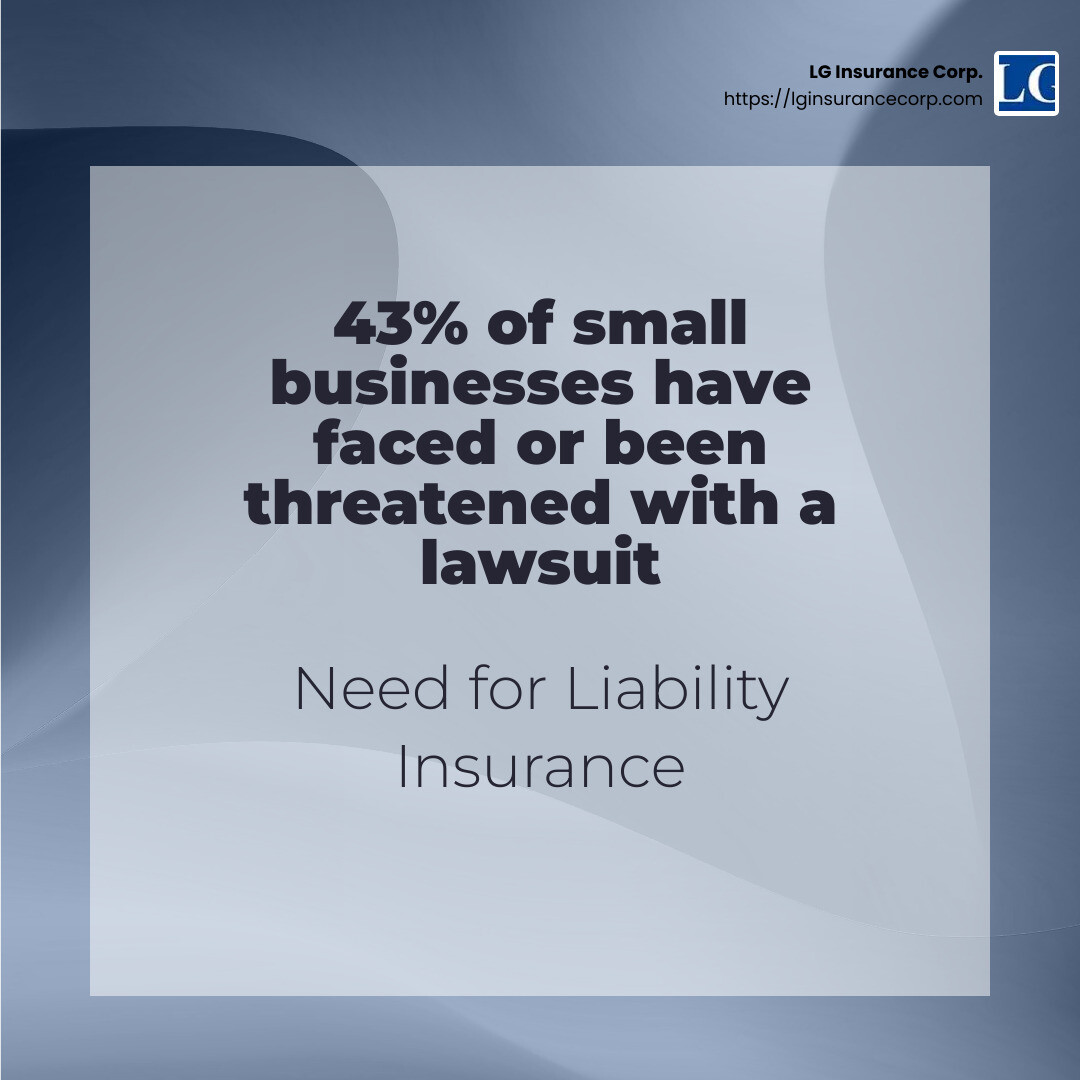
The goal of sole proprietor liability insurance is financial protection. It shields you from unexpected expenses that could otherwise jeopardize your business and personal assets. According to a study, 43% of small businesses have faced or been threatened with a lawsuit. Without insurance, the financial impact of such events could be devastating.
Investing in the right insurance isn’t just about compliance—it’s about peace of mind. Knowing you’re protected allows you to focus on growing your business, rather than worrying about what might go wrong.
Types of Sole Proprietor Liability Insurance
When you’re a sole proprietor, having the right insurance can make all the difference. Let’s break down the key types of sole proprietor liability insurance you should consider:
General Liability Insurance
This is the bread and butter of business insurance. General liability insurance covers everyday mishaps, like if a customer trips and falls at your office. It also protects against property damage and personal injuries that occur on your business premises. For many sole proprietors, this is a must-have, especially if you lease commercial space. In fact, it might even be required by your landlord.
Professional Liability Insurance
Also known as errors and omissions (E&O) insurance, this coverage is crucial for those offering professional services or advice. If you make a mistake that causes a client financial harm, professional liability insurance can cover legal costs and settlements. This is especially important for fields like accounting, consulting, and real estate, where even a small error can lead to a big lawsuit.
Workers’ Compensation Insurance
If you have employees, workers’ comp is often required by law. It covers medical expenses and lost wages if an employee gets injured or sick due to work. Even if you’re a one-person operation, it’s worth checking your state’s requirements, especially if you hire subcontractors or temporary workers.
Commercial Auto Insurance
If you drive for work—whether it’s for deliveries, client meetings, or transporting goods—personal auto insurance often won’t cut it. Commercial auto insurance covers accidents that happen during business activities, protecting you from repair costs and medical bills. This is essential if your business relies on vehicles.
Business Owner’s Policy (BOP)
A BOP bundles general liability and commercial property insurance into one convenient package. It’s a cost-effective way to get comprehensive coverage for your business. This policy is particularly beneficial for sole proprietors who want to protect their physical assets along with liability coverage.
Each type of insurance serves a unique purpose, helping shield your business from different risks. Choosing the right mix of policies depends on your specific business needs and activities. By understanding these options, you can better protect your sole proprietorship from unexpected challenges.
How Much Does Sole Proprietor Liability Insurance Cost?
Understanding the cost of sole proprietor liability insurance is crucial for budgeting and planning. Several factors influence the price you might pay for this coverage.
Risk Exposure
The nature of your business plays a significant role in determining insurance costs. Industries with higher risks—like construction or food services—typically face higher premiums. This is because the likelihood of claims is greater, and insurers price policies accordingly to cover potential payouts.
Location
Where your business operates can also impact your insurance rates. For instance, businesses in areas with higher crime rates or those prone to natural disasters may see increased premiums. Additionally, insurance requirements and costs can vary by state, so understand your local regulations.
Coverage Limits
The amount of coverage you choose directly affects your premium. Higher coverage limits mean more protection, but they also come with higher costs. For example, opting for a $1 million liability policy will generally cost more than a $500,000 policy. It’s important to balance your need for protection with what you can afford.
Claims History
Your past claims can influence what you pay for future policies. A history of frequent claims might signal to insurers that your business is high-risk, leading to increased rates. Conversely, a clean claims record can help you secure lower premiums. Maintaining good safety practices and risk management can help keep your claims history favorable.
In summary, the cost of sole proprietor liability insurance is not one-size-fits-all. It depends on your business’s unique characteristics, from the type of work you do to where you operate. By understanding these factors, you can better anticipate your insurance costs and choose the right coverage for your needs.
Frequently Asked Questions about Sole Proprietor Liability Insurance
Do I need liability insurance as a sole proprietor?
Yes, you do. As a sole proprietor, you are personally liable for all business debts and obligations. This means if your business is sued or faces a claim, your personal assets—like your home or savings—could be at risk. Sole proprietor liability insurance provides a safety net, helping protect your personal assets from business-related liabilities.
How can I protect myself in a sole proprietorship?
Protecting yourself begins with understanding the risks and taking steps to manage them:
Insurance Coverage: Invest in the right types of insurance, such as general liability, professional liability, and errors and omissions insurance. These cover different risks, from customer injuries to professional mistakes.
Risk Management: Implement safety protocols and regular training to minimize accidents and errors. A proactive approach can reduce the likelihood of claims.
Legal Advice: Consult with a lawyer to understand your liabilities and ensure you’re compliant with local regulations. Legal advice can help you structure contracts and agreements to limit personal exposure.
How much is $1 million liability insurance for a sole proprietor?
The cost of a $1 million liability insurance policy varies based on several factors:
Average Cost: Generally, small businesses might pay between $400 and $1,500 annually for a $1 million policy. However, this can fluctuate widely.
Factors Affecting Cost: Your industry, location, claims history, and the specific risks associated with your business all play significant roles in determining your premium.
Coverage Options: You can adjust your policy to balance cost and coverage, such as choosing higher deductibles to lower premiums. It’s crucial to work with an insurance expert to tailor a plan that meets your needs and budget.
Understanding these aspects can help you make informed decisions about protecting your sole proprietorship effectively.
Conclusion
At LG Insurance Corp., we understand that navigating the complexities of business insurance can be overwhelming, especially for sole proprietors who are juggling multiple responsibilities. That’s why we’re committed to offering more than just insurance policies—we provide a customer-centric service that prioritizes your unique needs and challenges.
Our team of experts is here to offer expert advice custom to your specific situation. Whether you’re looking for general liability insurance or need guidance on professional liability coverage, our experienced agents are ready to help you find the right solution. We believe in empowering our clients with the knowledge and tools necessary to protect their businesses and personal assets.
Being a family-owned business in Miami, FL, we value the importance of community support. We strive to build strong relationships with our clients and the local community. Our goal is to be more than just your insurance provider; we aim to be your trusted partner in safeguarding your business against unforeseen risks.
With the right insurance coverage, you can focus on what you do best—running your business—while we handle the rest. For more information on how we can help protect your sole proprietorship, visit our comprehensive liability insurance page.
Let LG Insurance Corp. be your shield in business risks.