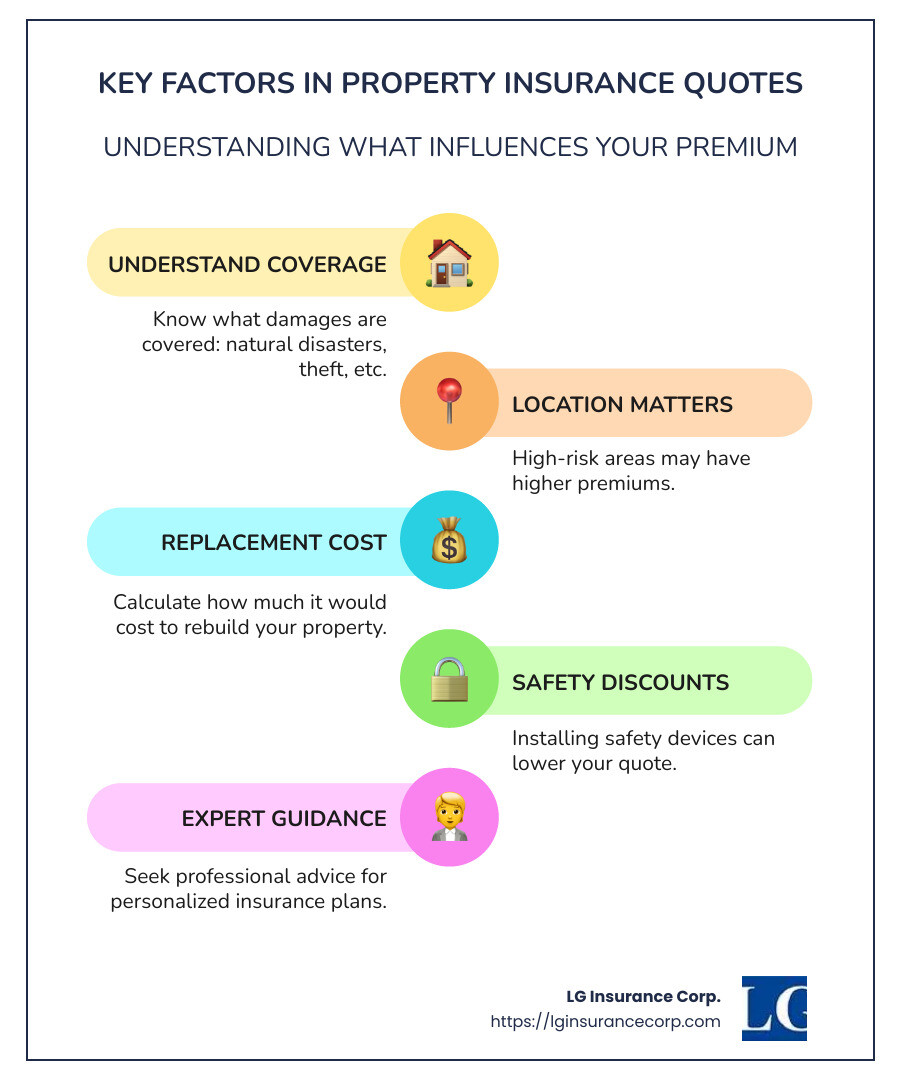
A property insurance quote is an essential piece of information for anyone looking to safeguard their home, office, or rental property. If you’re considering property insurance, there are a few key points to know:
Understand Coverage: Property insurance covers damage or loss related to the property. This includes natural disasters, theft, and sometimes water damage.
Location Matters: The location of your property impacts your insurance rates. High-risk areas, like those prone to floods or hurricanes, typically have higher premiums.
Replacement Cost: It’s crucial to assess how much it would cost to rebuild your property, as this impacts your quote.
Safety Discounts: Installing safety devices like alarms and deadbolts can reduce your quote.
Property insurance is more than just a financial buffer; it is a crucial part of protecting your assets and securing your financial future. With the right policy, you can avoid unexpected expenses due to events like fires, theft, or weather-related damage, ensuring peace of mind for you and your family.
As Leonard Garcia, the founder of LG Insurance Corp with over 20 years of experience in the insurance industry, I am dedicated to helping clients like you steer complex property insurance quotes with ease. My expertise ensures that you receive personalized service, simplifying the insurance process so you can focus on what truly matters.
Understanding Property Insurance
When it comes to property insurance, understanding the different types of coverage is vital. Let’s break down the main components: dwelling coverage, liability coverage, and personal property coverage.
Dwelling Coverage
Dwelling coverage is the backbone of property insurance. It protects the physical structure of your home, including the walls, roof, and foundation, against covered perils like fire, windstorms, and vandalism. If your home is damaged, this coverage helps pay for repairs or rebuilding, ensuring your home can be restored to its original state.
Liability Coverage
Liability coverage shields you from financial responsibility if someone is injured on your property or if you accidentally damage someone else’s property. For instance, if a guest slips on your icy driveway and gets hurt, liability coverage can help cover their medical expenses and any legal fees if they decide to sue. This coverage provides essential protection against potentially costly lawsuits.
Personal Property Coverage
Your belongings matter, and personal property coverage ensures they are protected. This coverage applies to items inside your home, like furniture, electronics, and clothing. If these items are stolen or damaged by a covered event, personal property coverage helps reimburse you for their value. It’s like having a safety net for your personal possessions.
Understanding these coverages helps you make informed decisions when getting a property insurance quote. Each type of coverage plays a crucial role in protecting different aspects of your home and assets, providing peace of mind and financial security.
How to Get a Property Insurance Quote
Getting a property insurance quote can be quick and easy, especially with the convenience of online tools. Here’s how you can steer the process to find the best coverage for your needs.
Online Quotes
Many insurance companies offer online platforms where you can get a quote in minutes. Simply provide some basic details about your property, like the address and year it was built. Online quotes often use public records to fill in the gaps, so you might not need to know every detail about your home. This makes the process faster and less stressful.
Customization
One of the big advantages of getting a quote online is the ability to customize your coverage. You can adjust different aspects like deductibles and coverage limits to see how they affect your premium. Want more coverage for your personal belongings? You can add that. Need extra protection for high-value items like jewelry or art? You can “schedule” these items for additional coverage. Customizing your policy ensures it fits your unique needs.
Discounts
Everyone loves saving money, and property insurance is no exception. Here are some common ways to get discounts:
Bundling: Combine your property insurance with other policies like auto insurance to save. Some companies offer discounts up to 7% or more for bundling.
Safety Devices: Install safety features like burglar alarms, smoke detectors, or fire sprinkler systems. These can lower your risk and your premium.
Claim-Free History: If you’ve been claim-free for a while, you might qualify for a discount. Insurance companies see you as a lower risk if you haven’t filed claims recently.
New Home: Buying a new home? Some insurers offer discounts even if it’s not newly built.
By taking advantage of these discounts, you can lower your premium and make your property insurance more affordable. The key to getting the best property insurance quote is to compare options, customize your coverage, and ask about available discounts.
Factors Affecting Property Insurance Quotes
Several key factors can influence your property insurance quote. Understanding these can help you tailor your policy and potentially save money.
Location
Your home’s location plays a significant role in determining your insurance costs. If you live in an area prone to natural disasters like floods or earthquakes, your premium might be higher. Proximity to fire stations and crime rates in your area also affect your quote. For example, living near a fire station can lower your premium, while a high crime rate might increase it.
Replacement Cost
The replacement cost is the amount it would take to rebuild your home from scratch, not its market value. This includes materials, labor, and even inflation. Homes with unique features or high construction costs will have higher replacement costs, which can increase your insurance premium. It’s crucial to ensure your policy covers the full replacement cost to avoid being underinsured.
Safety Devices
Installing safety devices can significantly reduce your insurance costs. Features like smoke detectors, burglar alarms, and deadbolt locks make your home safer and less likely to suffer damage or theft. Insurance companies often offer discounts for homes equipped with these devices. A safer home means a lower risk for insurers, which translates to savings for you.
Deductible
Your deductible is what you pay out-of-pocket before your insurance kicks in. A higher deductible generally means a lower premium, but it also means more cost if you need to file a claim. It’s important to choose a deductible that fits your financial situation. Balancing your deductible and premium can help you find a policy that suits your budget without sacrificing necessary coverage.
By understanding these factors, you can better steer the process of getting a property insurance quote. Adjusting elements like your deductible or installing safety devices can make a significant difference in your premium. Next, we’ll explore the 80% Rule in Property Insurance and why it matters for your coverage.
The 80% Rule in Property Insurance
The 80% Rule is a crucial concept in property insurance that ensures you have enough coverage to rebuild your home if disaster strikes. Let’s break it down.
Underinsurance
Underinsurance happens when your policy doesn’t cover the full cost to rebuild your home. This can be a big problem if you face a total loss. The 80% Rule helps prevent this by requiring you to insure your home for at least 80% of its replacement cost. If you don’t, you might not get enough money to fully repair or rebuild after a loss.
Replacement Cost
The replacement cost is what it would take to reconstruct your home using similar materials and quality. It’s different from the market value, which includes the land and can be influenced by real estate trends. To avoid underinsurance, calculate your home’s replacement cost accurately. Include labor, materials, and even inflation. This ensures your coverage aligns with the 80% Rule.
Penalties
Failing to meet the 80% Rule can lead to penalties. If your insurance policy covers less than 80% of the replacement cost, the insurer may not fully cover your loss. For instance, if your policy only covers 70% of the replacement cost, you might have to pay a significant portion of the rebuilding costs yourself. This penalty is a way for insurers to encourage adequate coverage.
Here’s a simple table to illustrate:
| Coverage Level | Replacement Cost Coverage | Potential Penalty |
|---|---|---|
| 80% or more | Full coverage | No penalty |
| Less than 80% | Partial coverage | Out-of-pocket costs |
By ensuring your home is insured for at least 80% of its replacement cost, you can avoid these penalties and protect your financial future. Understanding and applying the 80% Rule is crucial for anyone seeking a property insurance quote.
In the next section, we’ll tackle some frequently asked questions about property insurance quotes to help you make informed decisions.
Frequently Asked Questions about Property Insurance Quotes
How can I find affordable property insurance?
Finding affordable property insurance can feel overwhelming, but with a few strategies, you can save money without sacrificing coverage. Here are some tips:
- Shop Around: Get quotes from multiple insurance providers. Prices can vary significantly, so comparing options is key.
- Bundle Policies: Many insurers offer discounts if you combine different types of insurance, like auto and home insurance.
- Increase Your Deductible: A higher deductible can lower your premium. Just ensure you can afford the deductible if you need to make a claim.
- Ask About Discounts: You might qualify for discounts based on safety features like smoke detectors or burglar alarms. Check with your insurer.
- Maintain a Good Credit Score: Insurers often use credit scores to determine premiums. A better score can lead to lower rates.
What is the difference between property insurance and homeowners insurance?
While both types of insurance protect your property, they cover different needs:
Homeowners Insurance: This is a specific type of property insurance for owners of homes. It typically covers the structure, personal belongings, liability, and additional living expenses if you can’t live in your home after a covered loss.
Property Insurance: This is a broader term that can include various types of coverage, such as renters insurance, which protects the belongings of tenants, and flood insurance, which covers damage from flooding—something standard homeowners insurance policies usually don’t cover.
Understanding these differences ensures you get the right coverage for your situation.
What is the average cost of homeowners insurance in South Carolina?
The cost of homeowners insurance varies based on several factors, including location, home value, and coverage limits. In South Carolina, the average cost is often higher than the national average due to the state’s exposure to coastal storms and hurricanes.
National Average: According to recent data, the average annual premium for homeowners insurance in the U.S. is around $1,312.
South Carolina Average: In South Carolina, the average cost is approximately $1,500 per year. This higher cost reflects the increased risk of weather-related damage in the region.
When considering a property insurance quote, compare these averages and understand how your specific circumstances might affect your premium.
In the next section, we’ll conclude our guide with insights on how LG Insurance Corp. can assist you in navigating your property insurance needs.
Conclusion
At LG Insurance Corp., we pride ourselves on being a family-owned agency that puts our customers first. Our focus is on providing customer-centric service, offering expert advice, and supporting our community in Miami, FL. We believe that understanding your insurance needs is crucial, and we are here to help you steer the complexities of property insurance.
Our team is dedicated to creating personalized insurance solutions that protect your most valuable assets. Whether you need coverage for your home, rental property, or business, we work closely with you to ensure you get the right policy at a competitive price.
We understand that insurance can be confusing, but you don’t have to steer it alone. Our experts are here to guide you every step of the way, answering your questions and providing clarity on your coverage options.
Additionally, we are committed to supporting our community by offering resources and information to help you make informed decisions. Our goal is not just to sell insurance but to build lasting relationships with our clients based on trust and reliability.
If you’re looking for a partner who will prioritize your needs and provide comprehensive insurance solutions, consider reaching out to us at LG Insurance Corp. We are here to help you protect what matters most.
For more information on how we can assist with your property insurance needs, visit our Business Property Insurance page. Let’s work together to find the best coverage for you.