Personal liability insurance is your financial safety net, shielding you from unforeseen claims of bodily injury and property damage that you may be held responsible for. In simple terms, it’s a protective blanket that covers legal and financial burdens if someone sues you for accidents that happen on or off your property.
- Provides financial protection from lawsuits and injury claims.
- Covers legal fees if you are sued.
- Helps pay for accidental damage to others’ property.
Imagine hosting a family barbecue and a guest trips over a misplaced toy, injuring themselves. Personal liability insurance steps in, potentially covering medical expenses and legal costs. As crucial as it is, many homeowners overlook this coverage, leaving themselves vulnerable to significant financial risks.
I am Leonard Garcia, founder of LG Insurance Corp. With over 20 years in the industry, I guide clients through the intricacies of Personal liability insurance. My expertise ensures you are equipped with a policy that effectively protects your home and assets.

What is Personal Liability Insurance?
Personal liability insurance is a type of insurance that protects you and your family from the financial fallout of accidents you might be legally responsible for. Think of it as a safeguard for your assets and peace of mind.
Protection for Your Assets
Imagine your home as your biggest investment and a place of countless memories. Personal liability insurance ensures that this asset, along with others, is protected from unforeseen legal claims. If someone gets injured on your property or if your child accidentally damages a neighbor’s property, this insurance can help cover the costs.
Legal Responsibility
When you’re legally responsible for an accident, the financial consequences can be overwhelming. Personal liability insurance covers legal fees, settlements, and medical expenses, allowing you to manage these burdens without draining your savings.
For instance, if a visitor slips on your icy driveway and decides to sue, your personal liability coverage can handle the legal expenses and any compensation you might owe.
Why It’s Important
Without this coverage, you risk facing significant financial strain. The average homeowners insurance policy includes a minimum of $100,000 in personal liability coverage, but higher limits are available if you feel the need for more protection. An umbrella policy can further extend these limits, providing additional peace of mind.
In summary, personal liability insurance is a crucial component of your financial safety net, ensuring that you are prepared for unexpected legal and financial challenges.
Coverage Details of Personal Liability Insurance
When it comes to personal liability insurance, understanding what is covered is crucial to protecting your finances and assets. Here’s a breakdown of the key coverage areas:
Injuries
If someone is injured on your property, personal liability insurance can help cover their medical expenses. For example, if a guest trips over a loose step and breaks an arm, your policy may pay for their hospital bills. This coverage ensures that you won’t have to pay out-of-pocket for someone else’s medical costs.
Property Damage
Accidents happen, and sometimes they result in damage to someone else’s property. Whether your child accidentally throws a ball through a neighbor’s window or you unintentionally cause damage during a visit to a friend’s house, personal liability insurance can cover the repair or replacement costs. This helps prevent small mishaps from becoming financial burdens.
Lawsuits and Legal Fees
Legal battles can be expensive and stressful. Personal liability insurance provides coverage for legal defense costs if you’re sued. Suppose a delivery person slips on your icy front porch and files a lawsuit against you. Your insurance can cover attorney fees, court costs, and any settlements or judgments, up to your policy limits. This protection allows you to focus on resolving the issue without worrying about the legal expenses.
Dog Bites
Dog bites are a common source of liability claims. If your pet bites someone, personal liability insurance can cover medical bills and legal costs associated with the incident. However, it’s important to note that some policies may have exclusions or limitations for certain breeds, so check with your provider to understand the specifics.

In summary, personal liability insurance covers a wide range of incidents, from injuries and property damage to legal fees and dog bites. By understanding these coverage details, you can ensure you have the right protection in place for life’s unexpected events.
What Personal Liability Insurance Does Not Cover
While personal liability insurance offers broad protection, it’s important to know its limits. Here are some key scenarios that are not covered:
Car Accidents
Personal liability insurance does not cover car accidents. For these incidents, you’ll need auto insurance with liability coverage. This is because auto insurance is specifically designed to handle the unique risks associated with driving. If you cause an accident, your car insurance will cover the damages and injuries you are responsible for, not your personal liability policy.
Intentional Harm
If you intentionally cause harm or damage, personal liability insurance won’t cover you. Insurance is designed to protect against accidents and unforeseen events, not deliberate actions. For example, if you purposely break someone’s window, you’ll be responsible for the repair costs out of your own pocket.
Business Claims
Personal liability insurance is meant for personal matters, not business-related incidents. If you’re running a business, even from home, you need a separate business insurance policy. This includes coverage for things like customer injuries or property damage related to your business activities. A business owners policy would be more appropriate in such cases.
Own Injuries
Your own injuries or property damages are not covered by personal liability insurance. This type of insurance is designed to protect you against claims made by others. For personal injuries, you’d need health or medical insurance. For property damage, your homeowners insurance would come into play.
Understanding these exclusions is crucial. It helps ensure that you have the right types of insurance in place to cover all aspects of your life.
How Much Personal Liability Coverage Do You Need?
Deciding on the right amount of personal liability insurance coverage is crucial for safeguarding your assets and peace of mind. Here’s a simple guide to help you determine the right coverage for your needs.
Coverage Limits
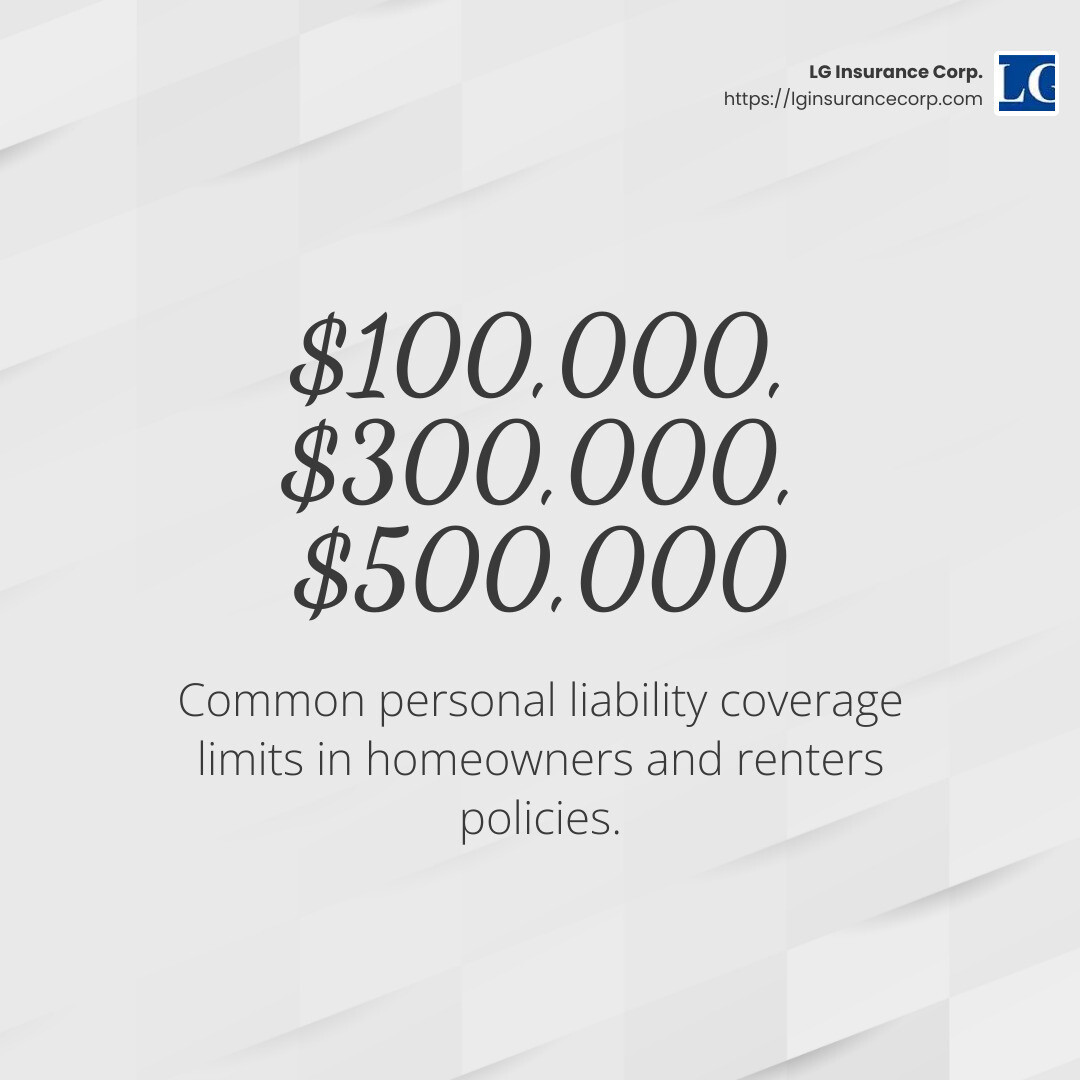
Homeowners and renters policies usually offer personal liability coverage limits of $100,000, $300,000, and $500,000. It’s important to choose a limit that adequately protects your financial assets.
Pro tip: A good rule of thumb is to select a coverage limit that matches or exceeds your net worth. For instance, if your total net worth is $150,000, consider opting for at least $300,000 in coverage to ensure you’re fully protected.
Net Worth
Your net worth plays a significant role in deciding how much coverage you need. The goal is to have enough insurance to cover your total assets in the event of a lawsuit. This includes your home, savings, investments, and any other valuable possessions. If your assets exceed $500,000, you might want to consider an umbrella policy to extend your coverage even further.
Risk Assessment
Assessing the risks associated with your lifestyle and property can also guide your decision. Here are a few questions to consider:
- Do you often host large gatherings at your home?
- Do you have a teenage driver in the family?
- Are you a landlord or rent out a property?
If you answer “yes” to any of these, you might face a higher risk of liability claims and should consider higher coverage limits.
Attractive Nuisances
Certain features of your property, known as “attractive nuisances,” can increase your liability risk. These include swimming pools, trampolines, or even a treehouse. Such features could entice children to enter your property, potentially leading to accidents.
To mitigate these risks, consider these precautions:
- Add a fence around your swimming pool with a locking gate.
- Secure your trampoline with a safety net.
By taking these steps, you not only lower risk but might also qualify for more affordable homeowners insurance.
In summary, when determining how much personal liability insurance you need, consider your net worth, lifestyle risks, and any attractive nuisances on your property. This approach will help you select coverage that provides comprehensive protection.
Cost and Acquisition of Personal Liability Insurance
When it comes to personal liability insurance, understanding the cost and how to acquire the right policy is essential for effective financial protection. Let’s break down the key factors involved.
Cost Factors
Personal liability insurance is often one of the most affordable parts of a home insurance policy. You can usually increase your coverage limit without dramatically raising your monthly premium. The cost largely depends on:
Coverage Limits: Higher limits generally mean higher premiums. However, the increase is often modest compared to the added protection.
Risk Factors: If your property has features like a swimming pool or trampoline, your premiums might be higher due to increased risk.
Location: Where you live can affect your rates. Areas prone to natural disasters or with high crime rates might see increased premiums.
Policy Acquisition
Acquiring personal liability insurance is straightforward. Here are the main steps:
Evaluate Your Needs: Assess your assets, lifestyle risks, and any attractive nuisances on your property to determine the coverage you need.
Choose a Policy: You can get personal liability coverage through homeowners, renters, or condo insurance policies. If you need more coverage, consider an umbrella policy.
Get a Quote: You can obtain a quote online or by contacting an insurance agent. This helps you understand the cost and coverage options available.
Purchase the Policy: Once you’ve decided on the coverage, you can purchase the policy through your chosen insurance provider.
Customizable Coverage Limits
While this guide doesn’t focus on specific companies, it’s worth noting that many insurers offer customizable personal liability insurance as part of their home insurance packages. Policies typically come with coverage limits of $100,000, $300,000, and $500,000, but you can opt for an umbrella policy if you need more extensive protection.
By understanding these cost factors and acquisition steps, you can make informed decisions about your personal liability insurance needs. This ensures you’re adequately protected without overspending.
Frequently Asked Questions about Personal Liability Insurance
What are the benefits of personal liability insurance?
Security: Personal liability insurance provides a safety net for unforeseen events. If someone is injured on your property or if you accidentally damage someone else’s property, this insurance helps cover the costs. It protects your finances from the high expenses of legal claims and medical bills.
Flexible Asset Management: While the primary aim is protection, having personal liability insurance allows you to manage your assets more flexibly. You can focus on other investments or savings, knowing that you have coverage for potential liabilities.
What counts as a personal liability?
Accidents: These are unexpected events that can happen to anyone. For example, a guest might slip on your icy driveway and sustain an injury. Personal liability insurance can cover such incidents, providing financial help for medical costs or legal fees.
Bodily Injury: If someone gets hurt on your property or due to your actions, you may be held responsible. This insurance can cover medical expenses and legal defense costs if you’re sued.
Property Damage: Accidents that damage someone else’s property, like a tree from your yard falling onto a neighbor’s car, are also covered. This helps you avoid paying out-of-pocket for repairs or replacements.
How does personal insurance work?
Financial Consequences: Personal liability insurance takes care of the financial burden resulting from accidents and injuries. If you’re found legally responsible, the insurance covers the costs up to your policy limit, protecting your savings and assets.
Life and Health Protection: While personal liability insurance doesn’t cover your own injuries, it ensures that others’ health-related expenses are managed without draining your resources. This way, you can maintain your lifestyle and focus on recovery or other priorities.
This insurance acts as a shield, safeguarding your financial well-being while allowing you to handle life’s unexpected moments with greater confidence.
Conclusion
In summary, personal liability insurance is a crucial part of safeguarding your financial future. It acts as a protective shield, covering costs associated with unforeseen accidents and legal claims. Whether it’s a slip on your property or an accidental damage to a neighbor’s belongings, having this insurance means you won’t have to bear the financial burden alone.
At LG Insurance Corp., we understand the importance of comprehensive coverage custom to your needs. Our family-owned agency in Miami, FL, is dedicated to providing expert advice and personalized service. We believe in supporting our community by ensuring that you and your assets are well protected.
Our team is here to guide you through the complexities of insurance, helping you make informed decisions about your coverage. We focus on delivering customer-centric service, ensuring that you feel confident and secure with your insurance choices.
Life’s unexpected moments can happen at any time. With the right coverage from LG Insurance Corp., you can face them with peace of mind. Reach out to us for expert advice and let us help you find the best personal liability insurance solution for your unique situation.