Personal liability insurance quote is a term that often pops up when seeking financial protection through a homeowners policy. Understanding this concept is crucial because it helps safeguard you and your family from potential legal responsibilities. This type of insurance covers claims arising from incidents like a visitor slipping on your driveway or your child accidentally breaking a neighbor’s window. Considering the complexities and potential consequences of such situations, obtaining a personal liability insurance quote is a smart move. Here’s a quick breakdown of what you need to know:
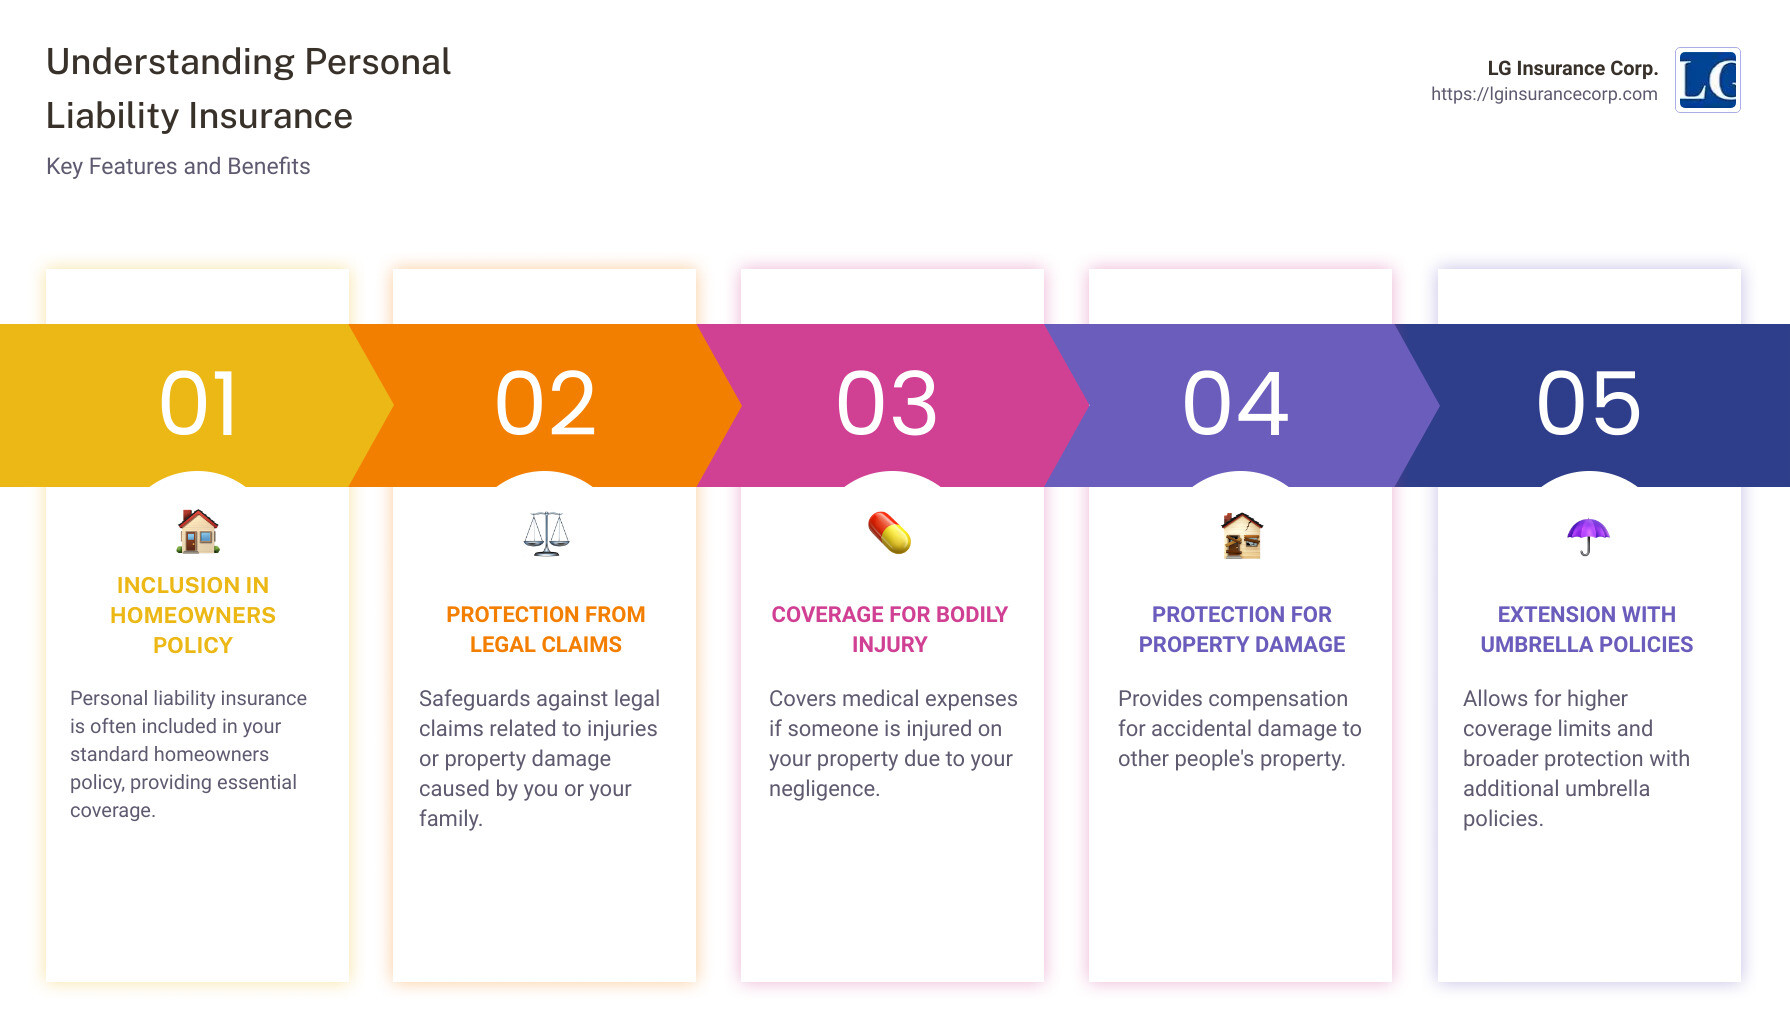
- Personal liability insurance is typically included in your homeowners policy.
- It protects against legal claims from injuries or property damage.
- Coverage can be extended with umbrella policies if needed.
As someone deeply rooted in the Miami, FL insurance scene, I am Leonard Garcia, ready to guide you in securing a personal liability insurance quote. With over 20 years of experience, I am dedicated to ensuring you have the protection you need. Let’s dive into understanding personal liability insurance in depth.
Glossary for personal liability insurance quote:
– Personal liability insurance
– best personal liability insurance
– cheap personal trainer insurance
Understanding Personal Liability Insurance
Personal liability insurance is like a safety net. It protects you from financial loss if someone claims you caused them injury or damaged their property. This coverage is usually part of your homeowners policy, but you can also get it separately if needed.
Coverage Limits
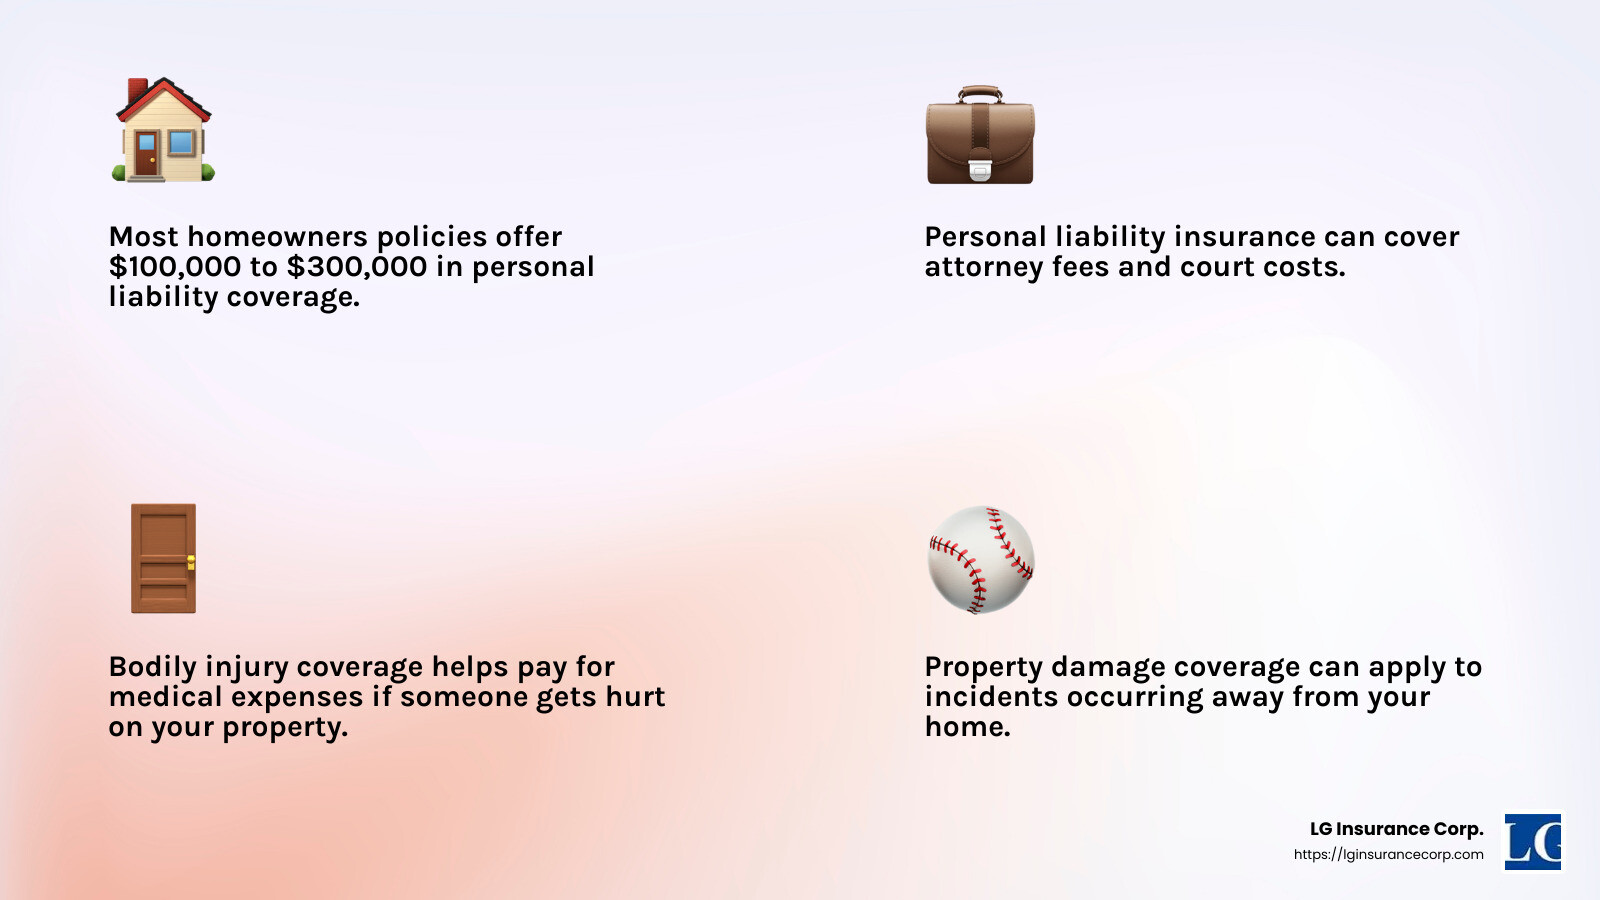
Coverage limits define the maximum amount your insurance will pay for a claim. Most homeowners policies offer between $100,000 and $300,000 in personal liability coverage. If you think this isn’t enough, you can increase your limits or add an umbrella policy for extra protection.
Bodily Injury
Bodily injury coverage helps pay for medical expenses if someone gets hurt on your property. For example, if a mail carrier slips on your icy driveway, your insurance can cover their medical bills. This type of coverage can also help pay for legal fees if the injured person decides to sue you.
Property Damage
Accidents happen. If your child throws a baseball through a neighbor’s window, property damage coverage can help pay for repairs or replacements. This coverage is not limited to your home; it can also apply to incidents that occur away from your property.
Legal Expenses
Legal battles can be costly. Personal liability insurance can cover your legal expenses if you’re sued for an accident. This includes attorney fees, court costs, and any settlements up to your coverage limits.
In summary, personal liability insurance is essential for protecting your finances from unexpected claims. By understanding coverage limits, bodily injury, property damage, and legal expenses, you can be better prepared for life’s surprises.
Up next, we’ll explore how to get a personal liability insurance quote and the options available to you.
How to Get a Personal Liability Insurance Quote
Getting a personal liability insurance quote is simpler than you might think. Here’s a quick guide to help you through the process.
1. Choose Your Coverage Options
First, consider what coverage you need. Do you want basic protection, or are there specific risks you need to cover? Standard policies usually include coverage for bodily injury, property damage, and legal expenses. But if you have a swimming pool or a trampoline, you might want to opt for higher limits or additional coverage like an umbrella policy.
2. Gather Your Information
Before you start, gather some basic information. This typically includes details about your property, any previous claims, and your current insurance limits. Having this information handy will make the process smoother and quicker.
3. Get Online Quotes
Many insurers offer online tools to get a personal liability insurance quote. These tools allow you to compare different policies and their costs. Simply enter your information, choose your coverage options, and get instant quotes. This can be a convenient way to see what different companies offer without having to call each one.
4. Talk to an Insurance Agent
While online quotes are helpful, speaking with an insurance agent can provide more personalized advice. Agents can explain policy details, recommend coverage based on your specific needs, and help you understand any exclusions or limitations.
5. Compare and Choose
Once you have your quotes, compare them. Look at the coverage limits, premium costs, and any additional benefits. Make sure the policy you choose meets your needs and fits your budget.
By following these steps, you can easily get a personal liability insurance quote and find the best coverage for your situation.
Next, we’ll dive into what personal liability insurance covers, from medical bills to pet-related damages.
What Does Personal Liability Insurance Cover?
Personal liability insurance is a safety net that protects you financially if you’re found responsible for causing harm to someone else or their property. Let’s break down what this type of insurance typically covers:
Medical Bills
If someone gets hurt on your property, personal liability insurance can help cover their medical expenses. This is crucial because medical bills can quickly add up, even for minor injuries. The coverage usually starts at $1,000 per person, but you can opt for higher amounts if needed.
Negligent Acts
Accidents happen, and sometimes they’re due to negligence. Whether it’s a slip on an icy walkway or a fall from a poorly maintained deck, personal liability insurance can cover the costs if you’re found liable. This includes legal fees and any settlements or judgments against you.
Pet-Related Damages
Our furry friends can sometimes cause trouble. If your pet injures someone or damages their property, personal liability insurance can cover the associated costs. This includes medical expenses for injuries and repair costs for damaged property. It’s a relief to know you’re protected, even if Fido has a bad day.
Legal Costs
Legal battles can be expensive. If you’re sued for an incident covered by your policy, personal liability insurance can cover your legal defense costs. This includes attorney fees, court costs, and any settlements or judgments. It’s like having a financial shield in the courtroom.
Understanding these coverages can help you see why personal liability insurance is an essential part of protecting your assets and lifestyle.
Next, we’ll explore what isn’t covered by personal liability insurance, so you know where you might need additional protection.
What Isn’t Covered by Personal Liability Insurance?
While personal liability insurance offers valuable protection, it’s important to know its limitations. Here’s a look at what typically isn’t covered:
Car Accidents
Personal liability insurance does not cover car accidents. For these situations, you’ll need auto insurance, which includes liability coverage for injuries and property damage resulting from car accidents. This is a separate policy designed specifically for vehicle-related incidents.
Intentional Harm
If you intentionally cause harm to someone or their property, your personal liability insurance won’t cover it. Insurance policies are designed to protect against accidents and unintentional acts, not deliberate actions. Intentional harm falls outside the scope of coverage.
Business Claims
Running a business from home? Personal liability insurance doesn’t cover business-related claims. If a client slips and falls in your home office, or if you’re sued for professional negligence, you’ll need a separate business liability policy. This ensures that your business activities are properly insured.
Exclusions
Insurance policies come with exclusions, which are specific situations or items not covered. Common exclusions include damage from natural disasters, like floods or earthquakes, and certain high-risk activities. Always read your policy carefully to understand these exclusions and consider additional coverage if needed.
By knowing what isn’t covered, you can make informed decisions about additional insurance policies you might need. This way, you can ensure comprehensive protection for all aspects of your life.
Next, we’ll discuss how much personal liability coverage you might need to adequately protect your assets.
How Much Personal Liability Coverage Do You Need?
Determining the right amount of personal liability coverage is crucial to protecting your assets. Here’s how you can assess your needs:
Net Worth and Coverage Limits
A good rule of thumb is to match or exceed your net worth with your liability coverage. For example, if your total net worth is $150,000, consider opting for at least $300,000 in coverage. This ensures that you’re not left financially vulnerable in the event of a lawsuit.
Homeowners and renters policies often offer coverage limits of $100,000, $300,000, or $500,000. If you need more than $500,000 in coverage, an umbrella insurance policy can extend your limits beyond those of your standard insurance.
Attractive Nuisances
Do you own a swimming pool or trampoline? These are considered “attractive nuisances,” meaning they can entice children and increase the risk of accidents on your property. If you have any such features, consider increasing your coverage limit to account for the heightened risk.
Taking precautions, like adding a fence around your pool, can help reduce risk and might even lower your insurance premiums.
Risk Assessment
Assessing the risk factors in your life is essential. Do you host large parties? Own a dog? Have teenage drivers in the family? Each of these situations can increase your liability risk. The more risks you have, the more coverage you should consider.
You can also evaluate your property for potential hazards and take steps to mitigate them. This proactive approach not only improves safety but also helps in deciding your coverage needs.
By understanding your net worth, assessing risks, and considering attractive nuisances, you can choose the right amount of personal liability coverage to safeguard your financial future.
Next, we’ll dive into frequently asked questions about personal liability insurance, including costs and legal requirements.
Frequently Asked Questions about Personal Liability Insurance
What is the typical cost of liability insurance?
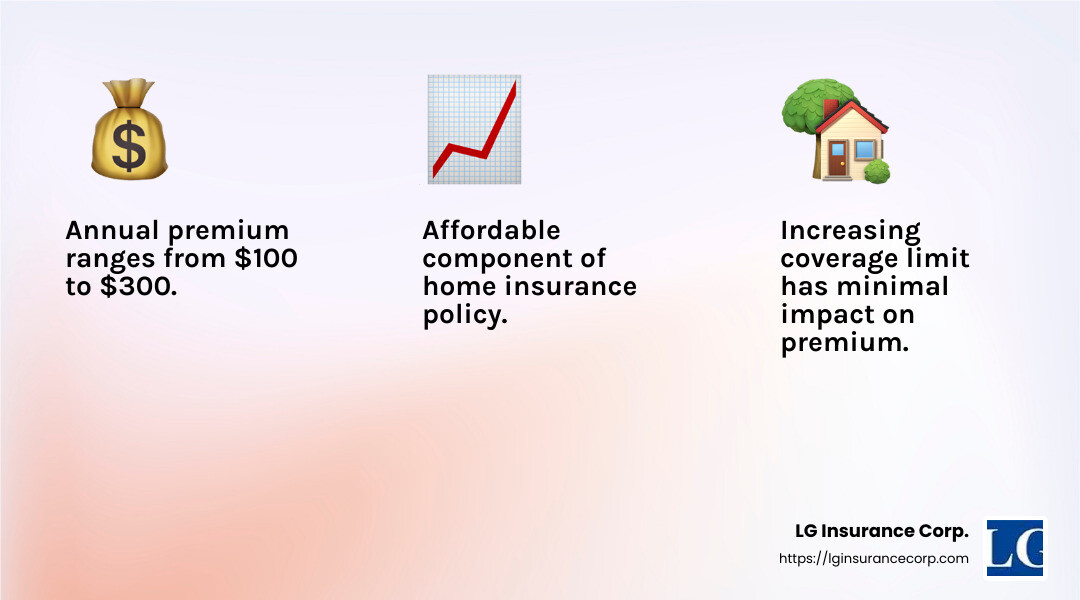
The cost of personal liability insurance is often one of the most affordable components of a home insurance policy. On average, the annual premium for personal liability coverage can range from $100 to $300, depending on factors such as the coverage limit and the insurer. Increasing your coverage limit often doesn’t drastically affect your monthly premium, making it a cost-effective way to protect your assets.
How do you calculate personal liability?
Calculating the right amount of personal liability coverage involves a few key steps:
Net Worth: Start by determining your total net worth. This includes your savings, investments, and the value of your home and other assets.
Asset Value: Consider the value of your assets that could be at risk in a lawsuit. This might include your home, car, and any other valuable possessions.
Coverage Limit: Choose a coverage limit that matches or exceeds your net worth. For instance, if your net worth is $200,000, you should consider a coverage limit of at least $300,000.
By assessing your net worth and asset value, you can select a coverage limit that offers adequate protection.
Do individuals need liability insurance?
While personal liability insurance is not legally required like auto insurance, it is highly recommended for anyone with assets to protect. It serves as a personal protection measure, safeguarding you from financial ruin in case of accidents or lawsuits. If you own a home, car, or have savings, having liability insurance is a prudent decision.
Personal liability insurance acts as a financial safety net, providing peace of mind and protecting your future. Even if you’re not legally obligated to have it, the benefits far outweigh the costs, especially when considering potential legal expenses and settlements.
Conclusion
Navigating insurance can be complex, but at LG Insurance Corp., we strive to make it simple and straightforward. As a family-owned agency based in Miami, FL, we offer comprehensive personal and business insurance solutions that cater to your unique needs. Our focus on customer-centric service ensures that you receive expert advice custom to your situation.
Personal liability insurance is a critical component of protecting your assets and financial future. Our team is dedicated to helping you understand your options and choose the right coverage limits that align with your lifestyle and risk exposure. We know that peace of mind comes from knowing you’re protected, and we’re here to provide that assurance.
Moreover, our commitment extends beyond just offering insurance. We are deeply invested in supporting our community. Whether it’s through educational workshops or community events, we aim to empower individuals with the knowledge they need to make informed decisions about their insurance needs.
For those looking to secure their financial future with a personal liability insurance quote, we invite you to explore our offerings. Our team is ready to assist you every step of the way, ensuring that you have the coverage you need to live confidently and securely.
To get started, visit our Comprehensive Liability Insurance page and let us help you protect what matters most.