Miami whole life insurance serves as a financial safety net for you and your loved ones. Whether you’re contemplating term or whole life policies, these insurance options provide monetary support by paying out a sum to your chosen beneficiaries. Miami whole life insurance, in particular, offers lifelong coverage and can even serve as a source of income through its cash value component.
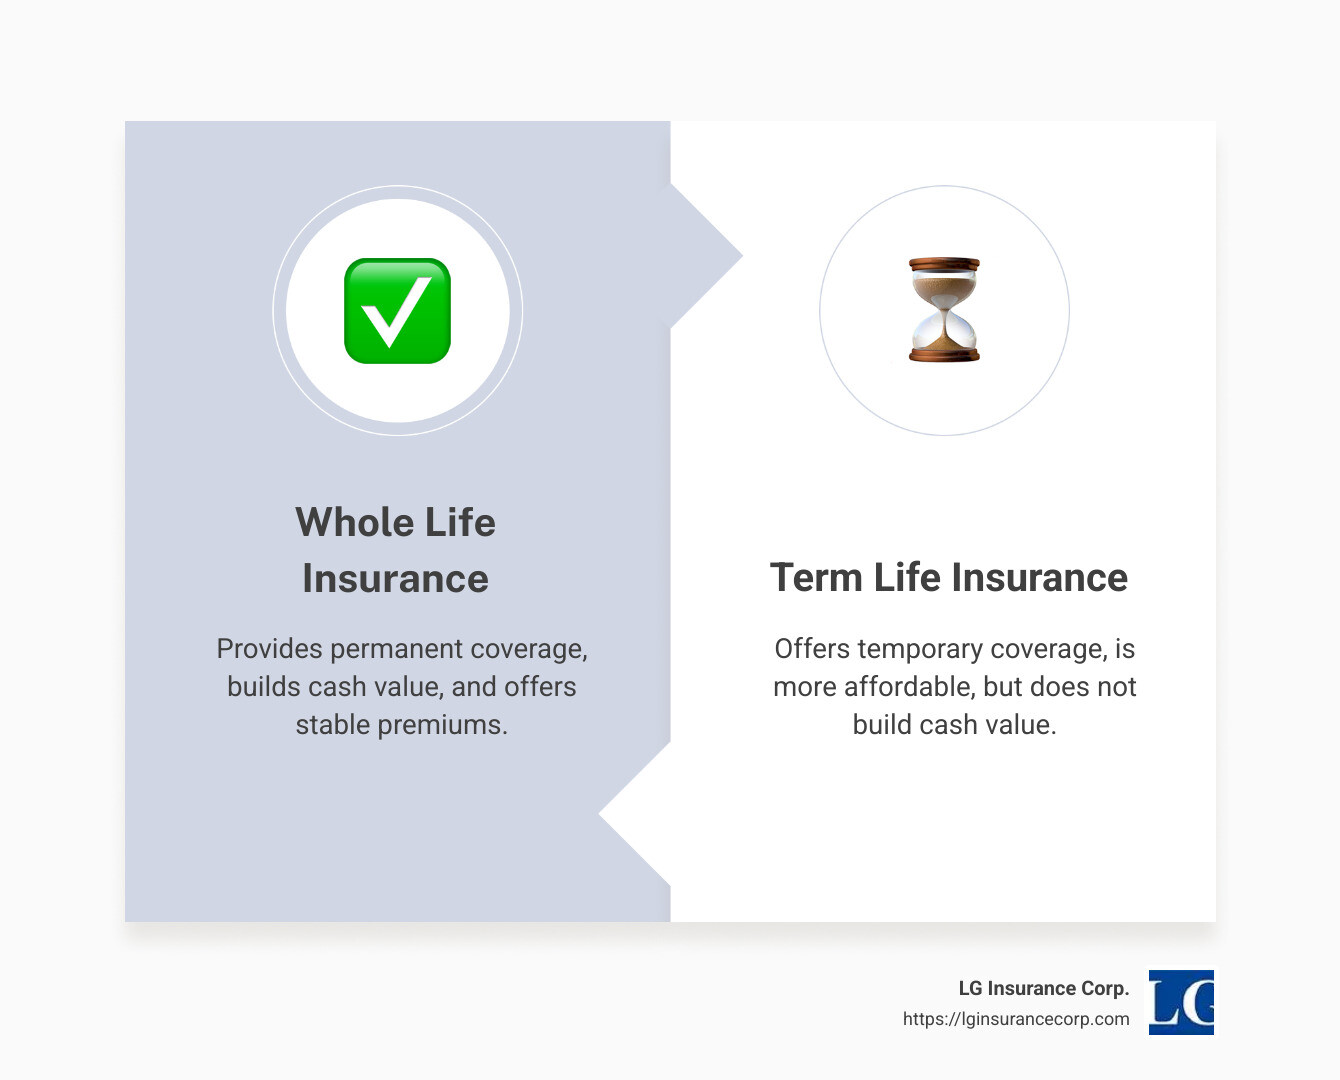
- Whole Life Insurance: Permanent, builds cash value, stable premiums
- Term Life Insurance: Limited term, affordable, doesn’t build cash value
- Financial Planning: Ensures family’s financial security, peace of mind
Why choose life insurance in Miami? When life takes unexpected turns, having insurance ensures you’re prepared. Understanding the nuances of each can make a big difference. If you’re tight on time, this intro outlines the basic benefits so you’re more equipped to decide without reading further.
As Leonard Garcia, owner of LG Insurance Agency in Miami, I bring over 20 years of expertise in life insurance solutions to the table. Having worked extensively within South Florida, I understand the community’s unique needs, ensuring you get the right coverage for financial peace of mind.
Miami whole life insurance word guide:
Understanding Whole Life Insurance
Whole life insurance is a type of permanent coverage that lasts for your entire life, as long as you keep up with the premium payments. Unlike term life insurance, which only covers you for a set period, whole life insurance offers several key benefits and some drawbacks.
Benefits of Whole Life Insurance
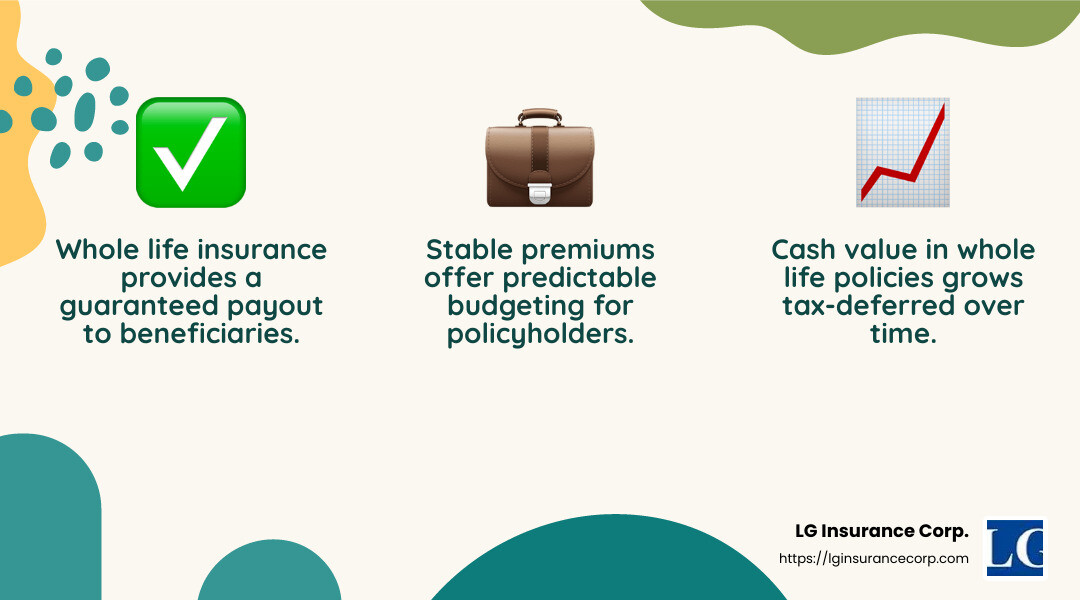
Guaranteed Payout: One of the standout features of whole life insurance is the guaranteed death benefit. This ensures that no matter when you pass away, your beneficiaries will receive a predetermined sum of money. This financial security can help cover significant expenses like mortgage payments, college tuition, or everyday living costs.
Financial Security: Whole life insurance provides peace of mind by ensuring your loved ones are financially secure. This is crucial during difficult times when they might need support the most.
Cash Value Growth: Whole life policies come with a cash value component that grows over time. As you pay your premiums, a portion is set aside in a tax-deferred savings account. This cash value can be borrowed against or withdrawn under certain conditions, offering a financial cushion for emergencies or other goals, like funding a business.
Stable Premiums: Unlike term life insurance, which can see premiums increase over time, whole life insurance offers stable premiums throughout the life of the policy. This predictability makes it easier to budget, knowing your premium payments won’t suddenly skyrocket with age or health changes.
Drawbacks of Whole Life Insurance
Higher Premiums: The stability and benefits of whole life insurance come at a cost. Premiums for whole life policies are generally higher than those for term life insurance. This might be a consideration if you are looking for more affordable coverage options.
Complexity: Whole life insurance policies can be more complex than term life policies. Understanding the cash value component and the conditions for borrowing or withdrawing funds can be complicated.
Potential Cost: While the cash value component can be beneficial, it may also lead to additional costs if you decide to borrow against it or withdraw funds. It’s essential to understand these potential costs before committing to a policy.
In summary, Miami whole life insurance provides lifelong coverage and financial security for your beneficiaries, with the added benefit of cash value growth. However, the higher premiums and complexity of these policies might be a drawback for some. It’s crucial to weigh these factors carefully to determine if whole life insurance is the right choice for you.
Next, we’ll dig into understanding term life insurance and how it compares to whole life policies.
Understanding Term Life Insurance
Term life insurance is like a rental agreement for life coverage. It provides protection for a specific period, known as the term. This could be 10, 20, or even 30 years. If you pass away during this term, your beneficiaries receive a death benefit. If the term expires while you’re still alive, the coverage ends, and there’s no payout.
Benefits of Term Life Insurance
Affordability: Term life insurance is generally cheaper than whole life insurance. This makes it an attractive option for those who need coverage but are on a budget. You can get significant coverage at a lower cost, which is great for young families or those just starting their financial planning.
Lower Premiums: Since term life insurance covers you for a limited time, the premiums are usually lower compared to whole life insurance. This can help you allocate your budget to other financial needs while still ensuring your family is protected.
Flexibility: Term life insurance offers flexibility in choosing the length of the coverage. You can select a term that matches your financial goals, such as covering the years until your children are financially independent or until your mortgage is paid off.
Specific Term: With term life insurance, you know exactly how long you’re covered. This specificity allows you to plan around major life events, like paying off debts or saving for retirement.
Drawbacks of Term Life Insurance
No Cash Value: Unlike whole life insurance, term policies do not build cash value. This means you can’t borrow against the policy or withdraw funds. The premiums you pay only go towards the death benefit, with no savings component.
Policy Expiration: Once the term ends, so does your coverage. If you still need life insurance, you’ll have to reapply for a new policy. This can be a problem if your health has changed, potentially leading to higher premiums or even denial of coverage.
Reapplication: At the end of the term, if you decide to continue coverage, you’ll need to reapply. This process might involve new medical exams and can result in higher premiums due to age or health changes.
Term life insurance provides a straightforward and affordable way to ensure financial protection for your loved ones. However, the lack of cash value and the need to reapply after the term ends are important considerations. If you’re weighing your options, think about your current financial situation and future needs to decide if term life insurance is the right fit for you.
Next, let’s explore the key considerations for Miami whole life insurance and how to choose the right policy for your needs.
Miami Whole Life Insurance: Key Considerations
When considering Miami whole life insurance, it’s crucial to weigh different aspects to ensure you choose a policy that aligns with your financial goals and lifestyle.
Choosing the Right Policy
Coverage Options: Whole life insurance offers permanent coverage, meaning your beneficiaries receive a payout regardless of when you pass away. This can provide peace of mind, knowing that your loved ones are financially secure.
Financial Goals: Whole life insurance isn’t just about the death benefit. It also builds cash value over time. This cash value can be a financial resource during your lifetime, offering options like borrowing against the policy. Consider how this aligns with your long-term financial goals, such as retirement planning or creating an inheritance.
Policy Features: Whole life insurance policies often come with stable premiums, meaning your payments won’t increase as you age. This can be beneficial for budgeting and financial planning, allowing you to know exactly what you’ll pay over time.
Age, Health, and Lifestyle: Your age and health significantly impact the cost of whole life insurance. Generally, the younger and healthier you are, the lower your premiums. Lifestyle choices, like smoking or engaging in high-risk activities, can also influence costs. It’s essential to consider these factors when choosing a policy.
Cost Factors in Miami
Average Costs: The cost of whole life insurance in Miami can vary widely based on several factors, including age, health, and the amount of coverage. On average, premiums for a $100,000 policy might range from a few hundred to several thousand dollars annually.
Influencing Factors: In addition to age and health, the policy’s features, such as riders or additional benefits, can affect the cost. Riders, which are optional add-ons to your policy, can provide extra coverage but often come at an additional cost.
Budgeting: Whole life insurance tends to be more expensive than term life insurance. It’s essential to budget accordingly and consider how premiums fit into your overall financial plan. Think about the trade-off between higher premiums and the benefits of permanent coverage and cash value growth.
Choosing the right Miami whole life insurance policy involves understanding these key considerations and aligning them with your personal and financial circumstances. By doing so, you can ensure that your policy supports your long-term goals and provides the security you desire for your loved ones.
Next, let’s address some frequently asked questions about Miami life insurance to help clarify any remaining uncertainties.
Frequently Asked Questions about Miami Life Insurance
How much does a $100,000 whole life insurance policy cost?
The cost of a $100,000 Miami whole life insurance policy can vary significantly based on several factors. On average, premiums might range from a few hundred to several thousand dollars annually.
Influencing Factors:
- Age: Younger individuals generally pay lower premiums.
- Health: Good health can lead to more affordable rates.
- Lifestyle: Factors like smoking or engaging in high-risk activities can increase costs.
- Policy Features: Additional riders or benefits can also raise premiums.
It’s essential to consider these factors when budgeting for a whole life insurance policy.
What is the downside of whole life insurance?
While whole life insurance offers permanent coverage and cash value growth, there are some downsides to consider:
- Complexity: Whole life policies can be complex, with various features and options that may be difficult to understand.
- Cost: Premiums are generally higher compared to term life insurance.
- Coverage Lapse: If you miss premium payments, there’s a risk of coverage lapse, potentially losing the benefits of the policy.
Carefully weighing these drawbacks against the benefits is crucial when deciding if whole life insurance is right for you.
How does whole life insurance build cash value?
Whole life insurance policies include a cash value component that grows over time. Here’s how it works:
- Tax-Deferred Growth: The cash value grows tax-deferred, meaning you don’t pay taxes on the growth until you withdraw it.
- Borrowing: You can borrow against the cash value, providing a financial resource in times of need. However, unpaid loans can reduce the death benefit.
- Withdrawal Conditions: You may withdraw from the cash value, but this can affect the overall value of the policy and its benefits.
Understanding these aspects of cash value growth can help you maximize the benefits of your whole life insurance policy.
By addressing these frequently asked questions, you can better understand the complexities and benefits of Miami whole life insurance. Next, let’s explore how LG Insurance Corp. can offer expert advice and support to help you make the best decision for your needs.
Conclusion
Choosing the right life insurance policy is a significant decision, and we’re here to help. At LG Insurance Corp., our family-owned agency in Miami is dedicated to providing you with expert advice and personalized service. We understand that life insurance can be complex, and we’re committed to making the process as simple as possible for you.
Expert Advice and Guidance
Our experienced team of licensed agents takes the time to understand your unique needs. We offer clear explanations and custom solutions to ensure you have the right coverage for your financial goals. Whether you’re considering Miami whole life insurance for its permanent coverage and cash value benefits or exploring other options, we’re here to guide you every step of the way.
Community Support and Involvement
We are proud to be a part of the Miami community and actively support local organizations. Our commitment to community involvement means we are not just your insurance provider but also your neighbor. We believe in giving back and supporting the community that supports us.
Get Started with LG Insurance Corp.
Let us help you find peace of mind with the right life insurance policy. Visit our individual life insurance page to learn more about our services and how we can assist you in securing your family’s future. Contact us today to schedule a consultation and take the first step towards financial security.
Thank you for considering LG Insurance Corp. for your life insurance needs. We look forward to serving you and helping you make informed decisions about your insurance coverage.