Miami home insurance rates are crucial to know for both new and seasoned homeowners in this vibrant city. Miami’s unique location, while offering captivating beaches and lively culture, also comes with significant risks like hurricanes and floods, which contribute to higher insurance costs. Here’s a quick snapshot of key points about Miami home insurance rates:
- Average Annual Cost: $8,617 for a $300,000 house
- Common Risks: Hurricanes, floods, and sinkholes
- Savings Opportunity: Implementing wind mitigation can halve premiums
Homeowners here must steer not only the beauty of Miami but also the soaring insurance rates driven by these natural hazards. While some cities in Florida might face different challenges, Miami’s vulnerability to hurricanes and flooding makes adequate homeowners insurance not just essential but potentially costly.
As Leonard Garcia, an insurance expert and founder of LG Insurance Agency, I have over 20 years of experience helping Miami residents find home insurance that meets their unique needs and budgets. Let’s explore the factors that influence Miami home insurance rates and how it affects your peace of mind.
Miami home insurance rates glossary:
– cheap home insurance miami fl
– home insurance companies miami fl
– house insurance in miami
Understanding Miami home insurance rates is essential for homeowners. Miami’s picturesque beaches and vibrant culture come with a price—high insurance costs. On average, homeowners insurance in Miami costs $8,617 per year for a $300,000 house. This is significantly higher than the state average of $6,026 for the same value home.
Average Costs by Home Value
- $150,000 House: The average annual cost is approximately $8,617. However, rates can vary widely depending on the insurer.
- $300,000 House: Expect to pay around $15,602 per year. This cost reflects the added risk associated with higher property values.
- $450,000 House: The average cost jumps to $22,398 annually. As home values increase, so does the potential payout for insurers, thus raising premiums.
Factors Affecting Homeowners Insurance Rates
Several factors can influence the cost of homeowners insurance in Miami:
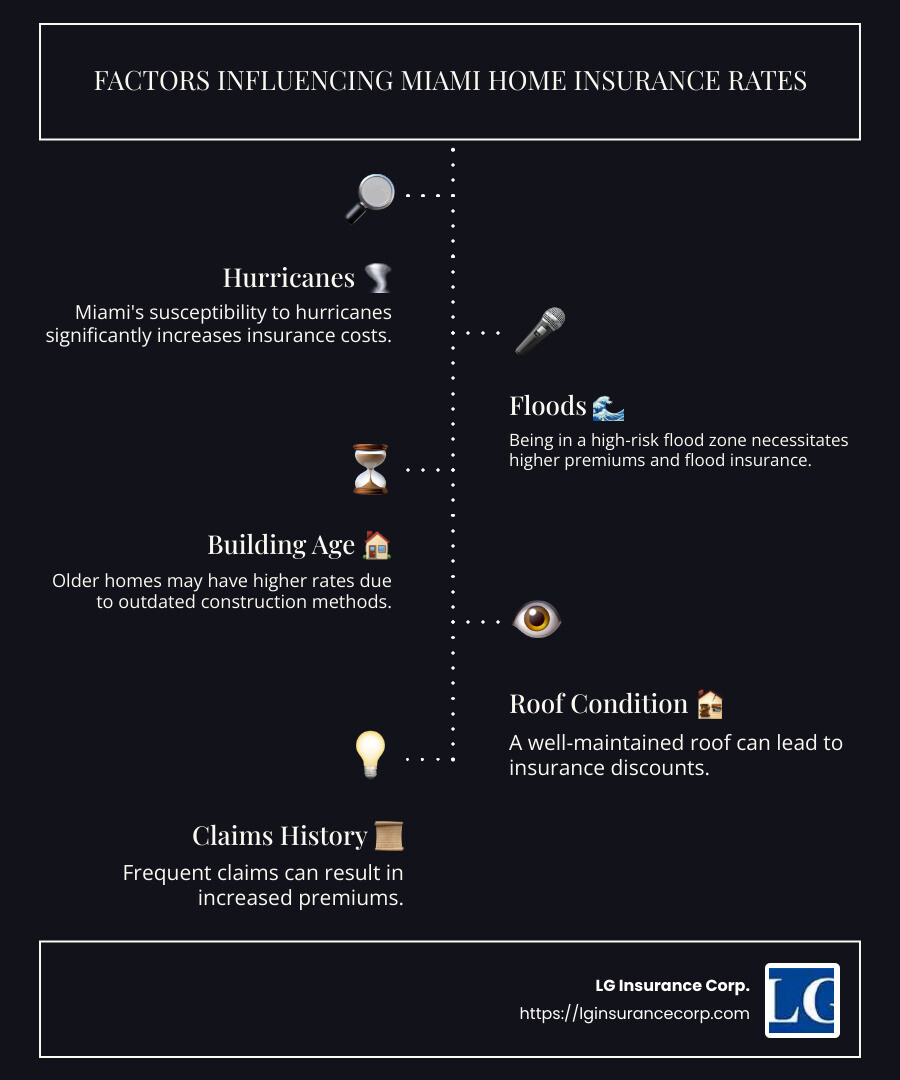
Age of Home: Older homes may have outdated structures and systems, increasing the risk of damage and claims. This can lead to higher premiums.
Roof Condition: A well-maintained roof can significantly lower insurance costs. Insurers often offer discounts for newer roofs or those with wind-resistant features.
Credit History: Insurers use credit scores to assess risk. A good credit score can lead to lower premiums, while poor credit can increase costs.
Claims History: A history of frequent claims can result in higher premiums. Insurers view past claims as indicators of future risk.
Natural Disaster Risk: Miami’s susceptibility to hurricanes and floods heavily impacts insurance rates. Homes in high-risk areas may require additional coverage, such as flood insurance.
Coverage Extent: The more coverage you need, the higher your premium will be. It’s important to balance adequate protection with cost.
Deductible: Choosing a higher deductible can lower your premium. However, it means more out-of-pocket costs in the event of a claim.
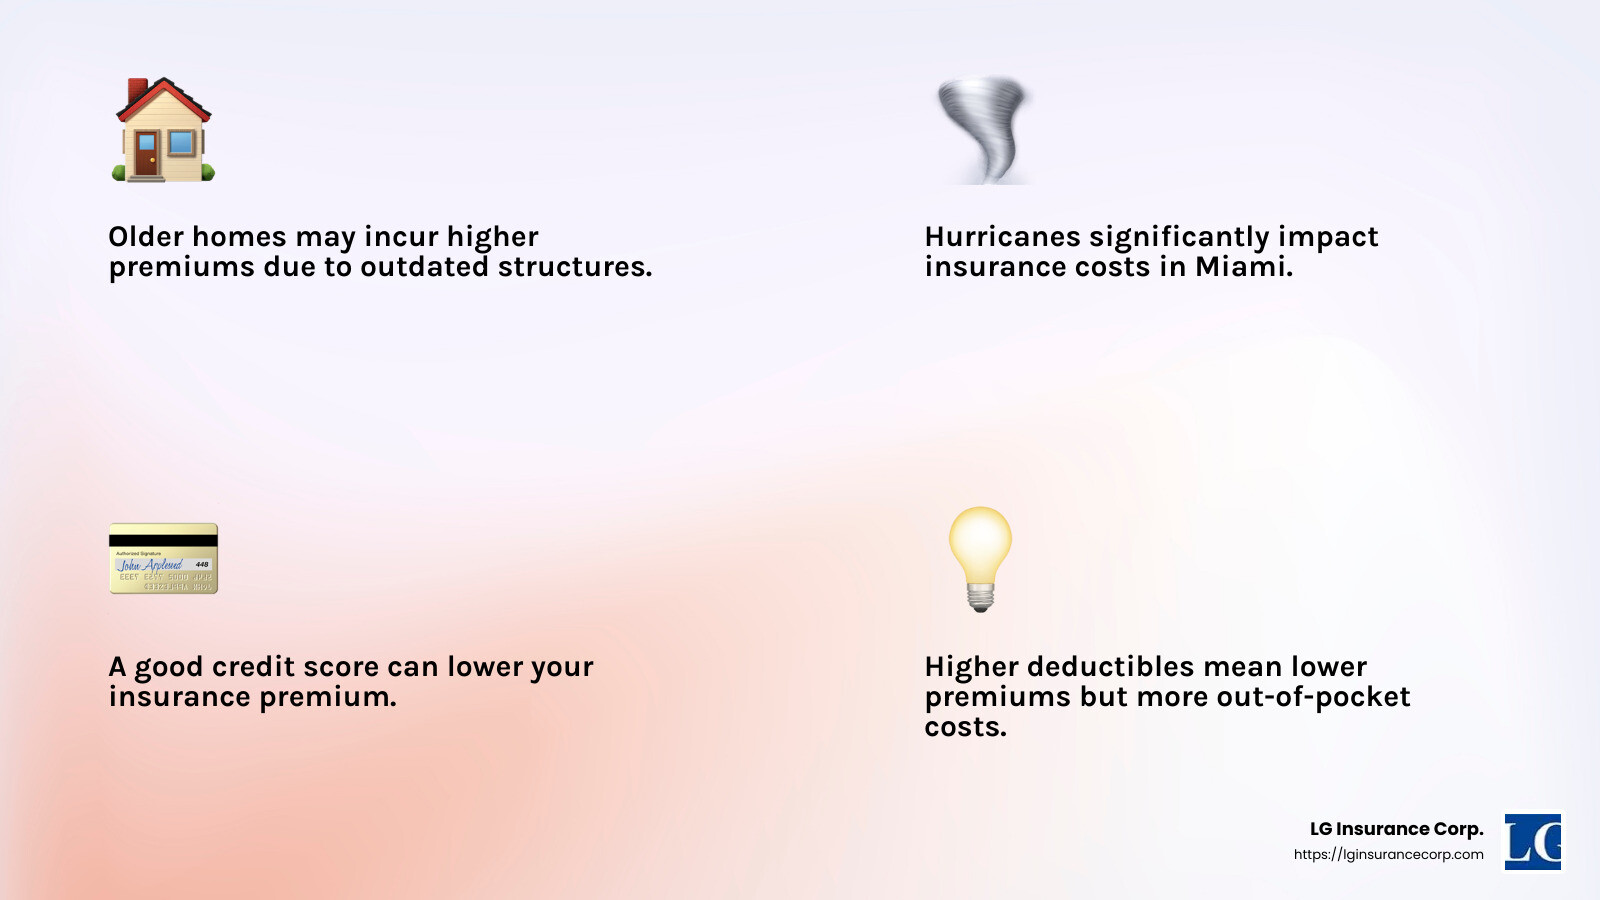
By understanding these factors, Miami homeowners can make informed decisions about their insurance needs, potentially saving money while ensuring they have adequate protection.
Why Is Home Insurance So Expensive in Miami?
Miami is a beautiful place to live, but it’s also one of the most expensive cities for homeowners insurance. Let’s explore why.
Impact of Hurricanes and Floods
Hurricanes and floods are major reasons for high insurance rates in Miami. The city sits in a high-risk area for hurricanes, which can cause severe damage. These storms bring heavy rains and powerful winds, leading to storm surge flooding. Miami’s location on the coast makes it especially vulnerable to these natural disasters.
The Federal Emergency Management Agency (FEMA) designates certain parts of Miami as flood zones. If your home is in one of these high-risk areas, you might need additional flood insurance. This separate policy covers damage from floods, which standard homeowners insurance doesn’t include.
Other Contributing Factors
Beyond natural disasters, other elements contribute to the high cost of home insurance in Miami:
Reinsurance Costs: Insurers buy reinsurance to protect themselves from large claims, especially after hurricanes. These costs have risen, pushing up premiums for homeowners.
Litigation: Florida has seen an increase in insurance-related lawsuits. This legal environment adds to the cost of providing insurance, which is passed on to homeowners.
Crime Rate: Miami’s property crime rate is higher than the national average. This increases the risk for insurers and contributes to higher premiums.
Rebuilding Costs: After a storm, the cost to rebuild is high due to demand for labor and materials. These costs are factored into insurance rates.
Labor Costs: Miami’s labor market can be expensive, especially after storms when demand for repairs is high. This affects the overall cost of claims and, in turn, insurance premiums.
These factors combined make Miami home insurance rates some of the highest in the country. Understanding these reasons can help homeowners make informed decisions about their insurance needs and explore ways to reduce costs.
How to Save on Home Insurance in Miami
Home insurance in Miami can be pricey, but there are ways to lower your costs. Let’s explore some effective strategies.
Wind Mitigation Measures
Wind mitigation can significantly reduce your premiums. Wind mitigation involves strengthening your home to withstand strong winds from hurricanes. Here are some common measures:
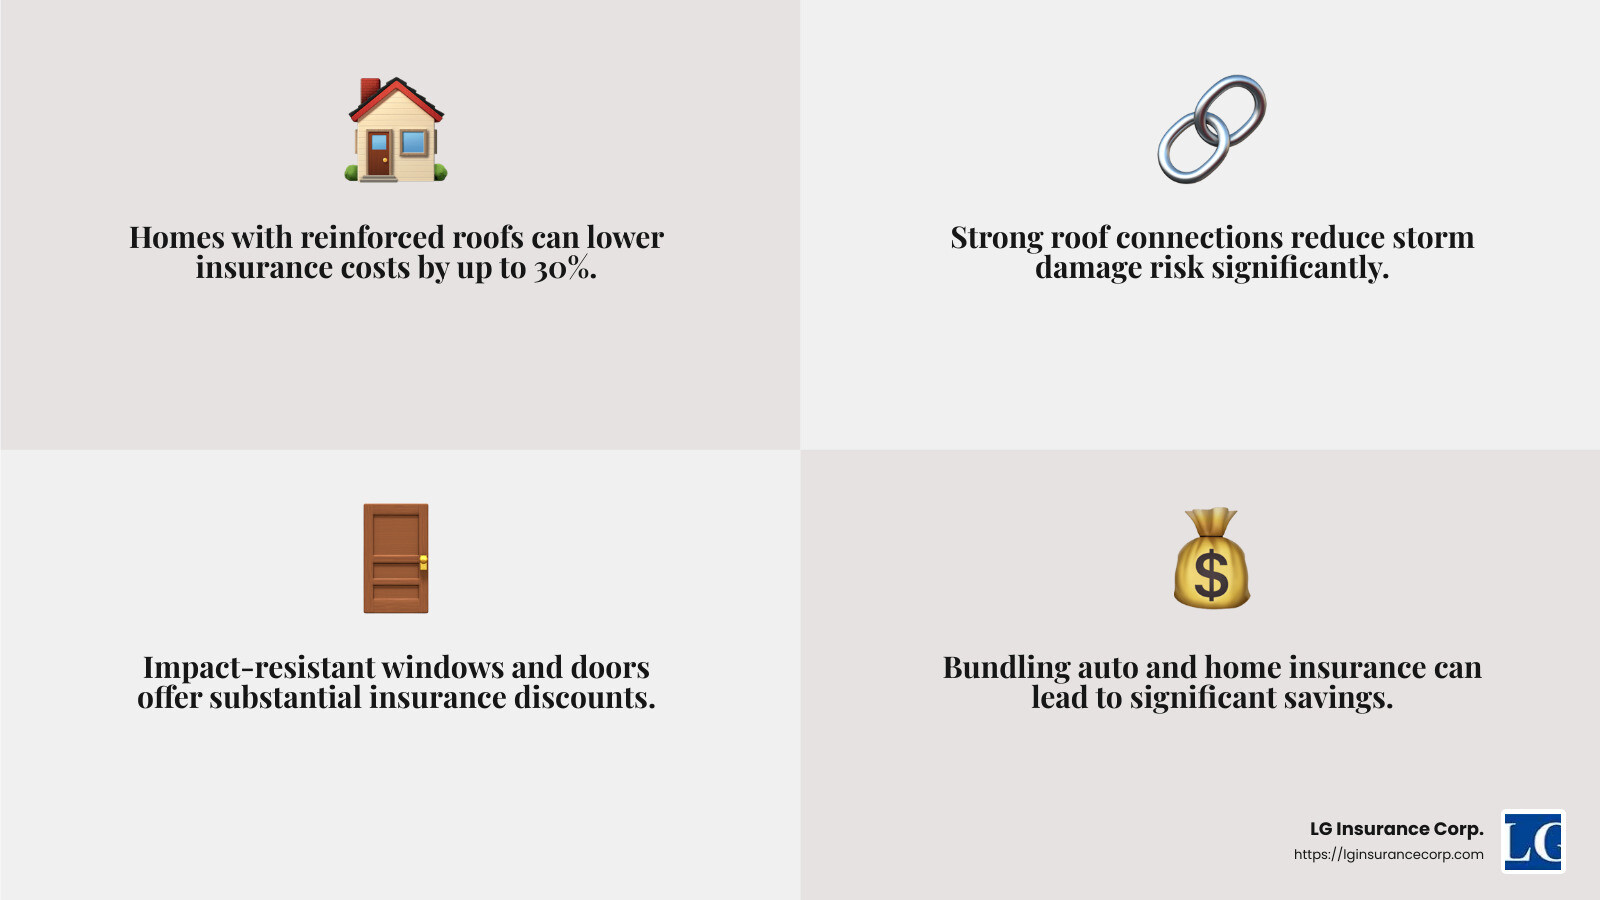
Roof Construction and Connections: Reinforcing your roof with stronger materials and ensuring it’s securely attached can make a big difference. Homes with solid roof connections are less likely to suffer damage during storms.
Impact-Resistant Doors and Windows: Installing doors and windows that can withstand high winds and flying debris is crucial. These features not only protect your home but can also lead to substantial insurance discounts.
Bundling Policies
Another way to save is by bundling your insurance policies. Many providers offer discounts if you purchase both auto and home insurance from them. Here’s why bundling is beneficial:
Provider Discounts: Insurance companies often offer discounts when you have multiple policies with them. This can lead to significant savings.
Convenience: Managing both policies with one provider simplifies your insurance dealings and can streamline payments and claims.
Other Strategies to Save
Higher Deductibles: Choosing a higher deductible can lower your monthly premium. Just ensure you can afford the deductible if you need to make a claim.
Discounts: Ask your provider about available discounts. You might qualify for savings based on your home’s safety features or your personal circumstances.
Technology for Risk Assessment: Some insurers use technology to assess risks more accurately. By allowing them to evaluate your home, you might qualify for lower rates.
By implementing these strategies, you can potentially lower your Miami home insurance rates and keep more money in your pocket.
Additional Coverage Options for Miami Homeowners
When it comes to protecting your home in Miami, standard homeowners insurance might not cover all the risks you face. Here are some additional coverage options to consider:
Flood Insurance
Flooding is a significant risk in Miami due to its low-lying geography and susceptibility to hurricanes. Homeowners insurance typically does not cover flood damage, so purchasing a separate flood insurance policy is crucial, especially if you live in a high-risk zone.
High-Risk Zones: Miami has several areas designated as high-risk flood zones by FEMA. If your home is in one of these areas, your mortgage lender will likely require you to have flood insurance.
FEMA Maps: These maps are essential tools for determining flood risk. They outline which areas are more prone to flooding, helping homeowners understand their risk level and insurance needs.
Mortgage Lender Requirements: If you have a mortgage and live in a high-risk flood zone, your lender will usually mandate flood insurance. This requirement ensures that both you and the lender are protected financially in the event of flood damage.
Hurricane Deductibles
Miami’s location makes it highly vulnerable to hurricanes. Hurricane deductibles are a unique feature of Florida homeowners insurance policies, designed to address this risk.
Percentage-Based Deductibles: Unlike standard deductibles, hurricane deductibles are often based on a percentage of your home’s insured value. This percentage can range from 1% to 10%.
Once Per Season: The good news is that hurricane deductibles apply only once per hurricane season. So if multiple storms hit, you only pay the deductible for the first one.
Coverage Limits: It’s important to understand your policy’s coverage limits and how the hurricane deductible affects them. Be sure to select a deductible you can afford, even in the worst-case scenario.
By considering these additional coverage options, Miami homeowners can better protect their properties from the unique risks posed by the area’s climate and geography.
Frequently Asked Questions about Miami Home Insurance Rates
How much is the average homeowners insurance in Miami?
In Miami, the average cost of homeowners insurance is around $3,572 per year, which breaks down to about $298 a month. This rate typically covers a home with $300,000 in dwelling coverage. Rates can vary significantly based on factors like the age of your home, its location, and your credit history.
Why is home insurance so expensive in South Florida?
Home insurance in South Florida, including Miami, tends to be expensive due to several risk factors. The region is highly prone to hurricanes and floods, which can cause extensive damage to properties. Sinkholes also pose a risk, although they are less common in Miami compared to other parts of Florida. The proximity to the coast increases the risk of storm surge flooding, making coastal homes more vulnerable. These risks necessitate higher insurance premiums to cover the potential for large claims.
Who has the cheapest homeowners insurance in Florida?
Finding affordable homeowners insurance in Florida can be challenging due to the high risk of natural disasters. However, there are still affordable options available. On average, the cheapest homeowners insurance rates in Florida are around $2,443 per year. While specific companies offering these rates were not detailed, it’s important to shop around and compare quotes from different insurers to find the best deal for your needs.
For more personalized advice and to explore your options, consider reaching out to an insurance expert who can help tailor a policy that meets your specific requirements and budget.
Conclusion
Navigating the complexities of Miami home insurance rates can be daunting. With the city’s unique risks, such as hurricanes, floods, and high rebuilding costs, securing the right coverage is crucial.
At LG Insurance Corp., we understand these challenges. As a family-owned agency rooted in Miami, we offer custom policies custom to meet your specific needs. Our goal is to provide you with an affordable price without compromising on the protection your home deserves.
We pride ourselves on delivering expert advice and support to our community. Our team is dedicated to helping you understand your options and find the best solutions for your home insurance needs. By partnering with us, you’re not just getting an insurance policy—you’re gaining a trusted ally committed to safeguarding your most valuable asset.
For more information on how we can assist you with your home insurance needs, visit our Home Insurance page. Let us help you protect your home and provide peace of mind for you and your family.