Is theft covered under commercial property insurance? Yes, but there’s more to the story.
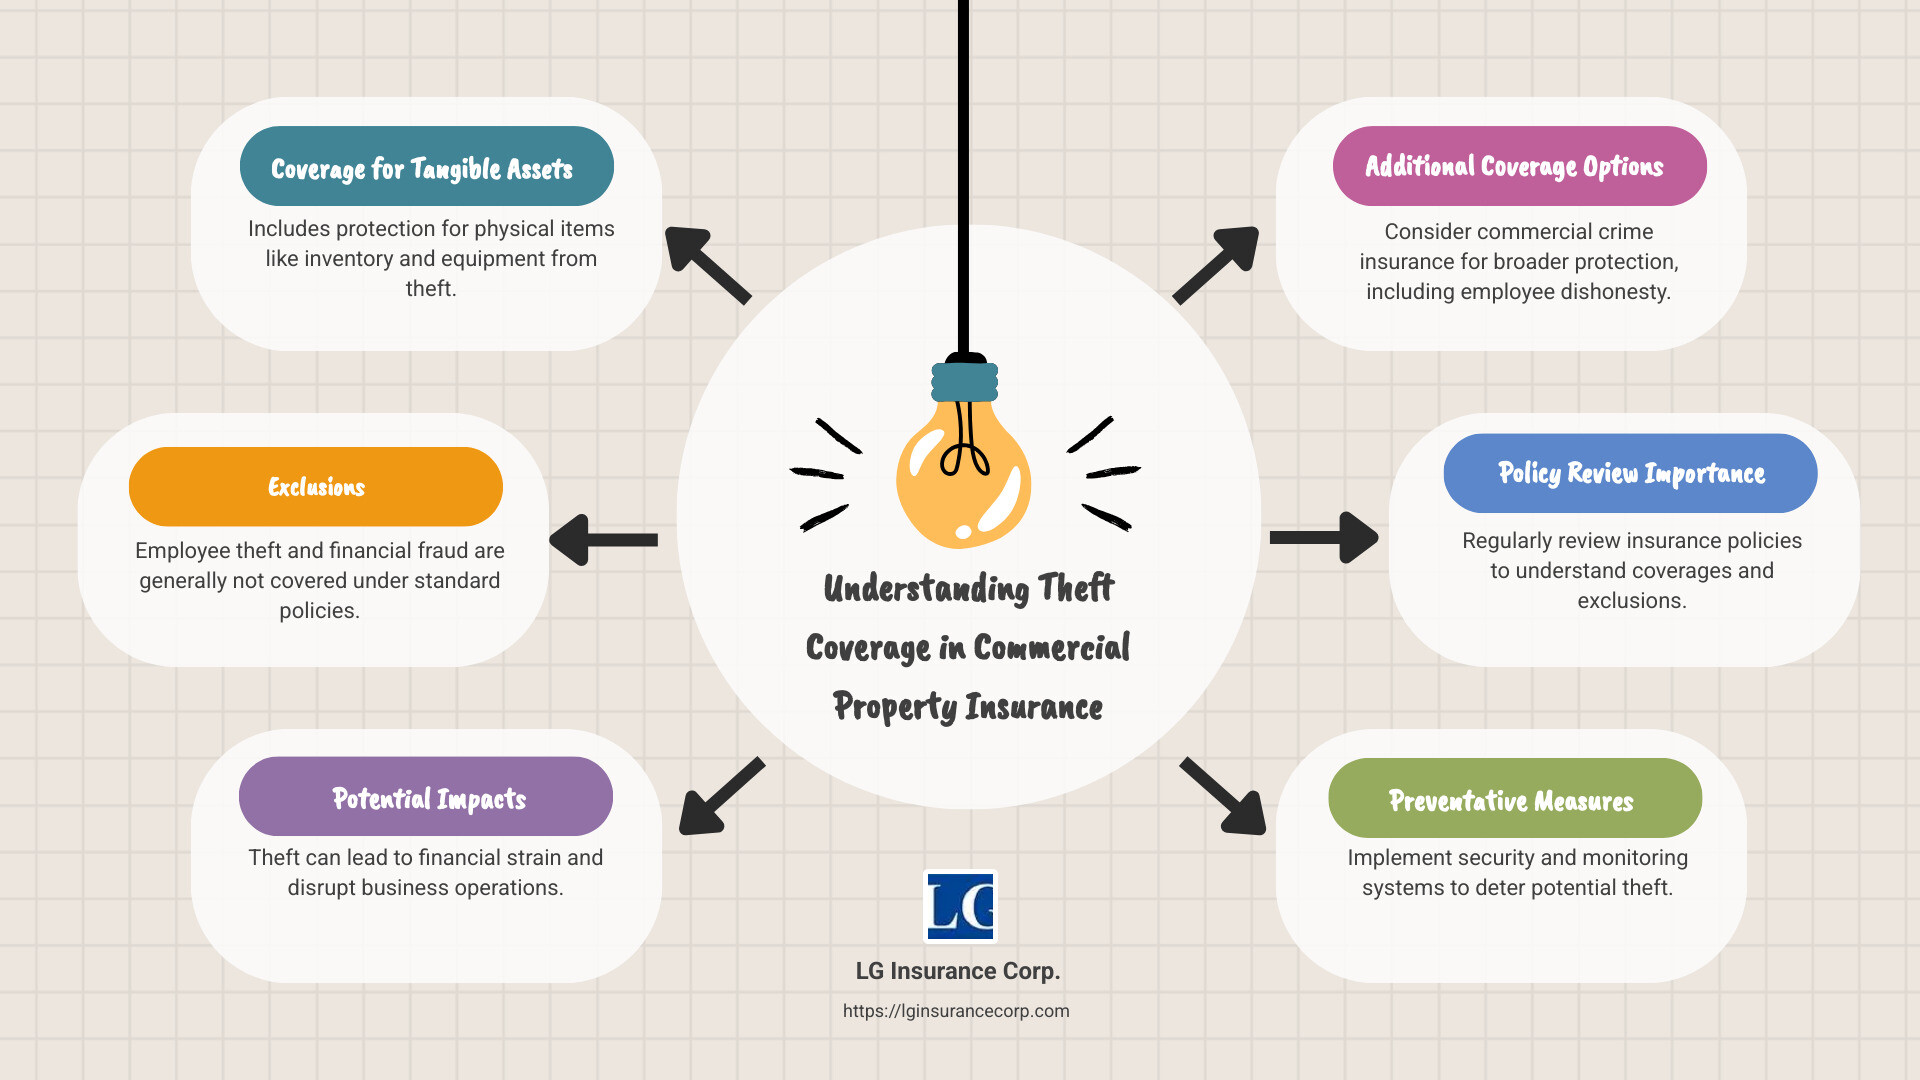
Commercial property insurance typically covers theft of business property like office equipment and inventory. However, it doesn’t protect against employee theft or financial fraud. Understanding what is included—and what isn’t—can shield your business from unexpected losses.
Key Points to Know:
– Covers tangible assets like inventory and equipment.
– Does not cover employee theft or financial fraud.
– Consider additional coverage like commercial crime insurance for broader protection.
Why It’s Important:
Theft can wreak havoc on your business finances and operations. Repairing the damage can be costly, and dealing with claims can be frustrating. Thus, comprehending your insurance policy is crucial to safeguard your business.
As the owner of LG Insurance Agency in Miami, I’ve spent over 20 years helping businesses answer the complex question: is theft covered under commercial property insurance? With my expertise, I’ll guide you through understanding your policy to ensure your business is well-protected.
Is theft covered under commercial property insurance terms to learn:
– is collapse covered by commercial property insurance
– what can be covered under citizens commercial property insurance
– commercial property insurance cost
What is Commercial Property Insurance?
Commercial property insurance is a vital part of protecting your business. It’s designed to cover physical assets from unexpected events like fire, theft, and certain natural disasters. Let’s break it down to see what this type of insurance typically covers and what you need to know.
Coverage Types
At its core, commercial property insurance protects the physical assets of your business. This includes:
- Buildings: Whether you own or lease, the structure itself is covered.
- Equipment: Machinery and tools essential for your business operations.
- Inventory: Products you sell or materials you use.
- Furniture and Fixtures: Everything from desks and chairs to lighting fixtures.
- Electronics: Computers, printers, and other tech devices.

Policy Details
Understanding the details of your policy is crucial. Here are a few key points:
- Named Perils vs. All-Risk: Policies may cover specific perils like fire and theft (named perils) or offer broader protection (all-risk).
- Replacement Cost vs. Actual Cash Value: Replacement cost covers the expense to replace items without depreciation. Actual cash value considers depreciation, which might result in lower payouts.
- Deductibles: The amount you pay out of pocket before your insurance kicks in. Higher deductibles can lower your premiums but increase your initial costs when filing a claim.
Why It Matters
It’s important to know what exactly your policy covers to avoid surprises. For instance, while theft of business property is generally covered, employee theft is not. This limitation highlights the importance of reviewing and understanding your policy thoroughly.
In Miami and South Florida, where LG Insurance Corp. operates, businesses must also consider local risks like hurricanes. Weather-related factors can influence your policy’s cost and coverage.
Takeaway: Commercial property insurance is essential for safeguarding your business assets. However, knowing the specifics of your coverage can save you from potential pitfalls down the road.
Next, we’ll dive into the specifics of theft coverage and explore the common exclusions and limitations you should be aware of.
Is Theft Covered Under Commercial Property Insurance?
When it comes to commercial property insurance, understanding what is and isn’t covered can be a bit tricky. Let’s get into the specifics of theft coverage, including theft scenarios, policy limitations, and exclusions.
Theft Scenarios
Commercial property insurance generally covers theft of physical assets like:
- Inventory and Equipment: If someone breaks in and steals your inventory or vital equipment, your policy should help cover the loss.
- Electronics: Theft of computers and other tech devices from your business premises is typically included.
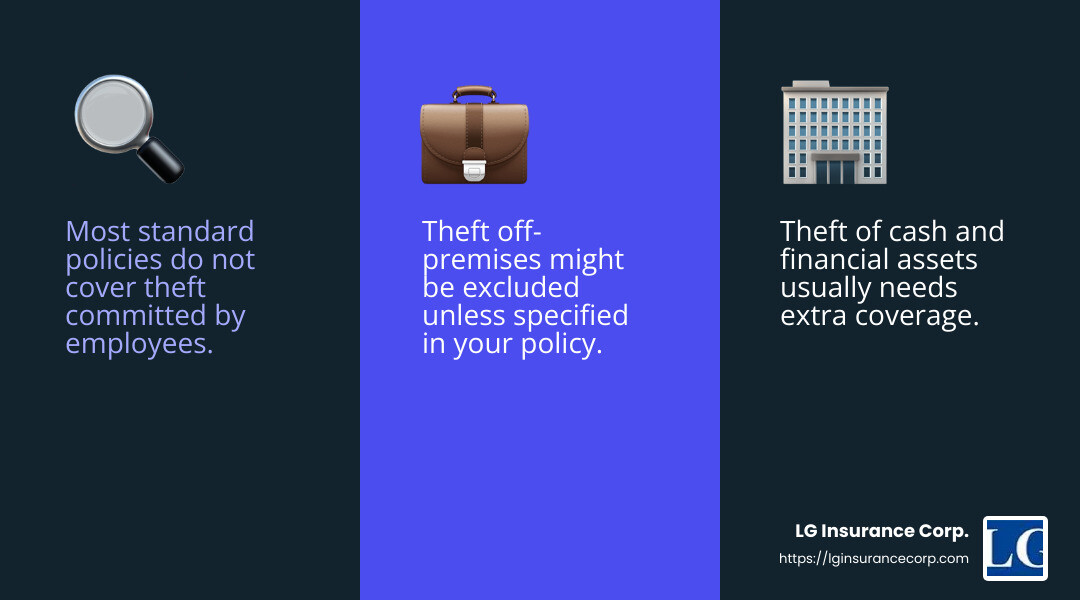
However, it’s crucial to know the exact terms of your policy. For example, theft that occurs off-premises, like a stolen company laptop from a traveling employee, might not be covered unless specified in the policy.
Policy Limitations
While commercial property insurance provides a safety net for many theft scenarios, there are some limitations to keep in mind:
- Employee Theft: Most standard policies do not cover theft committed by employees. For this, you would need a separate commercial crime insurance policy.
- Cash and Financial Assets: Theft of cash, accounts receivable, or other financial assets usually requires additional coverage, as these are often excluded from basic property policies.
Exclusions
Understanding exclusions is key to knowing what your policy won’t cover:
- Wear and Tear: Damage from normal wear and tear is not covered.
- Third-Party Damage: If a third party causes damage that leads to theft, this might not be covered under your commercial property policy.
- Acts of War or Terrorism: These are often explicitly excluded, requiring separate coverage.
In Miami and South Florida, where LG Insurance Corp. operates, businesses should also be aware of exclusions related to weather-related damages, which are common in this region.
Takeaway: While commercial property insurance can cover many theft scenarios, understand the limitations and exclusions. This ensures that your business is adequately protected and helps you avoid unexpected costs.
Next, we’ll explore common exclusions and limitations in more detail to help you steer the complexities of commercial property insurance.
Common Exclusions and Limitations
When it comes to commercial property insurance, understand what might not be covered. Knowing these common exclusions and limitations can save your business from unexpected surprises.
Wear and Tear
First up, wear and tear. Regular deterioration of your property or equipment over time is not covered. This means if your business’s roof starts leaking due to age, your insurance won’t pay for repairs. Regular maintenance is key to preventing these types of issues.
Employee Theft
Another crucial point is employee theft. Standard commercial property insurance policies typically do not cover theft committed by employees. For this, businesses need to look into commercial crime insurance. This specialized policy can cover losses from employee dishonesty, such as stealing cash or inventory.

Third-Party Damage
Third-party damage is another consideration. If someone outside your business (like a contractor) causes damage that results in theft, your commercial property insurance might not cover it. In such cases, the responsible party’s insurance should be liable, but it’s wise to verify this in your policy.
Acts of War or Terrorism
Lastly, acts of war or terrorism are usually excluded. These events require separate coverage, which is crucial in areas where such risks are higher.
Understanding these exclusions and limitations helps ensure that your business is prepared for various scenarios. By knowing what’s not covered, you can take additional steps to protect your assets, ensuring peace of mind for your business operations.
In the next section, we’ll dig into how you can improve your theft coverage to better safeguard your business.
Enhancing Your Theft Coverage
Understanding what your commercial property insurance doesn’t cover is just the first step. The next step is to improve your theft coverage to ensure your business is well-protected.
Endorsements
One way to strengthen your coverage is through endorsements. These are add-ons to your existing policy that provide extra protection. For instance, you might add an endorsement to cover specific theft scenarios not included in your standard policy. Talk to your insurance agent about which endorsements make sense for your business, especially if you handle valuable inventory or sensitive information.
Crime Insurance
Another option is to invest in commercial crime insurance. This type of insurance is custom to cover losses from various business crimes, such as theft, fraud, and forgery. According to research, businesses lose about 5% of their revenue to fraud each year. With crime insurance, you can protect your cash, assets, and even your reputation from these losses. It’s especially important for businesses dealing in cash or online payments, as they are more susceptible to theft.
Preventative Measures
Insurance is crucial, but prevention is even better. Implementing preventative measures can significantly reduce the risk of theft. Here are some tips:
- Install security cameras: Monitor entry points and high-traffic areas.
- Conduct background checks: Ensure your employees are trustworthy.
- Train your staff: Educate them on safe procedures and what to do in case of a robbery.
- Secure your premises: Use panic locks and keep doors locked from the outside.
These steps not only help protect your business but can also lead to lower insurance premiums, as insurers often offer discounts for businesses with strong security measures in place.
By considering endorsements, investing in crime insurance, and taking preventative measures, you can create a comprehensive theft protection plan. This approach ensures your business is not only covered but also prepared to handle potential theft scenarios effectively.
In the next section, we’ll address some frequently asked questions about theft coverage to further clarify how you can safeguard your business.
Frequently Asked Questions about Theft Coverage
Which is not covered under commercial property insurance?
When it comes to commercial property insurance, it’s important to know what it doesn’t cover. Generally, this insurance won’t cover wear and tear or maintenance issues. These are considered part of regular upkeep and not sudden, unforeseen events. For example, if your building’s roof leaks due to age, that’s maintenance, not a covered loss.
Employee theft is another common exclusion. Standard commercial property insurance typically doesn’t cover theft by employees. For this kind of protection, you’ll need crime insurance or a specific policy that includes employee dishonesty coverage.
Does commercial property insurance cover employee theft?
No, standard commercial property insurance usually does not cover employee theft. To protect against losses from dishonest employees, businesses should consider commercial crime insurance. This type of insurance covers a range of crimes, including employee theft, forgery, and fraud. Given that employee theft accounts for significant losses each year, having this coverage is crucial for many businesses.
What should businesses do to prevent theft?
Preventing theft is as important as having the right insurance. Here are some security measures and proactive strategies businesses can adopt:
- Install a security system: Cameras and alarms can deter thieves and provide evidence if a theft occurs.
- Conduct regular audits: Keep track of inventory and finances to spot discrepancies early.
- Background checks: Screen potential employees to ensure they have a trustworthy history.
- Educate employees: Train them on security protocols and what to do during a theft or burglary.
- Secure entry points: Use high-quality locks and limit access to sensitive areas.
By taking these steps, businesses can reduce their risk of theft and potentially lower their insurance premiums. These measures show insurers that you’re serious about security, which can be beneficial when negotiating policy terms.
In our concluding section, we’ll explore how LG Insurance Corp. can help you craft a comprehensive insurance plan that meets your business’s specific needs.
Conclusion
At LG Insurance Corp., we understand that protecting your business from theft and other risks is crucial. Our goal is to provide comprehensive solutions and expert advice to ensure your business is safeguarded against unforeseen events.
We offer a variety of insurance options custom to meet the unique needs of businesses in Miami, FL, and throughout South Florida. Our experienced team is here to help you steer the complexities of commercial property insurance and identify any gaps in coverage that could leave your business vulnerable.
Why Choose LG Insurance Corp.?
- Customer-Centric Service: We prioritize your needs and focus on delivering personalized service.
- Expert Advice: Our knowledgeable agents will guide you through the process, helping you understand your options and make informed decisions.
- Community Support: As a family-owned agency, we are committed to supporting our local community and helping businesses thrive.
Whether you’re looking to improve your theft coverage with endorsements or need guidance on preventative measures, we’re here to assist. Our team will work with you to design an insurance package that not only protects your physical assets but also aligns with your business goals.
Don’t leave your business’s security to chance. Visit our business property insurance page to learn more about how we can help you protect your business with the right coverage. Let LG Insurance Corp. be your partner in safeguarding your business’s future.