Is collapse covered by commercial property insurance? This is a critical question for property owners, particularly following incidents like the tragic collapse of Surfside, Florida’s Champlain Towers South. Understanding your commercial property insurance coverage is vital because most policies do not automatically cover collapses. Instead, coverage depends on specific causes of the collapse and whether it meets certain criteria.
- Covered Causes: Sudden, unexpected events like fire, certain natural disasters, or hidden structural issues might be covered.
- Exclusions to Watch: Gradual wear and tear, neglect, and known structural problems generally aren’t covered.
- Important Considerations: The type of policy and specific clauses play a major role in whether a claim for collapse would be approved.
I’m Leonard Garcia, a dedicated expert in navigating complex insurance scenarios. With over 20 years in the industry, particularly focused on regions like South Florida, I’ve helped countless clients address concerns just like “is collapse covered by commercial property insurance.” My experience enables me to provide you with valuable insights and protect what’s most important to you.
For those wanting a quick glance and easy reference:

Must-know is collapse covered by commercial property insurance terms:
– best commercial property insurance companies
– what can be covered under citizens commercial property insurance
– commercial property insurance cost
Understanding Building Collapse Coverage
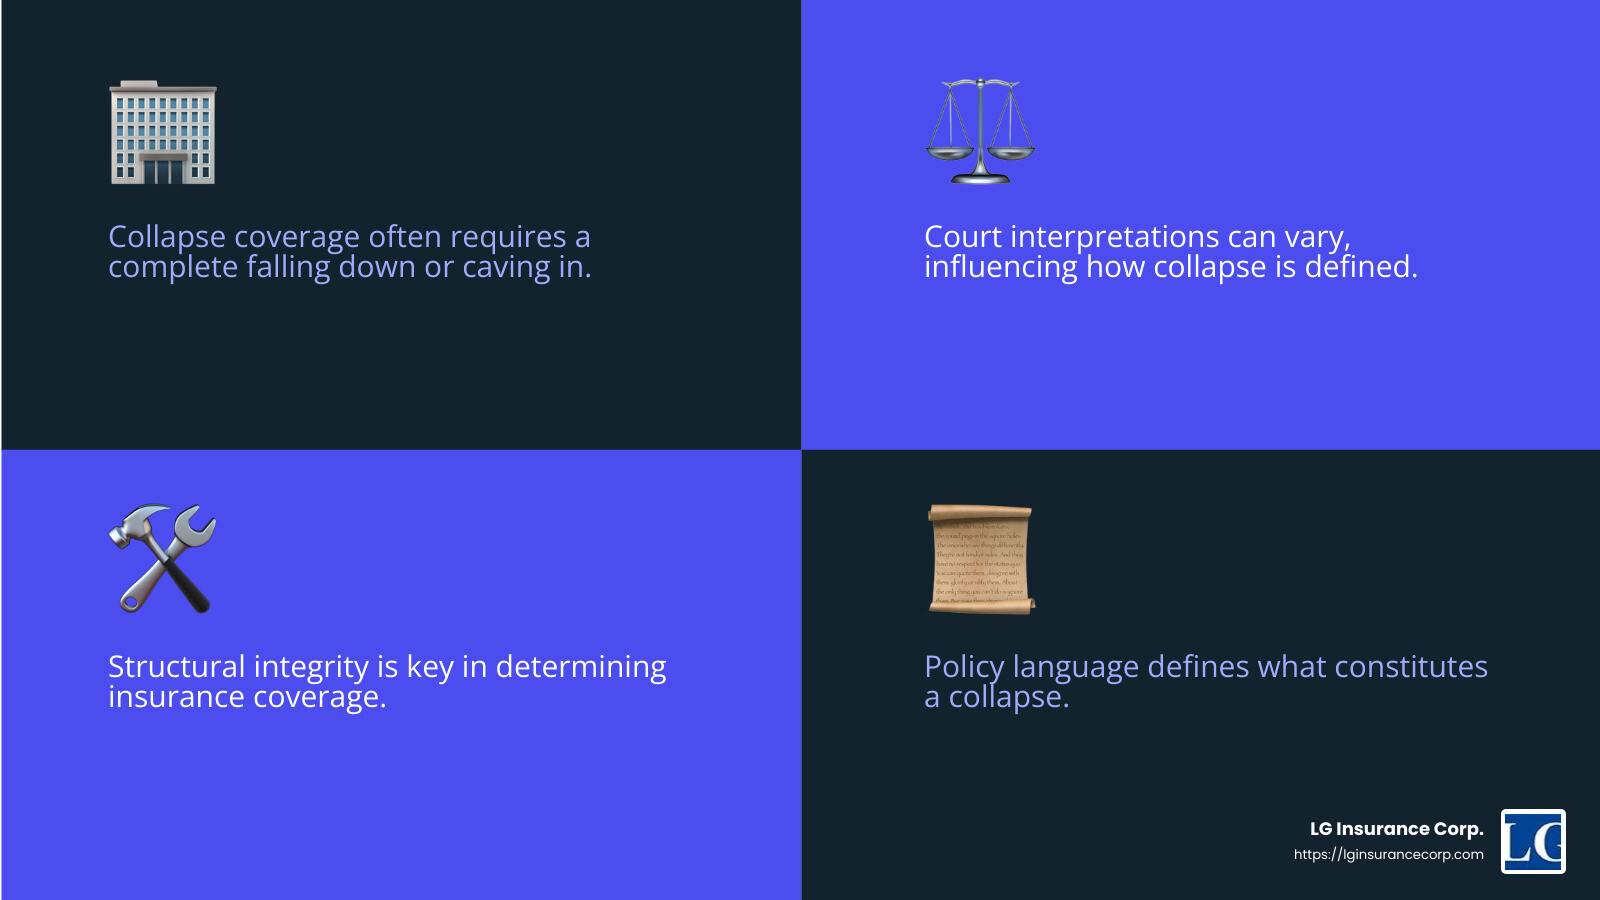
When discussing building collapse coverage in commercial property insurance, first understand what “collapse” means. In insurance terms, a collapse typically refers to the sudden falling down or caving in of a building or part of a building, resulting in it being unusable. This definition is crucial because not every structural issue constitutes a collapse.
Structural Integrity and Insurance
Insurance policies often focus on the structural integrity of a building when determining coverage. Structural integrity means the building is constructed and maintained to withstand its intended use and environmental factors. If a building’s structural integrity is compromised due to poor maintenance or known defects, insurance coverage may be limited or denied.
Insurance Policy Language
The language used in insurance policies can be complex and nuanced. Policies often include specific terms and conditions that define what is covered under a collapse scenario. For instance, some policies might cover collapses caused by hidden decay or certain natural disasters, but exclude those caused by neglect or gradual deterioration.
It’s important to carefully read and understand your insurance policy’s language. Look for sections that describe what constitutes a collapse and any exclusions that might apply. This will help you know what to expect if you ever need to file a claim.
Case Study: Court Interpretations
Court decisions have influenced how collapse coverage is interpreted. For example, some courts have taken a conservative view, requiring a complete falling down or caving in for a collapse to be recognized. Others have adopted a more liberal approach, considering substantial impairment of structural integrity as a collapse, even without the building falling down completely.
Understanding these interpretations can be critical, especially in areas prone to natural disasters, like South Florida. Knowing how different courts might interpret your policy can affect your coverage.
Key Takeaways
- Collapse Definition: Understand what your policy considers a collapse.
- Structural Integrity: Regular maintenance and addressing known issues are crucial.
- Policy Language: Read and understand your policy’s specific terms and conditions.
By grasping these concepts, commercial property owners can better steer their insurance policies and ensure they have the coverage they need in the event of a building collapse.
Is Collapse Covered by Commercial Property Insurance?
When it comes to commercial property insurance, understanding whether a collapse is covered can be complex. Perils covered, exclusions, and policy stipulations all play a role in determining coverage.
Perils Covered
Most commercial property insurance policies cover specific perils that could lead to a building collapse. These might include:
- Fire
- Windstorm
- Hail
- Explosion
- Weight of snow, ice, or rain
These perils are generally recognized as sudden and accidental events, which are often covered under standard policies. However, coverage can vary, so it’s crucial to review your policy details.
Exclusions
Policies often have exclusions that can limit coverage for building collapses. Common exclusions include:
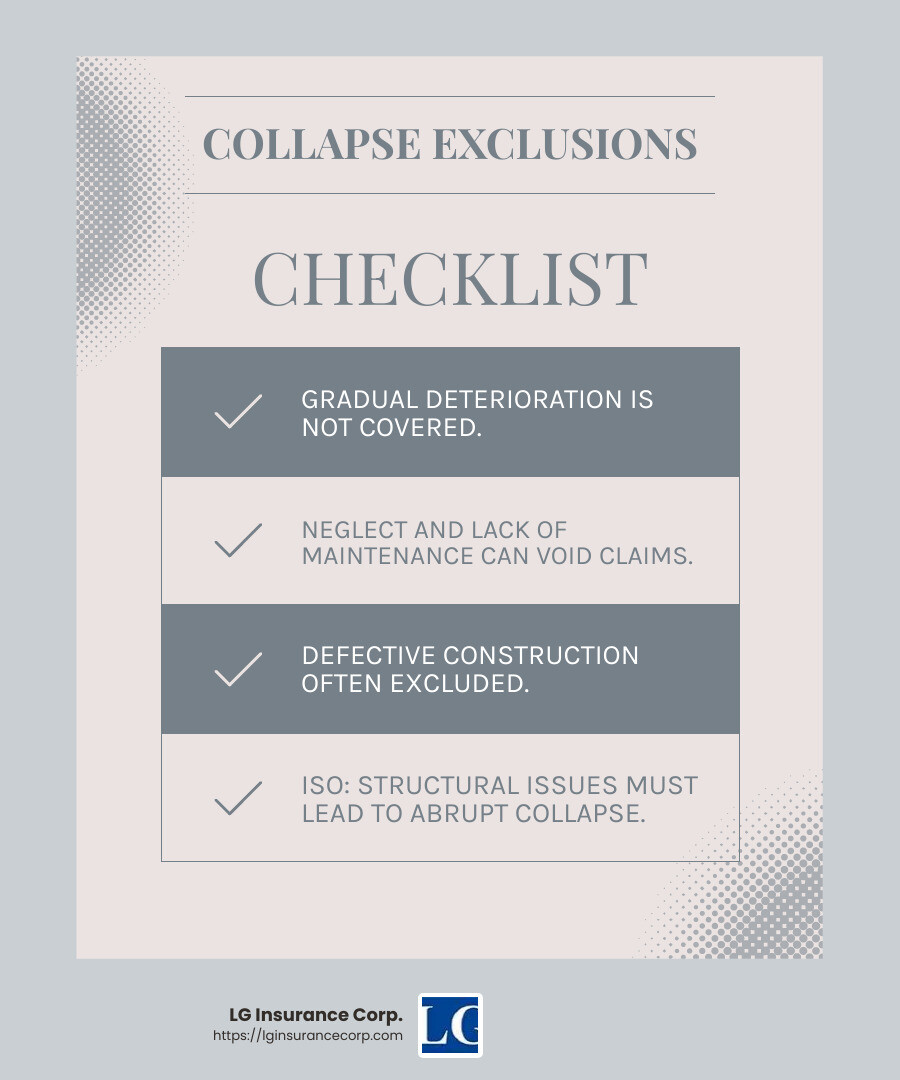
- Gradual deterioration: Damage due to wear and tear over time is typically not covered.
- Neglect: If a collapse results from a lack of maintenance or known structural issues, the claim may be denied.
- Defective materials or construction: Issues stemming from faulty construction may not be covered unless they lead to a sudden collapse.
The Insurance Services Office (ISO) notes that coverage is usually excluded for collapses due to structural issues like cracking or bulging unless it results in an abrupt cave-in.
Policy Stipulations
Insurance policies often have specific stipulations regarding collapse coverage. For instance, some policies may require that the collapse be sudden and without warning. Others might stipulate that the building is uninhabitable as a result of the collapse.
A notable example is the Champlain Towers South collapse in Surfside, Florida, which raised questions about insurance coverage. The key factor was whether the collapse was due to a covered peril or excluded cause, such as known structural deficiencies.
Navigating Your Policy
To determine if your commercial property insurance covers a collapse, closely examine your policy. Look for:
- Covered perils: Identify what events are included in your coverage.
- Exclusions: Understand what might limit or deny your claim.
- Stipulations: Pay attention to conditions that must be met for a collapse to be covered.
By understanding these elements, you can better steer your commercial property insurance policy. This knowledge is especially vital in areas like South Florida, where natural disasters pose a significant risk.
Factors Affecting Collapse Coverage
When discussing is collapse covered by commercial property insurance, consider several key factors. These include maintenance, structural damage, and construction flaws. Each of these can significantly impact whether an insurance claim for a building collapse will be approved or denied.
Maintenance
Maintenance plays a crucial role in determining collapse coverage. Regular upkeep is vital. Insurance policies often exclude coverage if a collapse results from neglect or lack of maintenance. For example, if a roof collapses due to accumulated debris or clogged gutters, the claim might be denied. Regular inspections and repairs can help prevent such issues and demonstrate a proactive approach, which can be beneficial if a claim is filed.
Structural Damage
Structural damage is another factor that can affect coverage. Insurance typically does not cover collapses resulting from pre-existing structural issues, like cracks or bulges, unless they lead to a sudden and unforeseen collapse. The Champlain Towers South collapse highlighted the importance of identifying and addressing structural damage early. If structural issues are known and not addressed, claims are likely to be denied.
Construction Flaws
Construction flaws can also impact insurance coverage. If a building collapses due to defective materials or poor construction practices, the insurance might not cover the damage. However, some policies offer additional coverage for specific construction-related issues, especially if they result in an abrupt collapse. For instance, if hidden decay or defective materials lead to a sudden collapse, coverage may apply, provided these were not apparent before the collapse.
Understanding these factors is crucial for property owners. Regular maintenance, addressing structural issues promptly, and ensuring quality construction can help in navigating the complexities of commercial property insurance policies. By being proactive, you can better protect your investment and ensure that your insurance coverage is effective when needed.
Exceptions and Additional Coverage Options
When considering the question, is collapse covered by commercial property insurance, it’s important to know that there are exceptions and additional coverage options that might apply. These can make a significant difference in whether a collapse is covered or not.
Specified Causes
Insurance policies often include specific causes of loss that are covered. These might include events like the weight of rain on a roof or the weight of people and property. For example, if a roof collapses due to heavy snow, and snow is a specified cause of loss in your policy, the damage might be covered. However, if the collapse is due to gradual wear and tear, it likely won’t be.
Additional Coverage
Some policies offer additional coverage for certain situations. This might include coverage for hidden decay or insect damage that is not visible before a collapse. These additional coverages can be crucial, especially if the collapse is due to issues that were not apparent. Discussing these options with your insurance provider can help ensure you have the necessary coverage in place.
Hidden Decay
Hidden decay is a critical factor in collapse coverage. If decay is hidden from view and not known to the insured, some policies might cover the resulting collapse. However, if the decay was visible or known, coverage might be denied. Regular inspections can help identify decay early and possibly prevent a collapse from occurring.
Understanding these exceptions and coverage options is key to effectively managing your commercial property insurance. By knowing what your policy covers and addressing any potential issues proactively, you can better protect your investment and ensure peace of mind.
Frequently Asked Questions about Collapse Coverage
What constitutes a collapse under insurance policies?
In insurance, a collapse isn’t just any structural issue. It specifically refers to an abrupt falling down or caving in of a building or a part of a building. This means the structure can no longer be used for its intended purpose.
However, if a building is merely in danger of collapsing or shows signs like cracking or sagging, it typically doesn’t qualify as a collapse under most insurance policies. The structure must actually fall or cave in to meet the definition of a collapse.
How has collapse coverage evolved over time?
Collapse coverage has seen significant changes over the years, largely due to court decisions and evolving policy language. Initially, insurance policies had a narrow view of what constituted a collapse. However, court rulings have sometimes expanded these definitions, prompting insurers to clarify and tighten their policy language.
For instance, cases like Guyther have emphasized the need for suddenness in a collapse, leading insurers to explicitly require that a collapse must be abrupt. This has aimed to prevent broad interpretations that could result in unintended coverage.
What are common exclusions in collapse coverage?
Understanding what isn’t covered is just as important as knowing what is. Common exclusions in collapse coverage often relate to maintenance and gradual deterioration. Here’s a quick rundown:
Maintenance Issues: If a collapse results from neglect or lack of proper maintenance, it likely won’t be covered. This includes issues like gradual wear and tear or decay that was visible but ignored.
Structural Impairment: Buildings with known structural impairments, like cracks or bulges, might not be covered if they collapse. The policy often requires the collapse to be sudden and unforeseen.
Construction Flaws: Faulty construction or repairs without proper permits can also lead to denied claims. Insurers expect buildings to be constructed or repaired to code.
By understanding these exclusions, property owners can better manage their risks and ensure they maintain their structures to avoid potential coverage issues.
Conclusion
Navigating the complexities of commercial property insurance, especially when it comes to understanding if collapse is covered, can be challenging. At LG Insurance Corp., we are committed to providing clear, expert advice custom to your needs. As a family-owned agency in Miami, FL, we focus on customer-centric service, ensuring you have the right coverage for your property.
Our team understands that insurance policy language can be confusing, and we strive to explain it for you. We are here to guide you through policy stipulations, exclusions, and the specifics of collapse coverage, so you can make informed decisions about your insurance needs.
By partnering with us, you gain access to our extensive knowledge of the industry and our dedication to community support. We work closely with you to assess your unique risks and develop comprehensive insurance solutions that protect your business assets.
For more information on how we can help secure your commercial property, visit our Business Property Insurance page. Let us help you safeguard your investment with confidence.