Hurricane damage insurance claims Miami-Dade are a critical concern for residents facing the aftermath of powerful storms. Filing these claims quickly and correctly can mean the difference between getting the compensation you need and struggling with unforeseen costs. Here’s a straightforward guide to get you started:
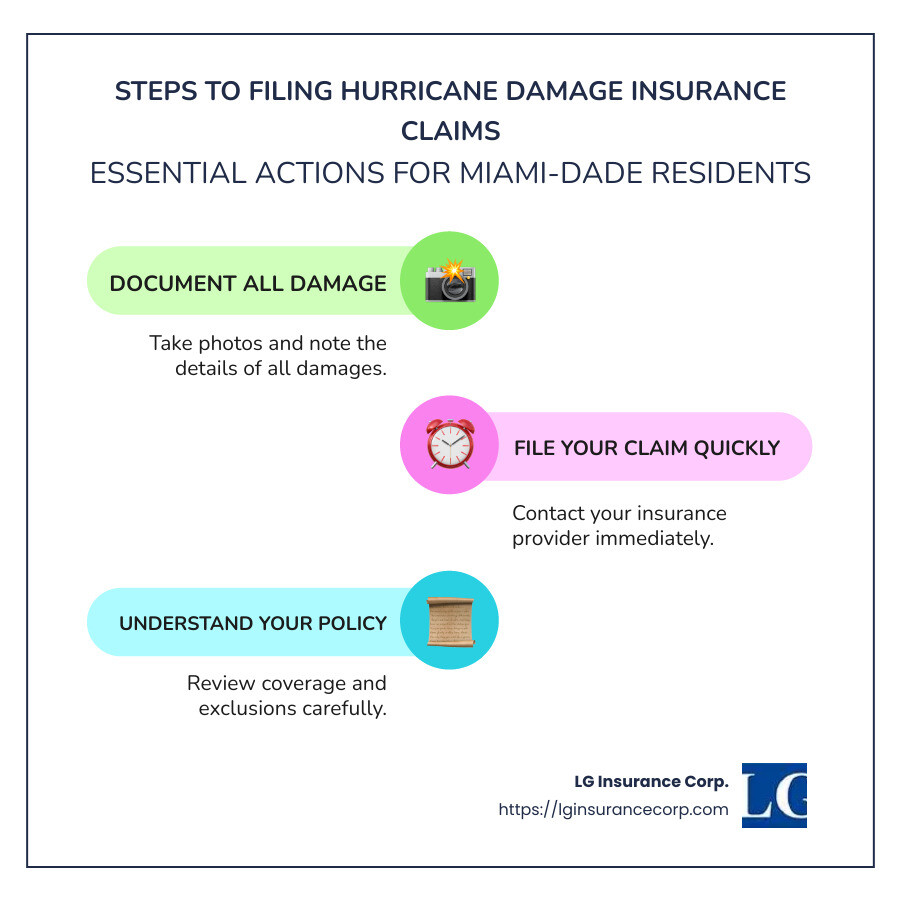
- Document All Damage: Take photos and write down the details of the damage.
- File Your Claim Quickly: Contact your insurance provider as soon as possible.
- Understand Your Policy: Know what your hurricane damage insurance covers and any exclusions.
- Seek Professional Help: Consider consulting with an insurance expert or lawyer.
In Miami-Dade, hurricanes are a regular threat. The area is vulnerable to high winds, storm surges, and heavy rains. These can cause severe damage to homes and businesses. Navigating insurance claims efficiently is crucial for recovery.
As the owner of LG Insurance Agency, I have over two decades of experience with hurricane damage insurance claims Miami-Dade. My team and I focus on offering personalized, comprehensive insurance solutions to meet the unique needs of our community.
Hurricane damage insurance claims miami dade glossary:
– Miami home insurance claims
– insurance adjusters miami
– business insurance claims miami fl
Understanding Hurricane Damage Insurance Claims
Hurricanes are a fact of life in Miami-Dade. They bring strong winds, storm surges, and flooding, causing significant damage to properties. Understanding how these elements interact with your insurance policy is crucial.
Wind-Related Damages
Wind can be incredibly destructive. Gale force winds can break tree limbs, while hurricane force winds can rip roofs off homes. Most homeowner policies cover wind damage. However, check your policy’s details. Some policies may have specific exclusions or require separate windstorm coverage.

Storm Surge and Flood Insurance
Storm surges occur when hurricane winds push seawater onto land. This can lead to extensive flooding. Unfortunately, standard homeowner insurance policies usually don’t cover flood damage. For this, you’ll need a separate flood insurance policy. It’s critical to understand that insurers might classify storm surge damage as flood damage, not covered under standard policies.
The Importance of Flood Insurance
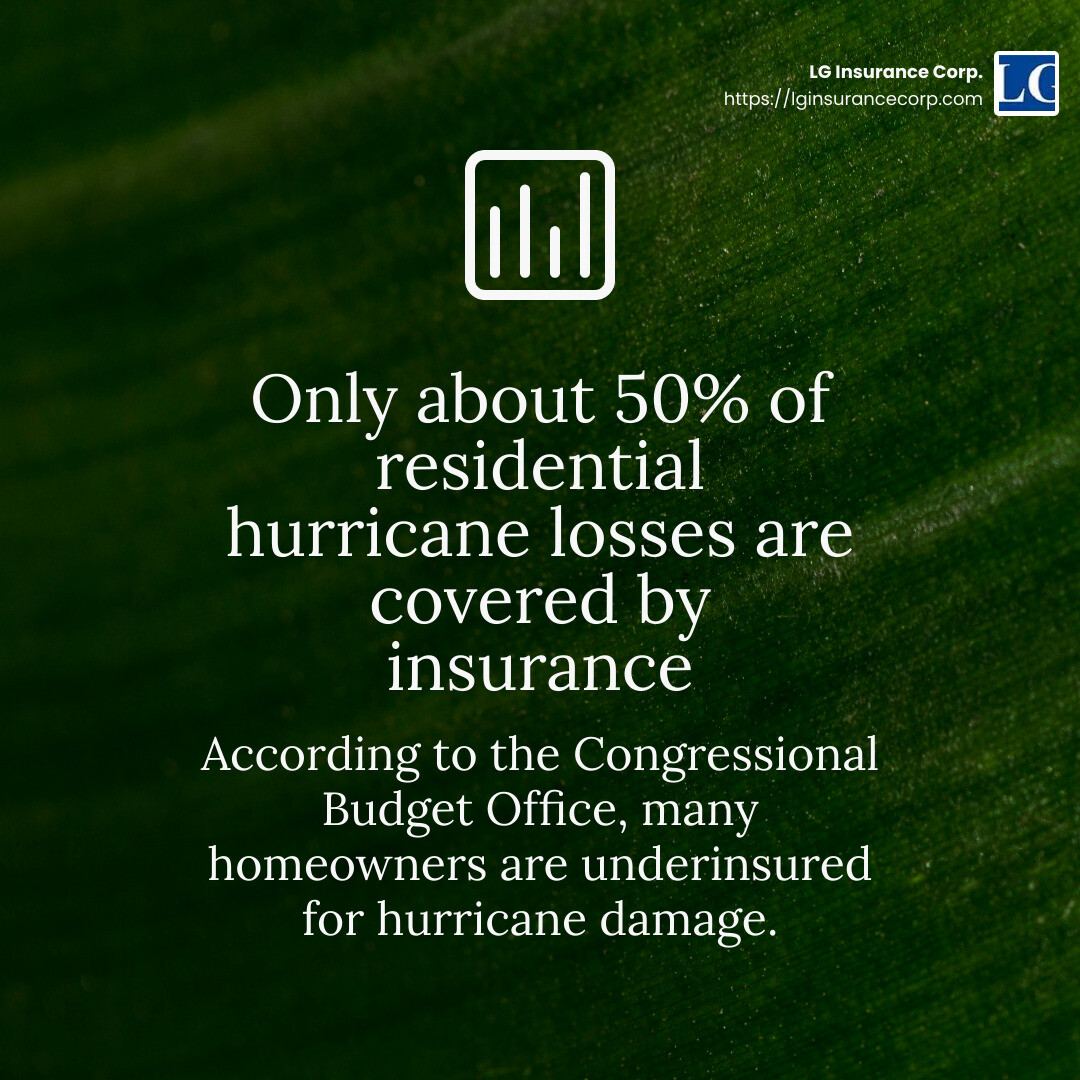
Flood insurance is a must in Miami-Dade. The Congressional Budget Office estimates that only about 50% of residential hurricane losses are covered by insurance. Given the area’s susceptibility to flooding, having a comprehensive flood insurance policy can save you from financial ruin.
In summary, understanding the nuances of hurricane damage insurance claims Miami-Dade is vital. Knowing what your policy covers, especially regarding wind and flood damage, can make a significant difference in your recovery process. Stay informed, review your coverage, and ensure you’re protected against all possible hurricane-related damages.
Filing Your Hurricane Damage Insurance Claim in Miami-Dade
Once a hurricane has passed, it’s crucial to act quickly to ensure your insurance claim is processed smoothly. Here’s how you can steer the process effectively:
Document Damage Thoroughly
Start by documenting all damage to your property. This includes taking clear, timestamped photos and videos of affected areas. Capture everything from structural damage to personal belongings. A detailed record will support your claim and help avoid disputes with your insurance company.
File Your Claim Immediately
Time is of the essence. Most insurance policies require you to file a claim as soon as possible after the damage occurs. Delaying can lead to complications or even denial of your claim. Make sure to follow any specific filing procedures outlined in your policy.
- Contact your insurer right away. Provide them with all necessary documentation and details about the damage.
- Keep a log of all communications with your insurer, noting dates, times, and the names of representatives you speak with.
Understand Your Insurance Policy Requirements
Every insurance policy has unique requirements. Familiarize yourself with the specifics of your policy to ensure compliance:
- Review your policy to understand what is covered, including any exclusions or limitations.
- Pay attention to any deductibles you may be responsible for, especially those related to hurricane or windstorm damage.
- If you have a separate flood insurance policy, file a claim with that provider as well for any flood-related damages.
Tip: Consider consulting with a professional, such as a lawyer or public adjuster, if you find the claims process overwhelming or if your claim is denied.
By promptly documenting damage, filing your claim, and understanding your insurance policy requirements, you can help ensure that you receive the compensation you need to recover from hurricane damage. This proactive approach is essential for anyone dealing with hurricane damage insurance claims Miami-Dade.
Steps to Protect Your Property Post-Hurricane
After a hurricane, your primary goal should be to protect your property from any further damage. This not only safeguards your home but also strengthens your position when filing insurance claims. Here’s how you can do it:
Cover Damaged Property
If your property has been damaged, cover it up as soon as it’s safe to do so. For instance, if your roof is damaged, use a tarp to prevent water from entering. This is crucial because insurance companies might deny claims for damages that occur after the hurricane if they believe you didn’t take steps to prevent further harm.
- Use tarps or plastic sheeting to cover roof damage.
- Secure broken windows with plywood or heavy-duty plastic.
Tip: If you can’t safely perform these tasks, hire a professional. Document any temporary repairs with photos to show your insurer you took action.
Prevent Further Damage
Stopping additional damage is not just about covering up. It also involves being proactive about other potential risks:
- Remove debris from around your home to prevent injury or more damage.
- Turn off utilities like gas and electricity if there are any leaks or water exposure.
- Check for water intrusion and dry out wet areas to prevent mold growth.
Safety Measures
Before you start any repairs, ensure your safety and that of your family:
- Inspect your property for downed power lines and avoid them.
- Be cautious of standing water, which can hide sharp debris or be electrically charged.
- Wear protective gear, like gloves and boots, when assessing damage or making repairs.
Quote: According to Miami-Dade County’s Department of Emergency Management, ensuring personal safety is the first step before conducting any damage assessment.
By securing your property and taking preventive measures, you not only protect your home but also bolster your hurricane damage insurance claims Miami-Dade. Insurers expect you to mitigate further damage to validate your claim.
Common Challenges in Hurricane Damage Claims
Navigating hurricane damage insurance claims in Miami-Dade can be tricky. Here are some common challenges you might face:
Claim Denial
One of the most frustrating experiences is having your claim denied. Insurance companies might reject claims for various reasons:
Pre-existing damage: Insurers may argue that your property was already damaged before the hurricane. Documenting the condition of your property before and after the storm with photos can help counter this claim.
Failure to mitigate damage: If you didn’t take steps to prevent further damage after the storm, such as covering a damaged roof, your claim might be denied. Always document temporary repairs with photos.
Policy Exclusions
Insurance policies can have exclusions that limit coverage. Common exclusions include:
Flooding: Standard homeowners or hurricane insurance policies often do not cover flood damage. This is a significant issue in Miami-Dade, where flooding is common. Separate flood insurance is usually required for flood-related claims.
Windstorm Coverage: Check your policy for wind-related damage coverage. Some policies may have specific exclusions or limitations on wind damage.
Insurance Company Tactics
Insurance companies may use tactics to delay or deny claims:
Lowball Offers: Insurers might offer settlements far below the actual cost of repairs. It’s important to know the value of your claim and negotiate if necessary.
Complex Documentation Requirements: Companies might request extensive documentation, hoping you’ll give up. Stay organized and provide all necessary documents promptly.
Lengthy Investigation Processes: Delays in processing can be frustrating. Keep in regular contact with your insurer and document all interactions.
Tip: If you’re struggling with your claim, consider seeking legal assistance. An experienced hurricane damage attorney can help you steer the process and fight for the compensation you deserve.
Understanding these challenges can better prepare you for the claims process and improve your chances of a successful outcome.
Frequently Asked Questions about Hurricane Damage Insurance Claims Miami-Dade
What is covered under hurricane damage insurance?
Hurricane damage insurance usually covers wind-related damages. This includes damage from high winds, flying debris, and sometimes hail. However, it’s crucial to understand that standard policies often have exclusions. For instance, flooding is generally not covered under standard homeowners or hurricane insurance policies. In Miami-Dade, where flooding is common, separate flood insurance is essential.
Tip: Always review your policy to understand what is and isn’t covered. Look for any specific exclusions or limitations related to windstorm damage.
How long do I have to file a claim in Florida?
In Florida, the deadline to file a hurricane damage insurance claim is generally three years from the date of the hurricane. However, it’s wise to file your claim as soon as possible. Filing early can help speed up the process and ensure you meet any specific timelines outlined in your policy.
Remember: Each insurance policy may have its own timelines and requirements. Always check your policy documents and consult with your insurance provider to avoid missing important deadlines.
What should I do if my claim is denied?
If your claim is denied, don’t panic. There are steps you can take:
Review the Denial Letter: Understand why your claim was denied. The letter should explain the reasons for denial.
Gather Documentation: Collect all relevant documents, including photos of the damage, repair estimates, and communication with your insurer.
Contact Your Insurer: Discuss the denial with your insurance company. Sometimes, providing additional information or clarification can resolve the issue.
Seek Legal Assistance: If you’re unable to resolve the denial, consider consulting with a legal professional. Experienced attorneys, like those at LG Insurance Corp., can help you steer the appeal process and fight for your rights.
File an Appeal: If necessary, formally appeal the decision. Your attorney can guide you through this process to improve your chances of a favorable outcome.
By understanding your coverage, acting promptly, and knowing your rights, you can better manage your hurricane damage insurance claims in Miami-Dade.
Conclusion
Navigating hurricane damage insurance claims in Miami-Dade can be daunting, but you don’t have to face it alone. At LG Insurance Corp., we are committed to providing expert advice and personalized support to help you through every step of the process. Our family-owned agency understands the unique challenges that come with living in hurricane-prone areas like South Florida.
Expert Advice: Our team is dedicated to guiding you through the complexities of insurance claims. We help you understand your policy, identify coverage gaps, and provide strategies to maximize your claim. Our expertise ensures that you’re fully informed and prepared to handle any insurance problems.
Community Support: We are more than just an insurance agency; we are part of the Miami-Dade community. We strive to support our neighbors by offering reliable insurance solutions that protect what matters most—your home, business, and peace of mind. Whether it’s through community events or one-on-one consultations, we are here to support you.
When hurricanes strike, having a trusted partner to assist with your insurance needs is invaluable. Let us help you secure the coverage you need and ensure that you’re well-prepared for any future storms. For more information and to explore our services, visit our Miami Home Insurance Claims page.
Trust LG Insurance Corp. to stand by your side, offering the support and guidance you need when it matters most.