How much is homeowners insurance in Miami? Due to the coastal beauty and vibrant lifestyle, many Miami homeowners face unique risks and costs. Potential hazards range from increasing sinkhole risks due to new development to the seasonal threat of hurricane damage. If you’re a Miami homeowner, you can expect to pay anywhere from $8,617 per year for older homes with no wind mitigation features to upwards of $22,398 annually for homes with comprehensive coverage.
Miami’s location makes it especially vulnerable to hurricanes and floods, causing insurance rates to surge over recent years. New homes with better wind-resistant designs tend to have lower insurance costs, while older structures incur higher premiums. Factors like the age and construction of your home, as well as the inclusion of wind mitigation features, significantly impact these costs.
As Leonard Garcia, owner of LG Insurance Agency, I bring over 20 years of experience in the Miami insurance market, helping residents understand how much is homeowners insurance in Miami. I’m committed to providing personalized, comprehensive insurance solutions to protect what matters most to my clients.
Easy how much is homeowners insurance in miami word list:
– average cost of homeowners insurance in miami
– affordable homeowners insurance miami florida
– homeowners insurance in miami dade county
Average Cost of Homeowners Insurance in Miami
How Much is Homeowners Insurance in Miami?
Homeowners insurance in Miami is notably higher than the national average due to the city’s susceptibility to hurricanes and floods. For a $150,000 home, you can expect to pay around $8,617 per year. If your home is valued at $300,000, the average annual premium jumps to $15,602. For a $450,000 home, the cost increases further to $22,398 per year.
These figures translate to monthly premiums of approximately $718, $1,300, and $1,867, respectively. These are averages; actual costs can vary based on several factors like the age of your home, its location, and the extent of coverage you choose.
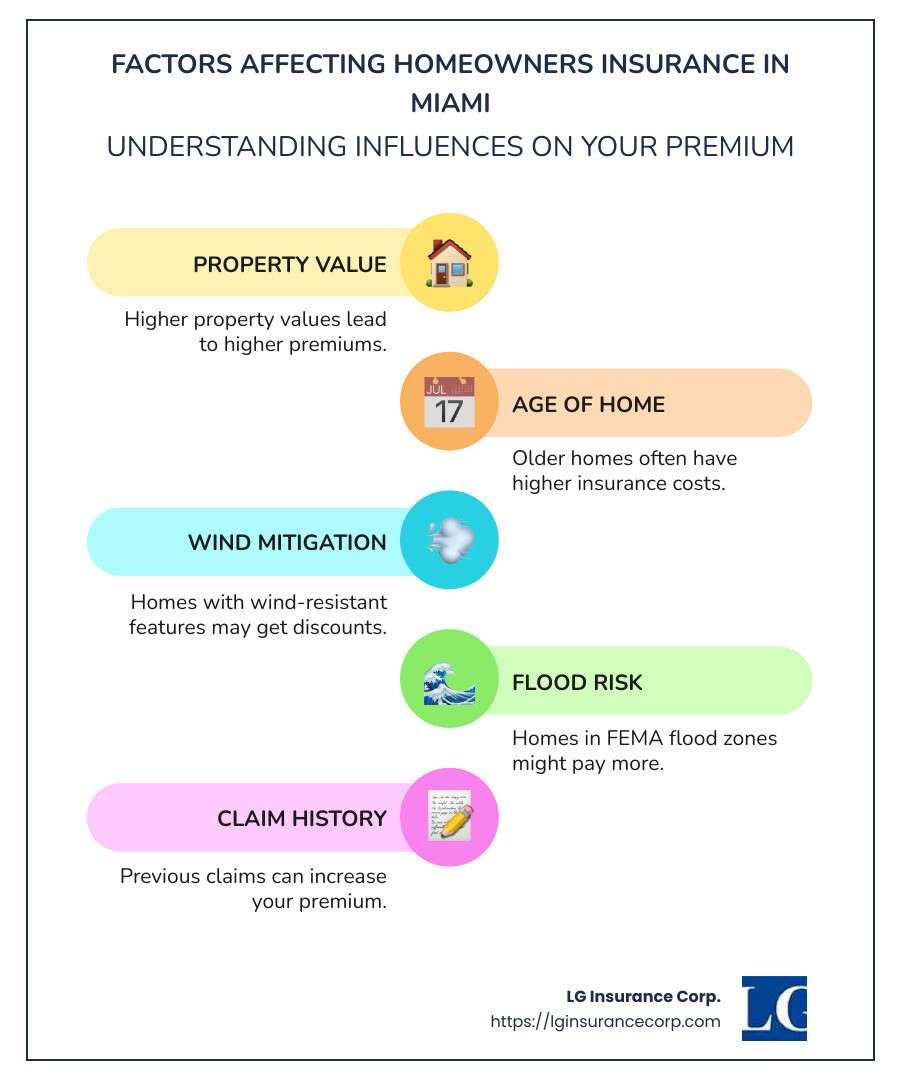
Factors such as your home’s construction date and whether it has wind mitigation features can significantly influence your premium. Homes built after 2005, which adhere to updated building codes, generally have lower insurance costs. Similarly, homes with effective wind mitigation features can see substantial savings on premiums.
Comparison of Average Rates by Provider
Miami’s insurance market is diverse, with several providers offering varying rates. Here’s a snapshot of what you might expect from different companies:
- Provider A: Known for competitive rates, offers around $4,366 for a $150,000 home.
- Provider B: Offers premiums at approximately $5,962.
- Provider C: Charges about $7,945 for similar coverage.
- Provider D: Offers rates around $8,807.
- Provider E: Has higher premiums, reaching up to $15,132.
- Provider F: Competitive rates at around $5,307.
- Provider G: Premiums are about $4,688.
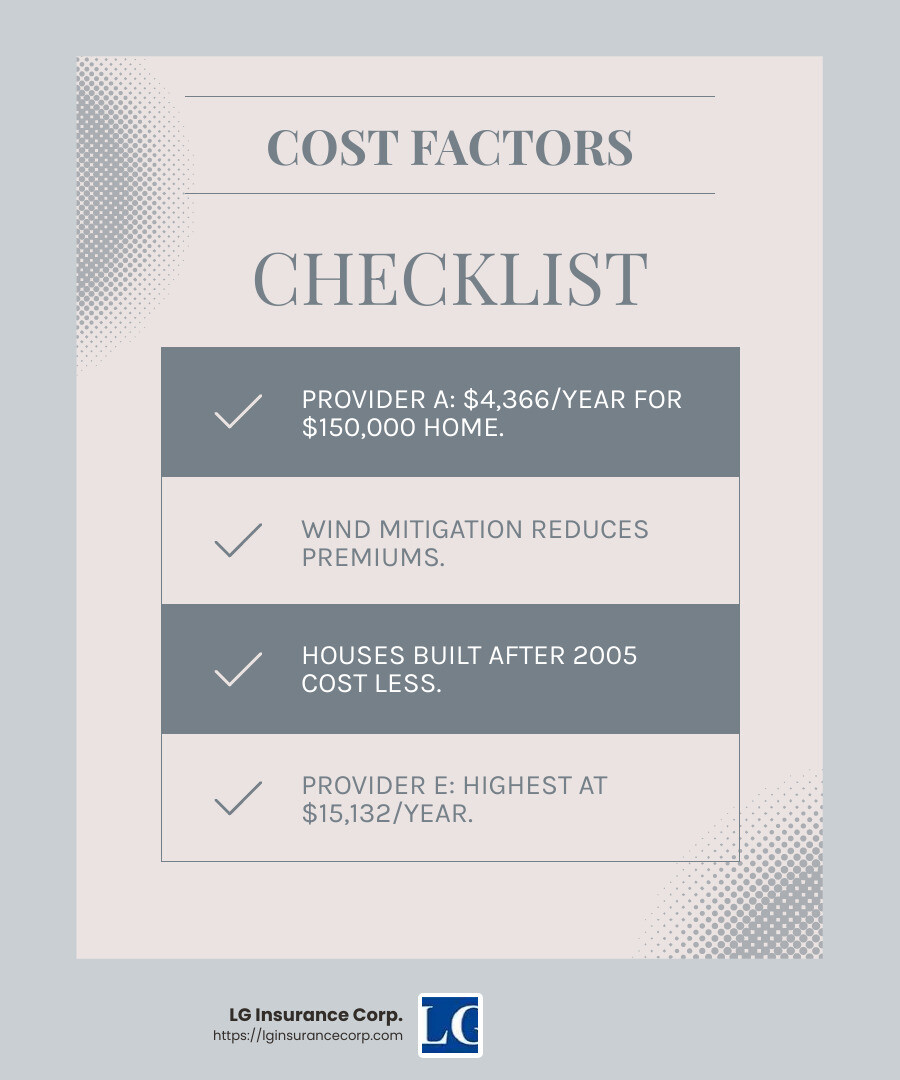
These rates highlight the importance of shopping around and comparing quotes from different insurers to find the best deal for your specific needs. Each provider assesses risk differently, so premiums can vary widely even for similar coverage levels.
Understanding how much is homeowners insurance in Miami involves considering these factors and exploring options custom to your home’s specific characteristics and your budget.
Factors Affecting Homeowners Insurance Rates in Miami
Wind Mitigation and Construction Date
In Miami, the age of your home and the presence of wind mitigation features are major factors affecting your insurance premium. Homes built before 2001 often face higher premiums due to older construction standards. Without wind mitigation, these homes can be more vulnerable to hurricane damage, leading to increased insurance costs.
For example, a home built in 1990 without wind mitigation features can see premiums as high as $14,156 annually for a $150,000 home. However, adding wind mitigation features like reinforced roofs and impact-resistant windows can drop premiums significantly.
Newer homes, especially those constructed after 2005, benefit from updated building codes designed to withstand hurricane-force winds. As a result, these homes generally have lower insurance costs. A $150,000 home built post-2005 might see average premiums around $5,571, thanks to these improved construction standards.
Impact of Hurricanes and Floods
Miami’s location makes it vulnerable to natural disasters like hurricanes and floods. This risk greatly influences homeowners insurance rates. Hurricane deductibles are a unique aspect of Florida insurance policies, often set as a percentage of your dwelling coverage, typically between 1% and 5%. This means if your home is insured for $300,000, you might have a hurricane deductible between $3,000 and $15,000.
Flooding is another significant risk. Standard homeowners insurance does not cover flood damage, so flood insurance is crucial, especially in high-risk areas. According to FEMA flood zone maps, many parts of Miami fall into high-risk categories, necessitating additional flood insurance coverage.
The threat of storm surges during hurricanes also lifts risk assessments, impacting premiums. Living in a flood zone or an area with high storm surge risk can increase insurance costs further, making flood insurance an essential consideration for Miami homeowners.
How to Save on Homeowners Insurance in Miami
Bundling Policies
One of the simplest ways to save on homeowners insurance in Miami is by bundling your home and auto insurance policies. When you purchase both types of coverage from the same provider, you often qualify for a discount. This not only lowers your premiums but also adds convenience by consolidating your insurance management under one company.
Wind Mitigation Measures
Implementing wind mitigation measures is another effective way to reduce your insurance costs. Miami homes, especially those built before 2001, can benefit significantly from these upgrades. Reinforcing your roof, installing impact-resistant doors, and upgrading to wind-resistant windows are all strategies that can lead to substantial savings on your premiums.
For example, a 1990 home without wind mitigation might face premiums as high as $14,156 annually for a $150,000 home. However, with wind mitigation features, this cost can drop significantly. Insurers often offer discounts for homes with these protective features because they reduce the risk of damage during hurricanes.
New Construction Benefits
If you’re considering buying or building a new home in Miami, opting for a property constructed after 2005 can offer additional savings. These homes are built to meet stringent building codes designed to withstand hurricane-force winds, resulting in lower insurance premiums. For instance, a $150,000 home built post-2005 might see average premiums around $5,571, thanks to these improved construction standards.
Higher Deductibles
Another way to lower your insurance premium is by opting for a higher deductible. While this means you’ll pay more out-of-pocket if you file a claim, it can significantly reduce your annual premium. Consider your financial situation and risk tolerance when deciding if this option is right for you.
Discounts
Many insurance providers offer various discounts that can help reduce your premium. These might include discounts for having a security system, being a loyal customer, or even being a non-smoker. It’s worth asking your insurance provider about any available discounts that you might qualify for.
By taking advantage of these strategies—bundling policies, implementing wind mitigation measures, choosing new construction, opting for higher deductibles, and seeking out discounts—you can make a significant dent in your homeowners insurance costs in Miami.
Additional Coverage Options for Miami Homeowners
In Miami, homeowners face unique challenges due to the city’s susceptibility to natural disasters like hurricanes and floods. Therefore, it’s crucial to consider additional coverage options beyond standard homeowners insurance.
Flood Insurance
Flooding is a significant concern for Miami residents, especially those living in high-risk areas. Homeowners insurance policies typically do not cover flood damage, so obtaining a separate flood insurance policy is essential.
The Federal Emergency Management Agency (FEMA) provides flood zone maps that help determine your flood risk. Areas starting with “A” or “V” are considered high-risk, and if you’re in these zones, your mortgage lender might require flood insurance. This coverage is vital because Miami’s proximity to the coast increases the likelihood of flooding from storm surges and heavy rains.
Sinkhole Coverage
Another risk Miami homeowners face is sinkholes, particularly with new developments. While sinkhole damage is not commonly covered under standard policies, you can opt for sinkhole coverage as an endorsement. This coverage protects against catastrophic ground collapse, which can occur more frequently with changes in land use and water table levels. Given Miami’s increased risk due to ongoing development, it’s wise to consider this additional protection.
Hurricane Coverage
Miami’s location makes it highly vulnerable to hurricanes. Hurricane coverage is a critical component of homeowners insurance in Florida, but it comes with its own deductible, usually between 2% and 5% of your dwelling coverage. This deductible is separate from your regular homeowners deductible and only applies once per hurricane season. Ensuring adequate hurricane coverage is vital, as hurricanes can cause extensive property damage.
Liability Coverage
Liability coverage is another important aspect of homeowners insurance. It protects you if someone is injured on your property or if you accidentally cause damage to someone else’s property. Given the litigious environment and high property values in Miami, having robust liability coverage can safeguard your financial well-being.
In conclusion, while standard homeowners insurance provides a good foundation, considering additional coverages like flood insurance, sinkhole endorsements, hurricane coverage, and liability protection is essential for Miami homeowners. These options help address the unique risks associated with living in this vibrant but vulnerable city.
Frequently Asked Questions about Homeowners Insurance in Miami
What is the average monthly cost of homeowners insurance in Miami?
In Miami, homeowners insurance costs can be quite high compared to the national average due to the city’s increased risk of natural disasters. For a home valued at $150,000, the average annual premium is $8,617, which breaks down to about $718 per month. For a $300,000 home, the cost rises to $15,602 per year or approximately $1,300 per month. Meanwhile, a $450,000 home sees an average annual premium of $22,398, equating to around $1,867 per month. These figures highlight the significant expense of insuring a home in Miami, largely due to the area’s vulnerability to hurricanes and floods.
Why is homeowners insurance so expensive in Miami?
Miami’s homeowners insurance is notably expensive primarily because of its high exposure to hurricanes and floods. The city is in a high-risk area, making it more susceptible to natural disasters, which drives up insurance costs. Additionally, reinsurance costs—the insurance that insurance companies purchase to protect themselves—are higher in Miami due to these risks. Litigation costs also contribute to the high premiums, as Florida has a litigious environment, leading to more claims and legal expenses for insurers. These factors collectively make Miami one of the most expensive cities for homeowners insurance in Florida.
How can I reduce my homeowners insurance premium in Miami?
Despite the high costs, there are several strategies to potentially lower your homeowners insurance premium in Miami:
Bundling: Consider bundling your home and auto insurance policies with the same provider. This often results in discounts.
Wind Mitigation: Implementing wind mitigation measures, such as installing impact-resistant windows and reinforced roofing, can significantly reduce premiums since they help protect your home from hurricane damage.
Higher Deductibles: Opting for a higher deductible can lower your premium. However, ensure you can afford the deductible amount in the event of a claim.
Discounts: Inquire about any available discounts. Some insurers offer price reductions for installing security systems, being claim-free, or even for loyalty.
By taking these steps, you can manage the costs of homeowners insurance while still maintaining necessary coverage.
Conclusion
In conclusion, understanding the costs and factors affecting homeowners insurance in Miami is crucial for making informed decisions. Given the city’s unique risks, such as hurricanes and floods, insurance premiums can be higher than in other areas. However, there are ways to manage these costs effectively.
At LG Insurance Corp., we pride ourselves on offering custom policies custom to meet the specific needs of Miami homeowners. Our focus is on providing affordable rates without sacrificing the quality of coverage. We understand the complexities of the local insurance market and are committed to offering expert advice to help you steer your options.
Our family-owned agency is deeply rooted in the community, and we strive to support our clients with customer-centric service. Whether it’s through helping you bundle policies for added savings or advising on wind mitigation measures to reduce premiums, we are here to assist you every step of the way.
For more information on how we can help protect your home, visit our home insurance page. Let us help you safeguard your biggest asset with the right coverage at the right price.