Understanding Homeowners Insurance in Miami-Dade County
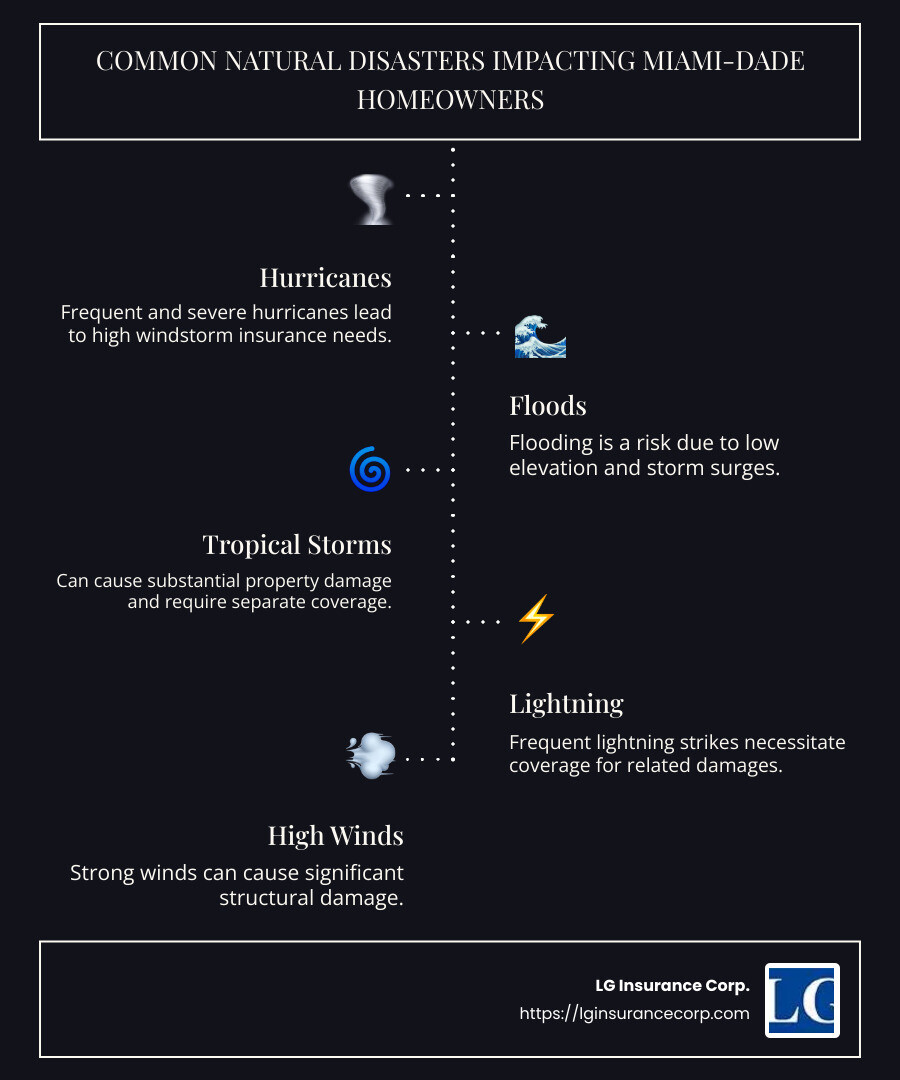
Homeowners insurance in miami dade county is essential for protecting your home against various risks, especially given the area’s vulnerability to natural disasters like hurricanes and floods. Here’s what you need to know in brief:
- Location Matters: Miami-Dade’s coastal position increases the risk of flood and wind damage, affecting insurance availability and premiums.
- Hurricane Season: Higher hurricane deductibles apply only once per season, but they can be significant.
- Flood Coverage: Not included in standard policies; separate flood insurance is often required.
The need for homeowners insurance in miami dade county extends beyond just financial protection. It often becomes a critical component of property ownership, where understanding local risks and specific insurance requirements is vital.
I’m Leonard Garcia, owner and founder of LG Insurance Agency. With over 20 years of experience, I specialize in providing custom insurance policies to meet the unique requirements of the Miami-Dade community. Let’s dig into the complexities and requirements of homeowners insurance in miami dade county.
Common homeowners insurance in miami dade county vocab:
– Miami home insurance rates
– affordable homeowners insurance miami florida
– home insurance companies miami fl
Understanding Homeowners Insurance in Miami-Dade County
Average Cost of Homeowners Insurance
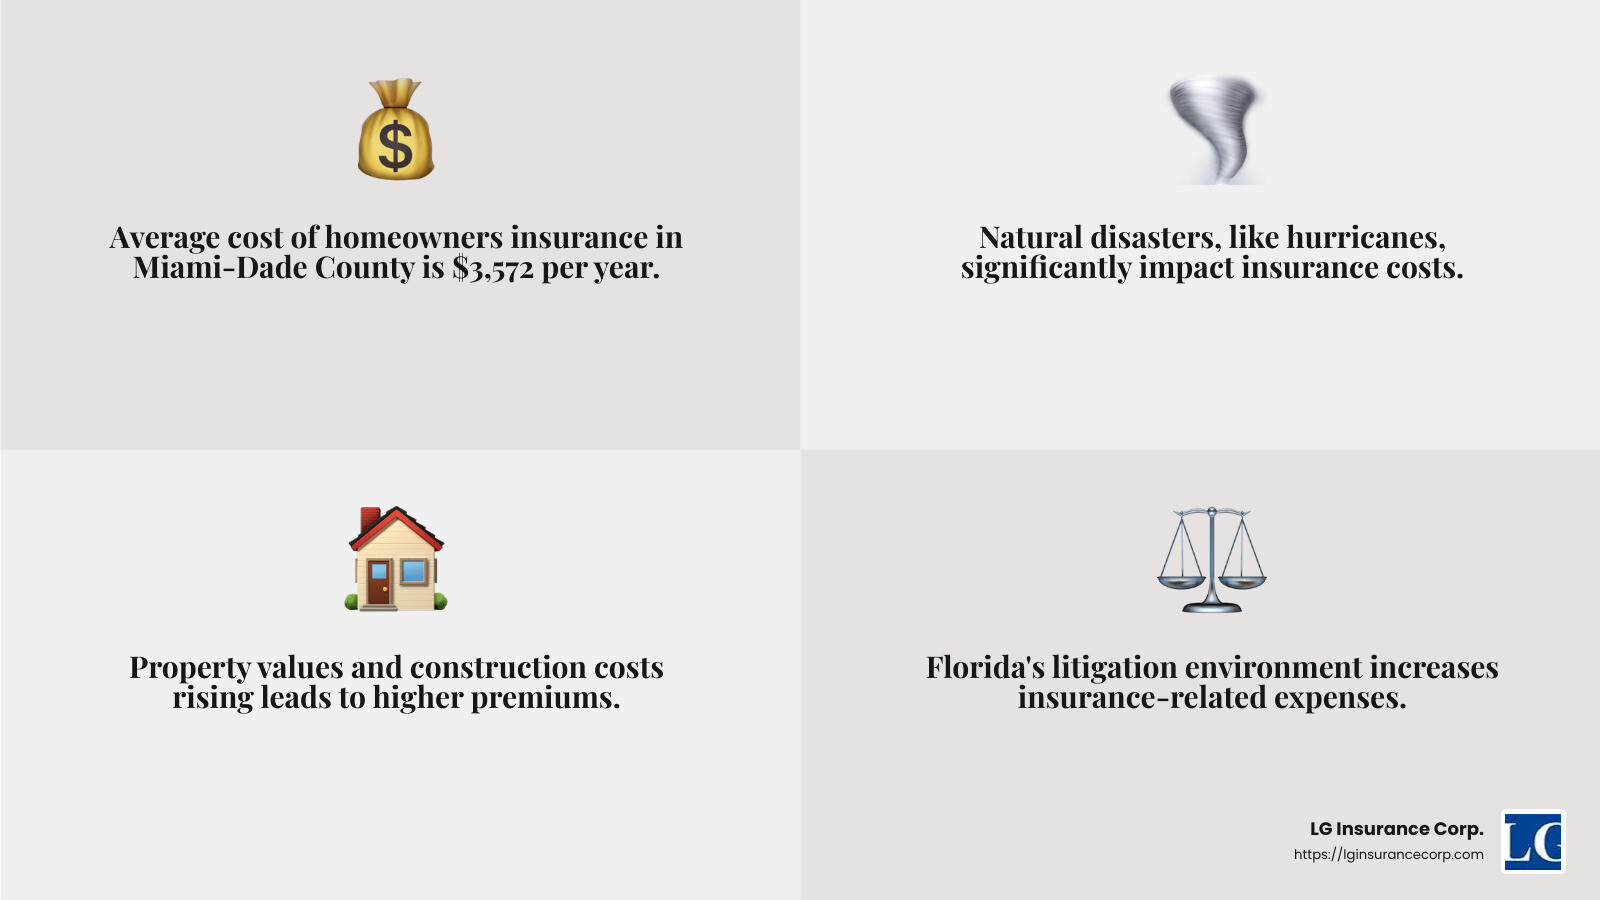
In Miami-Dade County, the average cost of homeowners insurance is notably higher than the national average. Homeowners pay about $3,572 per year or $298 a month for a typical policy covering a $300,000 dwelling. This high cost is driven by several factors, including the area’s exposure to natural disasters and the increasing costs of construction and property values.
Types of Coverage
Homeowners insurance policies in Miami-Dade typically include several types of coverage:
- Standard Policies: These cover the dwelling, personal property, liability, and additional living expenses if your home becomes uninhabitable due to a covered loss.
- Windstorm Coverage: Given Miami-Dade’s susceptibility to hurricanes, windstorm coverage is crucial. It protects against damage caused by high winds, which are common during hurricane season.
- Flood Insurance: Flood damage is not covered under standard homeowners policies. In Miami-Dade, many homes are in flood-prone areas, making separate flood insurance a necessity. Mortgage lenders often require it for homes in high-risk flood zones.
- Additional Living Expenses: This coverage helps pay for temporary housing and other costs if you’re displaced from your home due to a covered event.
Factors Affecting Insurance Rates
Several factors influence the cost of homeowners insurance in miami dade county:
- Natural Disasters: The risk of hurricanes and floods significantly impacts premiums. Insurers factor in the likelihood of these events when setting rates.
- Property Values and Construction Costs: As property values and construction costs rise, so do insurance premiums. Insurers must account for the increased cost to rebuild or repair homes.
- Litigation Environment: Florida’s legal environment can lead to higher insurance costs due to increased litigation and claims-related expenses.
- Reinsurance Costs: Insurers often rely on reinsurance to manage risk, and the cost of reinsurance can influence the price of homeowners insurance. In regions prone to natural disasters, reinsurance can be particularly expensive.
Understanding these components can help homeowners make informed decisions about their insurance needs and find ways to manage costs effectively.
Top Homeowners Insurance Providers in Miami-Dade
When it comes to securing homeowners insurance in Miami-Dade County, choosing the right provider is crucial. Here, we highlight some of the top insurance companies that offer reliable coverage options to suit various needs.
LG Insurance Corp.
LG Insurance Corp. stands out as a premier choice for homeowners in Miami-Dade. Known for its comprehensive coverage and customer-centric approach, LG Insurance Corp. has earned a reputation for excellence. With a solid 4 out of 5 rating, the company is recognized for its commitment to providing personalized insurance solutions.
What sets LG Insurance Corp. apart is its focus on helping clients steer the unique challenges of insuring homes in a region prone to natural disasters. They offer a range of policies that include standard homeowners insurance, windstorm coverage, and optional flood insurance. This ensures that homeowners are well-protected against the elements that frequently impact the area.
Moreover, LG Insurance Corp. provides competitive rates and flexible policy options, catering to both first-time homeowners and those looking to switch providers. By leveraging their extensive network of insurance partners, they can tailor policies to fit individual needs and budgets.
Other Local Providers
In addition to LG Insurance Corp., several other local providers offer competitive rates and a variety of coverage options for homeowners insurance in Miami-Dade County, Florida. These companies understand the specific needs of Miami-Dade residents and provide custom solutions to meet those needs.
Local providers often offer unique benefits such as multi-policy discounts, which can significantly reduce premiums for homeowners who bundle their home and auto insurance. They also provide specialized coverage options that address the risks associated with living in a coastal area, such as improved windstorm protection and flood insurance.
Choosing the right insurance provider involves considering factors like customer service, claim handling, and the range of coverage options available. By comparing offerings from LG Insurance Corp. and other local providers, homeowners in Miami-Dade can find the best policy to protect their property and peace of mind.
Tips for Lowering Your Homeowners Insurance Premiums
Reducing your homeowners insurance in Miami-Dade County premiums can be easier than you think. With a few strategic steps, you can make your home safer and your wallet happier.
Wind Mitigation Measures
Wind mitigation is a game-changer. By strengthening your home against hurricane-force winds, you can significantly lower your insurance costs. Start with your roof. Reinforce it with methods such as installing hurricane clips or straps that connect the roof to the walls of your house.
Impact-resistant doors and windows are another essential upgrade. These features not only protect your home but can also lead to substantial savings on your insurance premiums. Consider this: homes with effective wind mitigation features can save thousands annually on insurance costs.
Available Discounts
Insurance companies love rewarding safety and loyalty. Here’s how you can benefit:
- Multi-policy discounts: Bundle your home and auto insurance with the same provider to enjoy lower rates. This is a simple yet effective way to cut costs.
- Safety features: Installing smoke detectors, burglar alarms, and home security systems can qualify you for additional savings. These features reduce the risk of claims, making your home a safer bet for insurers.
- Loyalty discounts: Staying with the same insurance company over time can sometimes earn you a discount. Check with your provider to see if they offer this.
Other Considerations
Keep an eye on your roof condition and claims history. A well-maintained roof is less likely to suffer damage during a storm, which can keep your premiums in check. And while it might be tempting to file small claims, consider paying out of pocket for minor repairs. A clean claims history can help keep your rates low.
By implementing these strategies and exploring tailored policies for homeowners in Miami-Dade County, Florida, you can enjoy peace of mind knowing your home is protected without breaking the bank. Up next, we’ll dig into special considerations for homeowners in Miami-Dade County, including flood zones and hurricane deductibles.
Special Considerations for Miami-Dade Homeowners
Living in Miami-Dade County comes with its own unique set of challenges, especially when it comes to protecting your home. Let’s explore some special considerations you need to be aware of.
Flood Insurance
Flooding is a significant risk in Miami-Dade, particularly due to its low elevation and proximity to the coast. Homeowners insurance does not cover flood damage, making flood insurance a must-have for many residents. If your property is located in a high-risk flood zone, your mortgage lender will likely require you to purchase flood insurance. These zones are designated by FEMA, and their maps can help you determine your risk level.
Even if you’re not in a designated flood zone, it’s wise to consider flood insurance. Storm surges from hurricanes can cause flooding in unexpected areas, and having coverage can save you from financial ruin.
Hurricane Deductibles
In Florida, hurricanes are a fact of life, and hurricane deductibles are a key part of homeowners insurance policies. Unlike standard deductibles, these are percentage-based, typically ranging from 1% to 10% of your dwelling coverage. The good news is that hurricane deductibles apply only once per hurricane season, so if multiple storms hit, you’re not paying the deductible each time.
Mobile Home Insurance
Mobile homes present unique risks, especially in storm-prone areas like Miami-Dade. For mobile homeowners, an HO-7 policy is essential. This type of policy is custom to cover the specific risks associated with mobile homes, which are often more vulnerable to wind and water damage. Make sure your policy covers these unique risks to ensure you’re fully protected.
Condo Insurance
Condo owners need to be aware of the differences in coverage compared to traditional homes. An HO-6 policy is designed specifically for condo units, covering the interior of your unit and your personal property. It also protects against specific perils like fire and theft. Since the condo association’s master policy usually covers the building’s structure, your HO-6 policy fills in the gaps, ensuring that your belongings and any interior improvements are secure.
For those seeking homeowners insurance in Miami-Dade County, Florida, understanding these special considerations can help you make informed decisions about your homeowners insurance in Miami-Dade County. It’s crucial to tailor your coverage to meet the unique challenges of living in this vibrant yet vulnerable region.
Frequently Asked Questions about Homeowners Insurance in Miami-Dade County
How much does home insurance cost in Miami-Dade County?
The average cost of homeowners insurance in Miami-Dade County is about $3,572 per year, or approximately $298 per month, for a property with $300,000 in dwelling coverage. However, keep in mind that this is just an average. Your actual premium can vary based on several factors.
Factors influencing the cost include the age and condition of your home, your credit and claims history, and the level of coverage you select. Also, the likelihood of natural disasters, like hurricanes and floods, plays a significant role. Miami-Dade’s high risk for these events contributes to its higher insurance rates compared to other regions.
Is windstorm coverage included in standard policies?
In Miami-Dade, windstorm coverage is crucial because of the area’s vulnerability to hurricanes. While some standard homeowners insurance policies offer windstorm coverage, it’s often not included and must be purchased separately or as a rider. Even if windstorm coverage is included, there is usually an additional hurricane deductible that applies. This deductible is typically a percentage of your dwelling coverage, ranging from 1% to 10%.
High-risk areas, particularly those closer to the coast, may have stricter requirements or higher deductibles. Make sure to review your policy details or consult with your insurance provider to understand what is covered and any additional costs involved.
Do I need flood insurance if I’m not in a designated flood zone?
Even if you’re not in a designated flood zone, flood insurance can be a wise investment in Miami-Dade County. The area’s low elevation and susceptibility to storm surges from hurricanes mean that flooding can occur unexpectedly, even in areas not officially classified as high-risk.
FEMA flood maps can help you determine your risk level, but these maps might not capture all potential flood risks. Investing in flood insurance can provide peace of mind and financial protection against unforeseen water damage, safeguarding your home and assets from costly repairs.
Conclusion
Securing the right homeowners insurance in Miami-Dade County is more than just a financial decision—it’s a crucial step in protecting your home from the unpredictable nature of Florida’s weather. With the region’s high risk for hurricanes and floods, having comprehensive coverage is essential to safeguard your property and peace of mind.
At LG Insurance Corp., we understand the unique challenges Miami-Dade homeowners face. Our family-owned agency is committed to providing personalized and expert advice to help you steer these complexities. We pride ourselves on our customer-centric approach, ensuring you receive the coverage that best fits your needs.
Community support is at the heart of what we do. We believe in empowering our clients with the knowledge and resources to make informed insurance decisions. Whether it’s understanding the nuances of hurricane deductibles or exploring flood insurance options, our team is here to guide you every step of the way.
For more information on how we can help you secure the right homeowners insurance in Miami-Dade County, Florida, visit our home insurance page. Let us help you protect what matters most with confidence and care.