Do Miami homeowners have flood insurance? The simple answer is: not all of them do, but many should consider it. Here’s why:
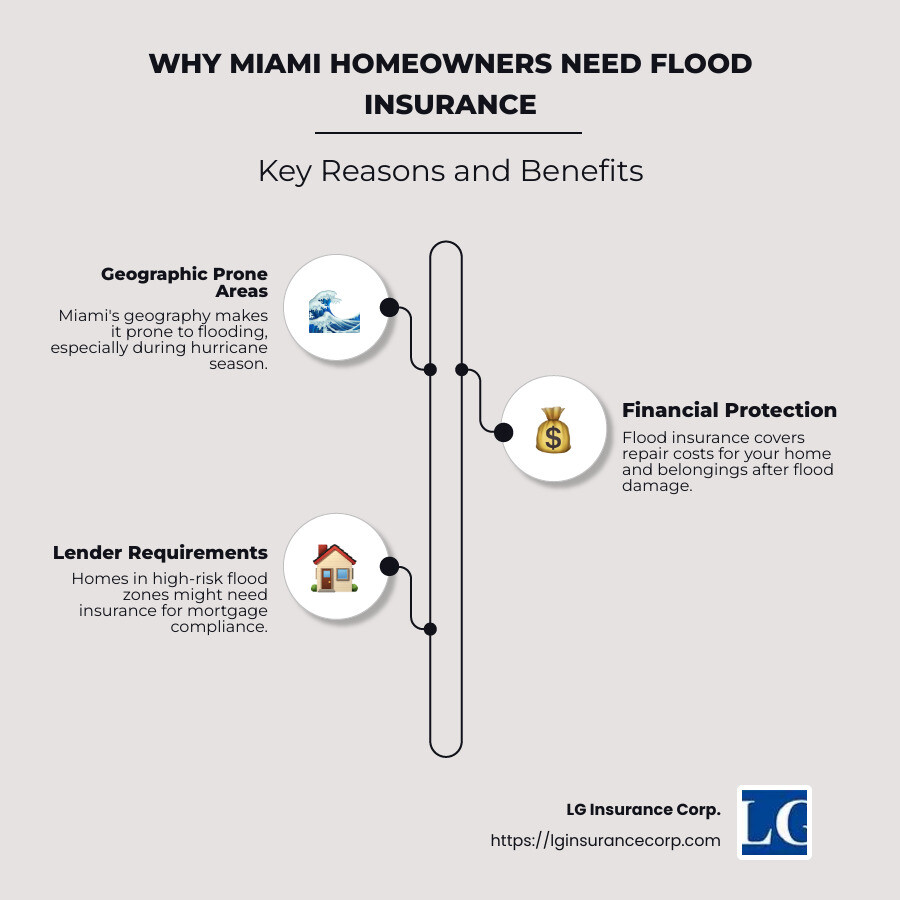
- Flood insurance is not typically included in standard homeowners insurance policies.
- Miami’s geography makes it prone to flooding, especially during hurricane season.
- Lenders might require flood insurance for homes in high-risk flood zones.
Despite Miami’s sunny reputation, the threat of flooding is significant and real to its homeowners. With changing climate patterns and rising sea levels, protecting your home with flood insurance has never been more critical. Flood insurance helps cover the costs of repairing your home and belongings after flood damage.
At LG Insurance Corp., we understand that navigating insurance policies can be daunting. I’m Leonard Garcia, founder of LG Insurance Corp, dedicated to providing custom and professional insurance solutions to the Miami community for over 20 years. Our aim is to ensure homeowners like you understand the importance of flood insurance in protecting your most valuable asset.
Do miami homeowners have flood insurance terms to learn:
– Miami home insurance claims
– homeowners insurance in miami dade county
– home insurance companies miami fl
Do Miami Homeowners Need Flood Insurance?
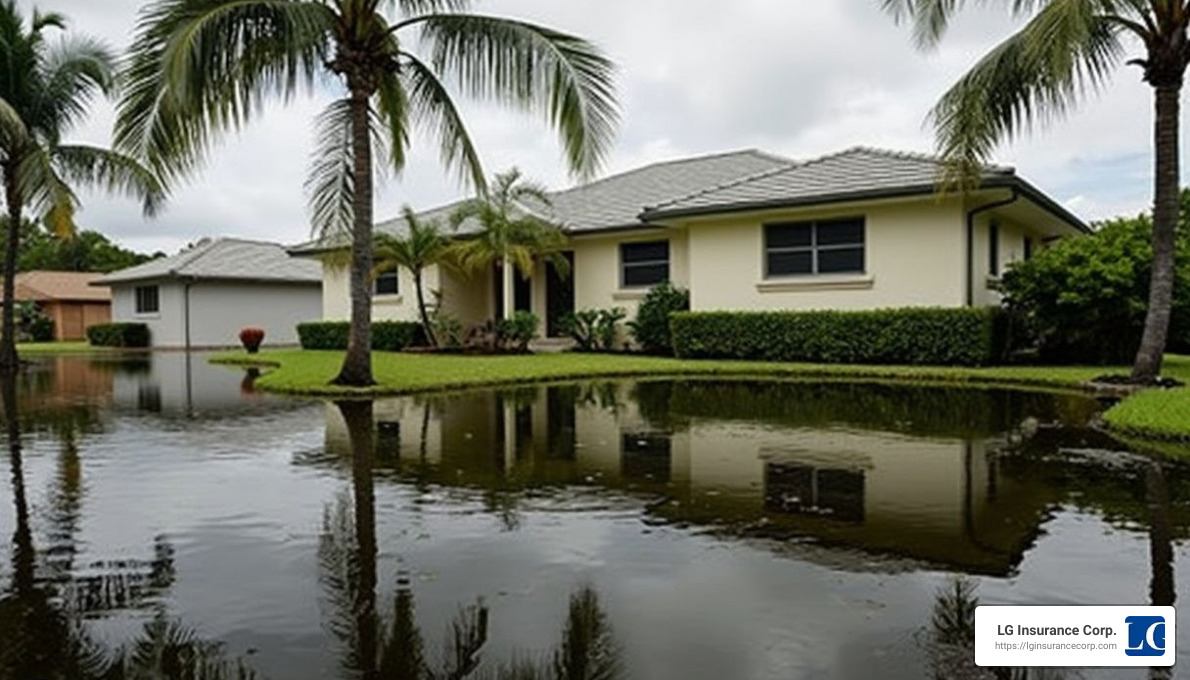
Flooding is a significant risk for Miami homeowners. The city is particularly vulnerable due to its low elevation and proximity to the coast. This section explores the necessity of flood insurance for Miami residents, focusing on flood zones and relevant regulations.
Flood Zones in Miami
Flood zones are areas identified by the Federal Emergency Management Agency (FEMA) as having varying levels of flood risk. In Miami, these zones are determined using Flood Insurance Rate Maps (FIRM). These maps help identify Special Flood Hazard Areas (SFHA), which are regions at high risk of flooding.
To understand if your property falls within a flood zone, you can consult the Planning and Zoning Department. They use FIRM maps to provide accurate flood zone determinations. Properties in an SFHA are more likely to experience flooding, and homeowners in these areas are often required to purchase flood insurance for federally backed mortgages.
Federal and State Regulations
Federal and state laws play a crucial role in flood insurance requirements for Miami homeowners. Under federal law, if you have a federally backed mortgage on a home in an SFHA, you must have flood insurance. This requirement is part of the National Flood Insurance Program (NFIP), which provides flood insurance to property owners, renters, and businesses.
In addition to federal mandates, Florida law also encourages flood insurance coverage through programs like the Community Rating System (CRS). This voluntary program recognizes communities that engage in floodplain management activities beyond the minimum NFIP standards, offering discounts on flood insurance premiums as an incentive.
Miami-Dade County participates in the CRS, achieving a Class 5 rating, which provides residents a 25% discount on flood insurance premiums in flood zones and a 10% discount outside these zones. This makes flood insurance more affordable and accessible for many Miami homeowners.
As climate change continues to affect weather patterns, the importance of understanding flood risk and insurance requirements cannot be overstated. Miami homeowners should seriously consider flood insurance, not only as a legal requirement in some cases but also as a vital safeguard for their homes and financial security.
What Does Flood Insurance Cover?
Flood insurance is a crucial safeguard for Miami homeowners, especially given the city’s vulnerability to flooding. It offers two main types of coverage: building property coverage and personal property coverage. Understanding what each covers can help homeowners make informed decisions.
Building Property Coverage
Building property coverage focuses on the physical structure of your home. It’s designed to protect the essential components that keep your house functional and safe. Here’s what it typically includes:
- Electrical and Plumbing Systems: Floods can cause severe damage to these systems, which are vital for your home’s operation.
- Water Heaters and Furnaces: These appliances are critical for everyday comfort and can be costly to repair or replace if damaged by floodwaters.
- Foundation Walls: The structural integrity of your home depends on your foundation. Flood insurance helps cover repairs to these crucial elements.
- Built-in Appliances and Cabinets: Permanent fixtures like kitchen cabinets and built-in ovens are also covered.
- Detached Garages: If you have a separate garage, flood insurance can help cover damages to this structure as well.
This coverage can significantly reduce the financial burden of repairing or rebuilding your home after a flood. The costs associated with these repairs can be substantial, especially in a high-risk flood area like Miami.
Personal Property Coverage
Personal property coverage protects the belongings inside your home. This includes items that are essential to your daily life and comfort:
- Clothing and Furniture: From your wardrobe to your living room sofa, these items are covered against flood damage.
- Electronics: Gadgets like TVs, computers, and sound systems can be expensive to replace, and flood insurance ensures you won’t have to bear the full cost.
- Curtains and Portable Air Conditioners: Often overlooked, these items can also be covered, providing peace of mind.
Flood insurance also covers flood debris removal and clean-up costs, which can be a significant expense after a flooding event. The clean-up process is crucial to restoring your home to a livable condition and preventing further damage.

By understanding the specific protections offered by flood insurance, Miami homeowners can better prepare for potential flooding events and ensure their homes and belongings are adequately safeguarded.
Cost of Flood Insurance in Miami
Flood insurance costs for Miami homeowners can vary widely, influenced by several key factors. Understanding these can help you anticipate expenses and explore ways to reduce them.
Factors Affecting Cost
Flood Zone: Your property’s location in a flood zone is a primary factor in determining insurance costs. Miami has areas designated as high-risk flood zones, identified by FEMA’s Flood Insurance Rate Maps (FIRM). Properties in these zones generally face higher premiums.
Property Elevation: Homes built above the base flood elevation can benefit from lower insurance rates. Elevation certificates, which document your property’s elevation, can be crucial in proving this.
Building Type: The type of building, whether a single-family home or a multi-unit structure, affects the cost. Different building types have varying vulnerabilities to flood damage.
Coverage Amount: The amount of coverage you choose also impacts the premium. Higher coverage limits for building and personal property will increase costs.
Community Rating System (CRS): Miami participates in FEMA’s Community Rating System, which rewards communities for floodplain management activities. Homeowners in areas with high CRS ratings may receive discounts on their flood insurance premiums.
Reducing Flood Insurance Costs
Elevation Certificates: Obtaining an elevation certificate can demonstrate that your home is liftd above the base flood elevation, potentially lowering your insurance premiums.
Map Amendments: If you believe your property is incorrectly classified in a high-risk zone, you can request a map amendment from FEMA. This process, if successful, can reclassify your property into a lower-risk zone.
Floodproofing: Investing in floodproofing measures, such as installing flood barriers or improving drainage systems, can reduce your flood risk and may lead to lower insurance costs.
CRS Discounts: Take advantage of any CRS discounts available in your community. These discounts are based on local efforts to reduce flood risk and can significantly cut your insurance expenses.
By understanding these factors and taking proactive steps, Miami homeowners can manage and potentially reduce the cost of flood insurance, ensuring their homes are protected without breaking the bank.
Steps to Obtain Flood Insurance
Getting flood insurance in Miami is an essential step for protecting your home and belongings from potential flood damage. Here’s how you can steer the process and choose the right policy for your needs.
How to Choose the Right Policy
When considering flood insurance, it’s crucial to select a policy that fits your specific situation. Here are some key steps:
Contacting Insurance Agents: Start by reaching out to insurance agents who are experienced in flood insurance. They can provide valuable insights into the types of policies available and help you understand your coverage options.
Policy Options: Flood insurance policies come in various forms. The most common are standard policies under the National Flood Insurance Program (NFIP), which cover both building and personal property. If you live in a low-risk area, you might qualify for a preferred risk policy, which offers lower premiums.
Coverage for Contents: Consider whether you need coverage for personal belongings. This can include items like clothing, furniture, and electronics. Make sure your policy covers the contents of your home if you want to protect these items.
Business Coverage: If you own a business in Miami, you should also explore flood insurance options custom for commercial properties. These policies can cover business equipment and inventory, ensuring your business can recover after a flood event.
Waiting Period: Be aware that most flood insurance policies have a waiting period before coverage begins. For NFIP policies, this is typically 30 days, but it can be shorter if the policy is purchased in connection with a loan closing.
Coverage Limits: Decide on the coverage limits that make sense for your property and belongings. The NFIP offers up to $250,000 for building coverage and $100,000 for contents coverage, but private insurers may offer higher limits.
Where to Buy Flood Insurance
Once you’ve decided on the type of policy you need, the next step is to purchase it. Here’s where you can obtain flood insurance:
Insurance Agencies: Many local insurance agencies in Miami offer flood insurance. They can provide quotes from both the NFIP and private insurers, allowing you to compare options.
National Flood Insurance Program (NFIP): This program is managed by FEMA and provides flood insurance to homeowners, renters, and businesses. You can purchase an NFIP policy through a certified insurance agent.
Private Insurers: Some private insurance companies offer flood insurance policies that may provide additional coverage options or higher limits than the NFIP. It’s a good idea to compare quotes from multiple private insurers to ensure you’re getting the best deal.
By following these steps and carefully considering your policy options, you can secure the right flood insurance coverage for your Miami home or business. This will provide peace of mind and financial protection in the event of a flood.
Frequently Asked Questions about Flood Insurance for Miami Homeowners
Do Miami homeowners have flood insurance?
Many Miami homeowners are aware of the flood risks but not all have flood insurance. According to the National Flood Insurance Program (NFIP), flood insurance is crucial in Miami due to the high flood risk in many areas. Miami’s geography and climate make it prone to flooding, especially during hurricane season. Yet, not every homeowner has a policy. Some rely on standard homeowner’s insurance, which typically does not cover flood damage.
Statistics show that properties with federally backed mortgages in Special Flood Hazard Areas (SFHA) are required by law to have flood insurance. However, homeowners outside these zones often skip this coverage, which can be a risky decision given the unpredictability of weather patterns.
Is flood insurance mandatory in Miami?
Flood insurance is mandatory for Miami properties located in high-risk flood zones, especially when a home has a federally backed mortgage. These are often designated as Special Flood Hazard Areas (SFHA) on FEMA’s Flood Insurance Rate Maps (FIRM). Federal law requires homeowners in these areas to maintain flood insurance as a condition of their mortgage.
Florida state regulations also support this requirement, emphasizing the importance of flood insurance due to the state’s vulnerability to hurricanes and heavy rains. Even for homes outside high-risk areas, flood insurance is recommended, as floods can occur anywhere.
How can I find out if my property is in a flood zone?
To determine if your property is in a flood zone, you can use several resources:
FEMA Maps: The FEMA website provides access to Flood Insurance Rate Maps (FIRM), which show flood zones and risk levels. These maps are a starting point to understand if your property is in a high-risk area.
Planning and Zoning Department: The Miami-Dade County Planning and Zoning Department can provide more detailed flood zone information and help you understand local regulations.
Online Resources: There are various online tools available that allow you to input your address and find out your flood zone status. These tools often provide additional insights into flood risks and insurance requirements.
By checking these resources, Miami homeowners can make informed decisions about purchasing flood insurance, ensuring they have the necessary protection against flood damage.
Conclusion
In Miami, where the risk of flooding is a constant concern due to its unique geography and frequent hurricanes, having flood insurance is not just a precaution—it’s a necessity. Flood insurance provides vital protection for homeowners, covering damages that standard homeowner’s policies typically do not. This coverage can be the difference between a manageable recovery and a financial disaster following a flood event.
Flood insurance not only protects your property but also offers peace of mind. It ensures that you are not left footing the bill for costly repairs or replacements after a flood. With Miami’s high flood risk, especially in designated Special Flood Hazard Areas (SFHA), having a policy is crucial. Even properties outside these high-risk zones can benefit from flood insurance, as floods can happen anywhere, often unexpectedly.
At LG Insurance Corp., we understand the importance of safeguarding your home against floods. Our team is committed to providing expert advice and personalized service to help you choose the right flood insurance policy. We offer a range of options to suit your needs and budget, ensuring you have the protection you need.
Don’t wait for the next storm to consider your flood insurance needs. Contact LG Insurance Corp. today to learn more about how we can help you protect your home and secure your financial future.