Commercial property insurance cost is a crucial consideration for small businesses striving to manage expenses while safeguarding assets. Understanding this cost means assessing several factors critical to your business’s location, assets, and risks, ultimately determining insurance premiums. Key elements influencing costs include the property’s value, your business type, and the region’s risk factors, such as climate and crime rates.
Small businesses face numerous challenges, from managing property-related risks to protecting valuable assets. Having the right insurance can be the difference between staying afloat after a disaster and closing shop. With commercial property insurance, small business owners are shielded from financial turmoil caused by theft, fire, or other unexpected events.
I’m Leonard Garcia, owner of LG Insurance Agency in Miami. With over 20 years of experience, I focus on personalized insurance solutions, especially in commercial property insurance cost, ensuring your business is protected. Let’s explore the factors influencing the cost and explore how you can optimize your coverage.
Commercial property insurance cost word roundup:
– commercial property insurance online quote
– property insurance quote
Factors Influencing Commercial Property Insurance Cost
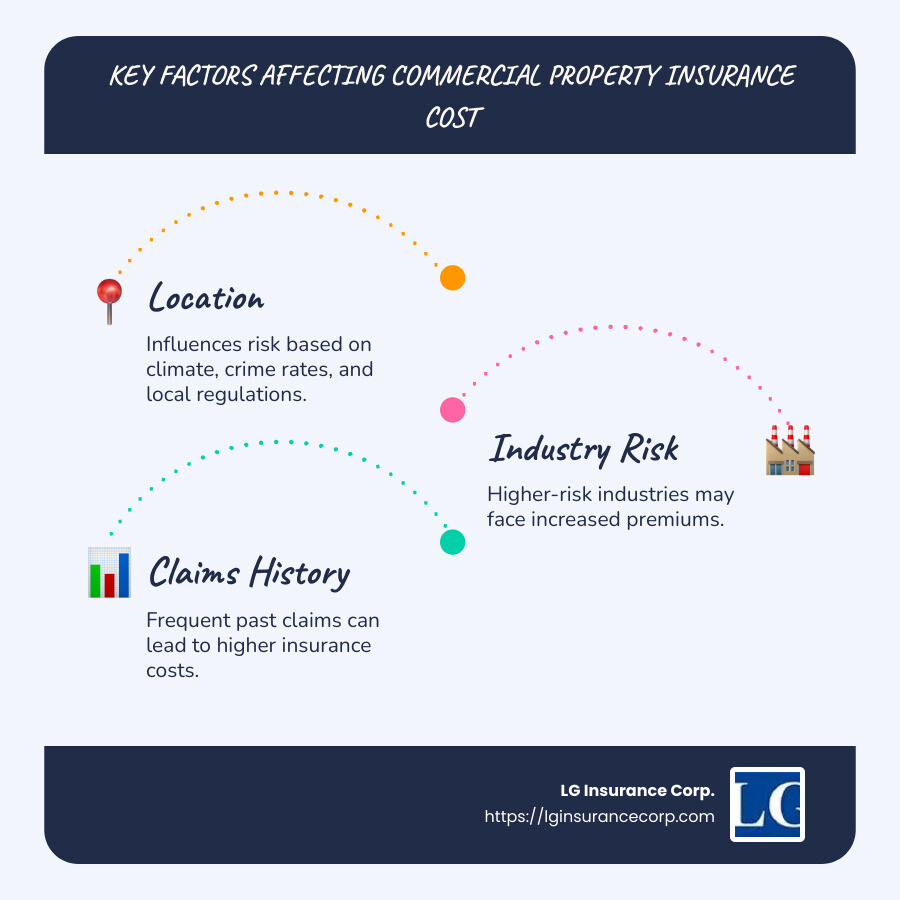
When it comes to commercial property insurance cost, several factors come into play. Understanding these can help you make informed decisions and potentially save money. Let’s break down the key elements that insurance companies consider.
1. Risk Factors
Insurance companies are all about assessing risk. The higher the risk of damage or loss to your property, the higher your insurance premium will be. For instance, businesses with high-value equipment or those located in areas prone to natural disasters will face higher costs.
2. Location
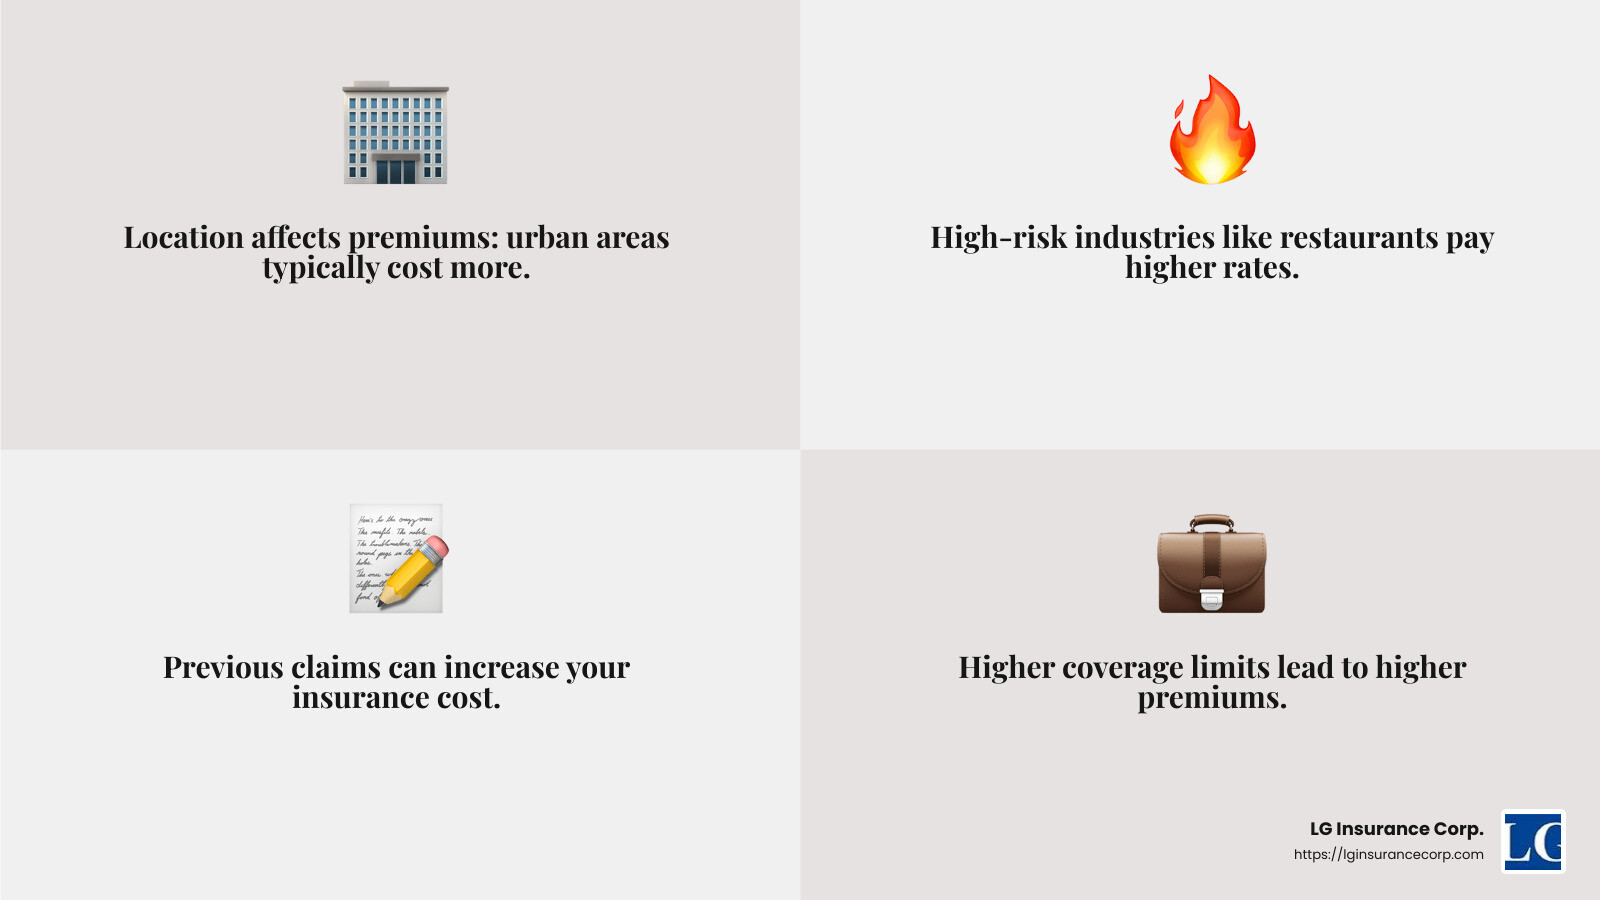
Where your business is located significantly affects your insurance cost. If you’re in a place like downtown Los Angeles, your premiums might be higher due to increased threats like natural disasters or crime. On the other hand, a business in rural Pennsylvania might enjoy lower rates due to fewer risks.
3. Industry
Not all businesses are created equal in the eyes of insurers. A florist will likely pay less than a restaurant because of the different levels of risk involved. Restaurants, with open flames and a high foot traffic, are considered riskier than a quiet office.
4. Claims History
Your past can come back to haunt you. If your business has a history of filing claims, insurers might see you as a higher risk, which could increase your premiums. For example, a bakery that had a fire incident might face higher insurance costs at renewal time.
5. Coverage Limits
The amount of coverage you choose also impacts your cost. Opting for higher limits means more protection but also results in higher premiums. It’s a balancing act—ensuring you have enough coverage without overpaying.
Understanding these factors can help you manage your commercial property insurance cost more effectively. By assessing your business’s risk profile and making strategic decisions, you can optimize your insurance coverage and keep costs in check.
Next, let’s explore how to calculate commercial property insurance rates and what you can do to potentially lower them.
How to Calculate Commercial Property Insurance Rates
Calculating commercial property insurance rates can seem complex, but breaking it down into key components makes it easier to understand. Let’s explore the main factors: building value, risk level, and premium calculation.
Building Value
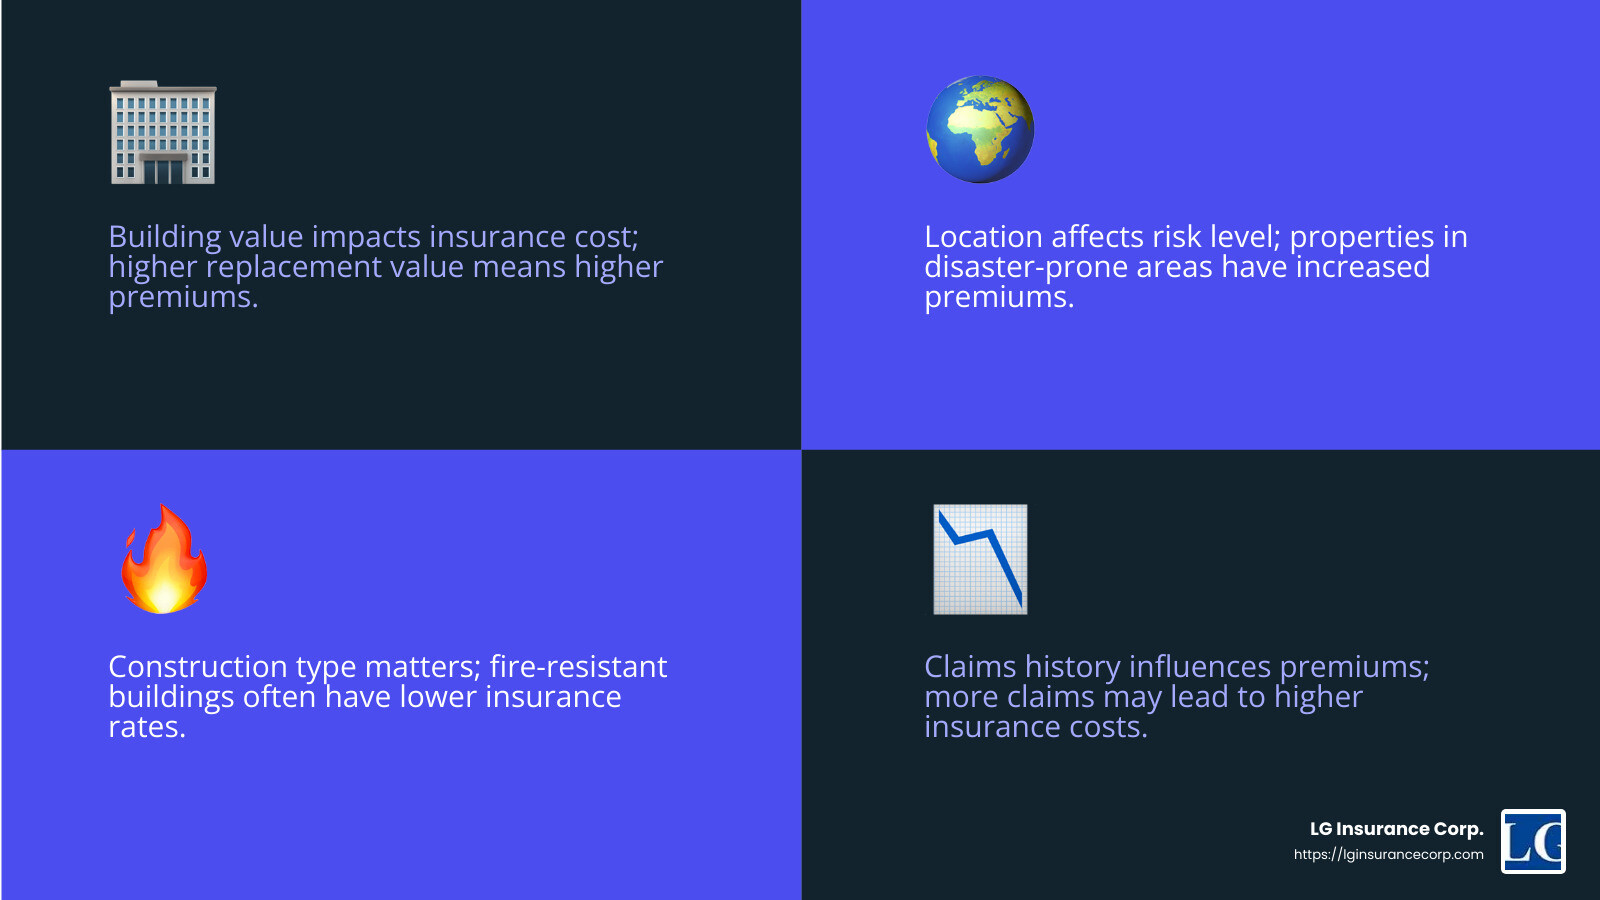
The value of your building is a major determinant of your commercial property insurance cost. Insurers look at the replacement cost of your property—what it would take to rebuild it from scratch. This includes the cost of materials, labor, and any special features your building might have.
For example, a large commercial factory with high-tech equipment will have a higher replacement cost than a small retail shop. Ensuring you have an accurate assessment of your building’s value is crucial. It ensures you’re neither underinsured nor overpaying for unnecessary coverage.
Risk Level
Risk level is all about assessing the likelihood of damage or loss. Insurance companies evaluate various risk factors, such as:
- Location: Buildings in areas prone to natural disasters or high crime rates are considered higher risk. For instance, a property near a flood zone will have higher premiums.
- Construction Type: Fire-resistant buildings may enjoy lower rates, while those made of flammable materials might incur higher costs.
- Occupancy: The use of the building also matters. An office space might have lower rates compared to a restaurant, which is considered riskier due to potential fire hazards.
Premium Calculation
Once building value and risk level are assessed, insurers calculate your premium. This involves considering:
- Coverage Limits: Higher coverage limits mean more protection but also result in higher premiums. It’s important to choose limits that adequately cover potential losses without unnecessary expense.
- Deductibles: Opting for a higher deductible can lower your premium. However, it also means you’ll pay more out of pocket before your insurance kicks in during a claim.
- Claims History: A history of frequent claims can increase your premium, as insurers may perceive your business as higher risk.
Understanding these elements helps you calculate your commercial property insurance rates more accurately. By evaluating your building value and risk level, you can make informed decisions to optimize your coverage and manage costs effectively.
Next, we’ll explore some practical tips to help you lower your commercial property insurance cost.
Tips to Lower Your Commercial Property Insurance Cost
Reducing your commercial property insurance cost is possible with a few smart strategies. Let’s explore some practical tips that can help you save money while ensuring adequate protection.
Risk Reduction
One effective way to lower your insurance costs is by reducing risks. Implementing safety measures can minimize the chance of accidents or damage, which can lead to fewer claims and lower premiums. Here are some steps you can take:
- Upgrade Security: Install security cameras, alarms, and locks to deter theft and vandalism.
- Fire Safety: Equip your property with fire extinguishers, smoke detectors, and sprinkler systems.
- Regular Maintenance: Conduct routine checks to fix potential hazards like faulty wiring or leaky roofs.
Deductible Choice
Choosing the right deductible is another way to manage your insurance costs. A higher deductible can reduce your premium. However, it also means you’ll pay more out of pocket if you need to make a claim.
- Assess Your Risk Tolerance: Consider how much you can afford to pay upfront in the event of a loss.
- Compare Deductibles: Look at the cost difference between various deductible options to find a balance that works for your budget.
Policy Bundling
Bundling multiple insurance policies can lead to significant savings. Many insurers offer discounts when you combine different types of coverage.
- Business Owners Policy (BOP): This policy often combines general liability and property insurance, offering comprehensive coverage at a reduced rate.
- Evaluate Your Needs: Determine which policies you can bundle to maximize discounts without sacrificing essential coverage.
Safety Measures
Taking proactive steps to improve safety can also help lower your insurance costs. By demonstrating a commitment to risk management, you may qualify for premium reductions.
- Employee Training: Educate your staff on safety protocols and emergency procedures.
- Hazard Mitigation: Identify and address potential hazards, such as slippery floors or unsecured shelving.
- Safety Audits: Conduct regular audits to ensure compliance with safety standards and regulations.
By implementing these strategies, you can effectively lower your commercial property insurance cost while maintaining the protection your business needs.
Next, we’ll dig into the various types of commercial property insurance coverage to help you choose the right one for your business.
Types of Commercial Property Insurance Coverage
Understanding the different types of commercial property insurance coverage is crucial for selecting the right protection for your business. Here’s a breakdown of the main options available:
Basic Form Coverage
Basic Form Coverage offers protection against the most common perils. These include fire, theft, vandalism, and certain weather events like wind or hail. It’s a straightforward option that covers essential risks but may leave gaps for certain disasters not explicitly listed.
Broad Form Coverage
Broad Form Coverage expands on the basic form by including additional risks. It covers everything in the basic form, plus hazards like water damage from plumbing issues, structural collapses, and damage from falling objects. This type offers more comprehensive protection, making it suitable for businesses with more complex risk profiles.
Special Form Coverage
Special Form Coverage is the most extensive option. Unlike the basic and broad forms, this coverage protects against all perils except those specifically excluded in the policy. It provides the highest level of protection and is ideal for businesses seeking to minimize risk exposure.
Common Exclusions
It’s important to be aware of what commercial property insurance typically does not cover. Common exclusions include:
- Flood Damage: Coverage for floods usually requires a separate policy.
- Earthquake Damage: Like floods, earthquakes often need additional insurance.
- Wear and Tear: Regular maintenance issues are not covered.
- Intentional Damage: Any damage caused intentionally by the policyholder is excluded.
Choosing the right type of coverage depends on your business needs and risk tolerance. Understanding these options will help you make an informed decision and ensure your business is protected.
In the next section, we’ll address frequently asked questions about commercial property insurance cost to further clarify any uncertainties you might have.
Frequently Asked Questions about Commercial Property Insurance Cost
How much is a $1 million commercial insurance policy?
The cost of a $1 million commercial insurance policy varies based on several factors, including your business’s location, industry, and risk profile. On average, small businesses might pay around $67 per month for commercial property insurance, but this can fluctuate. While some businesses pay less than $50, others may spend between $50 and $100 monthly. It’s essential to consider that the premium for a $1 million policy could be higher due to the increased coverage limits.
What are the two types of commercial insurance?
Commercial insurance generally falls into two main categories: property insurance and casualty insurance.
Property Insurance: This covers damage to your business’s physical assets, such as buildings, equipment, and inventory. It’s designed to protect against perils like fire, theft, and vandalism.
Casualty Insurance: Often referred to as liability insurance, this protects your business against legal claims for bodily injury or property damage caused by your business operations or employees.
Understanding these two types of insurance can help you choose the right coverage for your business needs.
Can you get general liability insurance without commercial property insurance?
Yes, you can obtain general liability insurance without purchasing commercial property insurance. However, if you want comprehensive protection, consider a Business Owner’s Policy (BOP). A BOP bundles both general liability and commercial property insurance at a more attractive price, providing a well-rounded coverage option for small businesses. While general liability insurance covers legal claims for bodily injury and property damage, a BOP ensures your business’s physical assets are also protected.
Conclusion
In today’s unpredictable world, safeguarding your business with the right insurance coverage is crucial. Commercial property insurance is not just a safety net—it’s a vital component of your business’s risk management strategy. It protects your physical assets from unexpected events like fires, theft, and natural disasters, ensuring that your business can recover and continue operations without bearing the full financial burden of such incidents.
At LG Insurance Corp., we understand the unique challenges faced by small businesses. As a family-owned agency based in Miami, FL, we pride ourselves on offering personalized, customer-centric service. Our team is committed to providing expert advice custom to your specific needs, helping you steer the complexities of commercial property insurance.
Whether you’re just starting out or looking to expand your coverage, we’re here to help. Our goal is to ensure that you have the right protection in place, allowing you to focus on what you do best—running your business.
For more information on how we can assist you with your commercial property insurance needs, visit our Business Property Insurance page.
The right coverage today can make all the difference tomorrow. Let us help you protect what matters most.