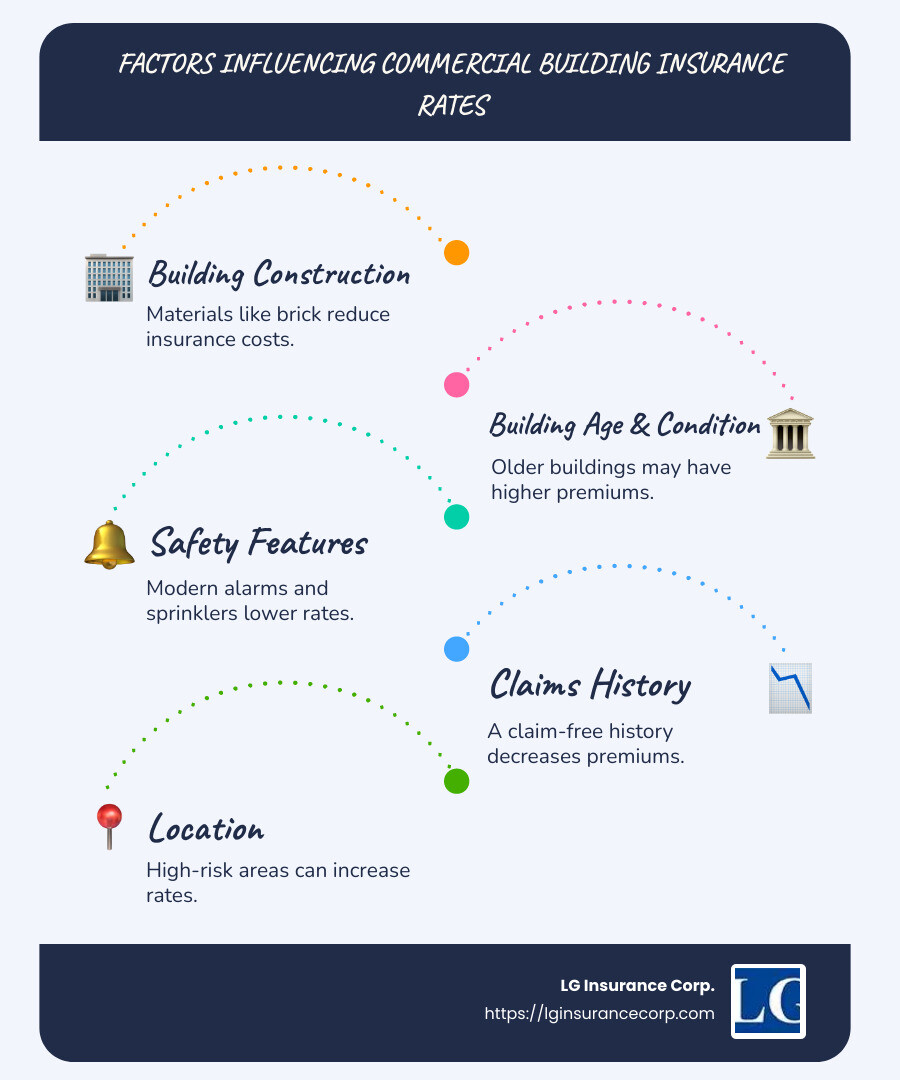
Commercial building insurance rates can seem like a complex puzzle, but understanding key factors can clear up the confusion. To grasp how rates are determined, consider these essentials:
- Building construction: Structures made primarily of flame-resistant materials, such as brick, generally cost less to insure.
- Building age and condition: Older buildings might incur higher premiums due to potential maintenance issues.
- Safety features: Buildings equipped with modern fire alarms, sprinkler systems, and security cameras tend to enjoy reduced insurance rates.
- Claims history: Having a record free from claims can significantly lower premiums.
Insurance premiums serve as the price you pay for protection against unforeseen events. They are calculated by analyzing the risk assessment of your commercial property. This assessment considers the likelihood of a claim being filed, influenced by factors like location, construction type, and safety precautions.
As the owner and founder of LG Insurance Agency, I bring over 20 years of experience in helping businesses steer commercial building insurance rates. My deep understanding of the unique needs of Miami and South Florida businesses allows me to provide expert, personalized service.
Simple guide to commercial building insurance rates:
- commercial property insurance cost
- building insurance commercial property
- who pays building insurance for commercial property
Factors Influencing Commercial Building Insurance Rates
When it comes to commercial building insurance rates, several factors play a crucial role. Let’s break down the key elements that insurers consider:
Location
The location of your business significantly impacts your insurance costs. Properties in areas prone to natural disasters, like hurricanes in Florida or wildfires in California, often face higher premiums. For example, Florida’s commercial property insurance rates are among the highest due to frequent hurricanes and flood risks.
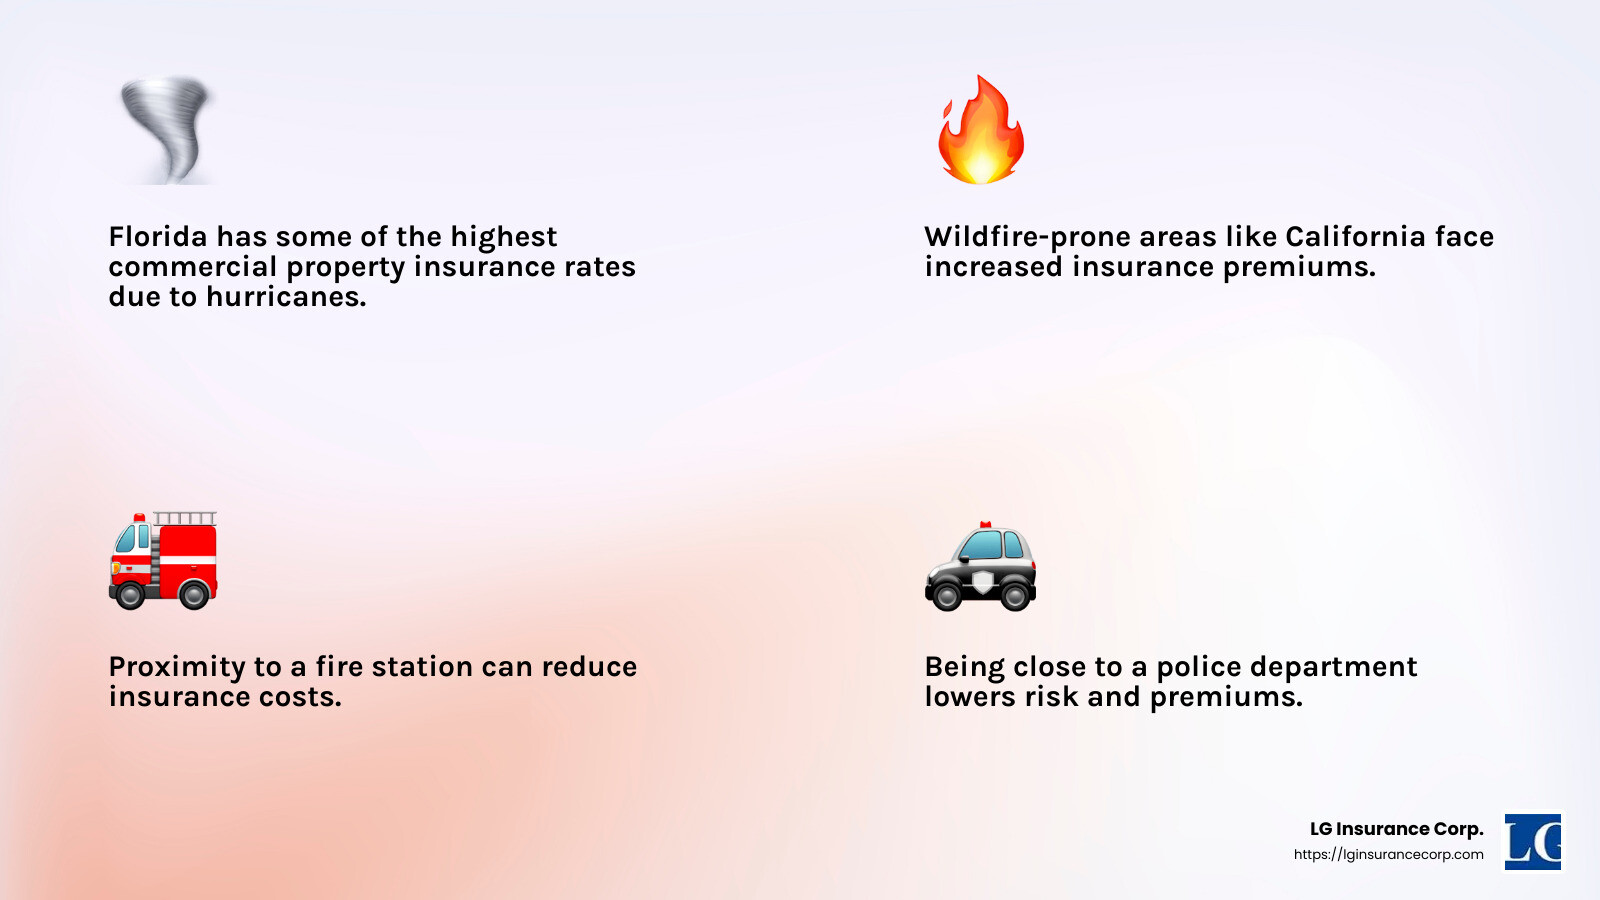
Additionally, being near a fire station or police department can lower your premiums, as these locations offer better protection and faster response times.
Industry
Different industries carry different levels of risk. For instance, a manufacturing plant with heavy machinery may have higher insurance costs compared to an office with standard equipment. Retail stores with high foot traffic might also face increased premiums due to the liftd risk of accidents or theft.
Occupancy
The number of people regularly occupying a building affects insurance rates. Buildings with high occupancy, such as hotels or retail spaces, are more likely to experience incidents, leading to higher premiums. Insurers assess both employee and customer traffic when determining rates.
Equipment
The type and value of equipment used in your business also influence insurance costs. Businesses with expensive or hazardous equipment, like construction companies, typically pay more for insurance. Conversely, offices with basic equipment like computers and printers may enjoy lower rates.
Construction
The materials used in constructing your building can impact your insurance rates. Buildings made of fire-resistant materials tend to have lower premiums compared to those made of wood, which is more flammable.
Building Age
Older buildings often come with higher insurance costs. They might have outdated electrical systems or structural issues that increase the risk of damage. Investing in renovations or maintenance can help reduce these costs.
Safety Measures
Implementing safety and security measures can significantly lower insurance premiums. Installing fire alarms, sprinkler systems, and security cameras improves the safety of your building and can lead to reduced rates. In high-crime areas, hiring security personnel might also be beneficial.
Understanding these factors can help you make informed decisions about your commercial property insurance and potentially lower your costs.
Next, let’s explore how to calculate these rates accurately.
How to Calculate Commercial Building Insurance Rates
Calculating commercial building insurance rates involves a few key components. Let’s explore what insurers typically consider:
Property Value
The first step in calculating insurance rates is determining the property value. This includes the building itself and any permanent fixtures. Insurers assess your property’s worth to decide how much coverage you’ll need. A higher property value usually means higher premiums, as there’s more to protect.
Risk Level
Insurers evaluate the risk level of your property. This involves looking at various factors like location, industry, and safety measures. For instance, if your building is in a hurricane-prone area like South Florida, the risk level—and consequently, the insurance cost—will be higher. Similarly, industries with higher accident or theft risks, like manufacturing or retail, might face increased rates.
Replacement Cost
Another critical factor is the replacement cost. This is what it would cost to rebuild your property from scratch, using current labor and material prices. According to recent data, nonresidential construction costs have risen significantly, with structural steel prices up by 65% and concrete products by 37% over the past four years. These increases directly impact insurance rates since higher replacement costs mean higher premiums.
Depreciation
Depreciation accounts for the reduction in your property’s value over time. Insurers use this to determine the actual cash value of your building. Older properties may have depreciated significantly, which can affect coverage amounts and premiums. However, opting for a replacement value policy instead of an actual cash value policy can ensure that you receive enough funds to rebuild your property as new, though it usually comes with higher premiums.
By understanding these factors, you can better anticipate your insurance costs and make strategic decisions to manage them. Next, we’ll discuss the average cost of commercial building insurance for different business sizes and locations.
Average Cost of Commercial Building Insurance
When it comes to commercial building insurance rates, costs can vary widely based on several factors, including the size of your business and its location. Let’s break it down:
Small Businesses
For small businesses, commercial building insurance typically ranges from $1,000 to $3,000 annually. This translates to about $83 to $250 per month. Small businesses often have less property and fewer assets to insure, which helps keep costs lower. However, factors like industry type and location can still significantly impact these rates. For example, a small retail store in a low-risk area will likely pay less than a similar store in a high-risk zone.
Large Businesses
Large businesses generally face higher insurance premiums. This is because they have more assets, larger facilities, and potentially more complex operations to cover. The cost can be double or even triple that of small businesses. For instance, a large manufacturing plant with extensive equipment and storage might see annual premiums exceeding $6,000. The increased risk and potential for larger claims drive these higher costs.
High-Risk Areas
Location plays a crucial role in determining commercial building insurance rates. Businesses located in high-risk areas, such as those prone to natural disasters like hurricanes or wildfires, often face higher premiums. For example, businesses in Florida or California might pay significantly more due to the increased likelihood of weather-related damage. Insurers account for these risks by raising premiums to cover potential claims.
Low-Risk Areas
Conversely, businesses in low-risk areas can benefit from lower insurance costs. These are locations with minimal exposure to natural disasters or crime. A business in a quiet suburban area with excellent fire protection and low crime rates could enjoy more affordable premiums. Insurers reward these safer locations with reduced rates, making it financially advantageous to operate in such areas.
Understanding these factors can help you better anticipate and manage your commercial building insurance rates. Next, we’ll explore strategies to reduce these costs effectively.
How to Reduce Commercial Building Insurance Costs
Reducing your commercial building insurance costs doesn’t have to be complicated. By making strategic changes and understanding your policy options, you can save money while maintaining adequate coverage. Here are some effective strategies:
Safety Upgrades
Enhancing your property’s safety can lead to lower premiums. Consider installing:
- Security Systems: Cameras and alarms deter theft and vandalism.
- Fire Safety: Sprinklers, smoke detectors, and fire-resistant materials can reduce fire risks.
These upgrades not only protect your property but can also convince insurers to offer you better rates. As the research suggests, insurers reward proactive risk reduction.
Accurate Valuations
Ensure that your property’s valuation is up-to-date. Overestimating or underestimating can affect your premiums:
- Overvaluation: Leads to higher premiums than necessary.
- Undervaluation: Could result in insufficient coverage during a claim.
Regularly review and update your valuations. If you’ve made improvements or renovations, inform your insurer. Accurate details can help you avoid paying too much or being underinsured.
Policy Bundling
Bundling policies can lead to significant savings. Consider combining different types of insurance, such as:
- General Liability
- Commercial Property
- Business Interruption
When you bundle, insurers often offer discounts. This approach is particularly beneficial for small businesses, as it simplifies management and reduces costs.
Business Owners Policy (BOP)
A Business Owners Policy (BOP) is a great option for many businesses. It combines essential coverages into one package:
- General Liability
- Property Insurance
- Business Interruption
A BOP is typically cheaper than purchasing each policy separately. It’s an efficient way to get comprehensive coverage at a reduced rate, especially if your business isn’t classified as high-risk.
By implementing these strategies, you can effectively manage and reduce your commercial building insurance costs. Understanding and applying these methods will help you maintain necessary coverage without overspending.
Frequently Asked Questions about Commercial Building Insurance Rates
How to Calculate Commercial Property Insurance Rate?
Calculating your commercial property insurance rate involves several factors. The most significant is the value of your building. Insurers assess how much it would cost to rebuild or repair your property. This means your insurance rate is closely tied to the replacement cost of your building, not just its market value.
Risk correlation plays a crucial role too. If your building is in a high-risk area—like Miami, FL, which is prone to hurricanes—expect higher rates. Insurers evaluate risks like natural disasters, crime rates, and even the age and construction materials of your building. Older buildings or those made with flammable materials often face higher premiums.
What is the Average Cost for Commercial Insurance?
The average cost of commercial insurance varies widely. For small businesses, typical costs range from $1,000 to $3,000 annually. This includes coverage like general liability and business owners policy (BOP), which bundles essential coverages for a better rate.
For larger businesses or those in high-risk industries, costs can be significantly higher. Factors like the size of your property, the industry you operate in, and specific risks you face all influence your premiums.
How Much is a $1 Million Dollar Insurance Policy for a Business?
A $1 million dollar insurance policy can vary in cost, depending on the type of coverage. For liability insurance, which protects against claims of injury or damage, businesses might pay anywhere from $300 to $1,000 annually. However, this varies greatly based on your business’s risk profile.
Cost variation is common. Factors like your claims history, industry risks, and even your safety measures can alter your premiums. For instance, a business with a clean claims record and robust safety protocols might pay less than a similar business with frequent claims.
Understanding these components can help you better steer and manage your commercial building insurance rates. This knowledge is crucial for making informed decisions and ensuring you get the best coverage for your needs.
Conclusion
Navigating commercial building insurance can be daunting, but you don’t have to do it alone. At LG Insurance Corp., we’re here to provide expert advice and support custom to your unique needs.
Why Choose LG Insurance Corp.?
We are a family-owned agency based in Miami, FL, with a deep commitment to our community. Our team understands the local challenges, such as the high-risk of hurricanes, and we’re ready to help you find the right coverage to protect your business. We pride ourselves on offering comprehensive insurance solutions that are both effective and affordable.
Expert Advice You Can Trust
Our team of experienced advisors is dedicated to helping you understand and manage your commercial building insurance rates. We take the time to assess your specific situation, ensuring your policy covers all potential risks without unnecessary extras. Whether you’re a small business or a large enterprise, we have the expertise to guide you through the insurance process.
Community Support
Being part of the South Florida community is important to us. We believe in supporting local businesses and helping them thrive. Our customer-centric approach means we’re always here to answer your questions and provide the support you need, when you need it.
For more information on how we can help protect your business property, visit our Business Property Insurance page. Let’s work together to keep your business safe and secure.