Business interruption insurance Miami is a crucial safeguard for businesses facing unexpected disruptions in their operations. In the busy economic hub of Miami, companies can face numerous challenges ranging from hurricanes, fires, or other unforeseen incidents that temporarily halt business activities. To address these challenges, business interruption insurance can provide financial relief by covering lost income, fixed costs, and expenses related to temporary relocation or recovery.
Understanding the importance of this insurance is essential for Miami business owners seeking stability amid uncertainty:
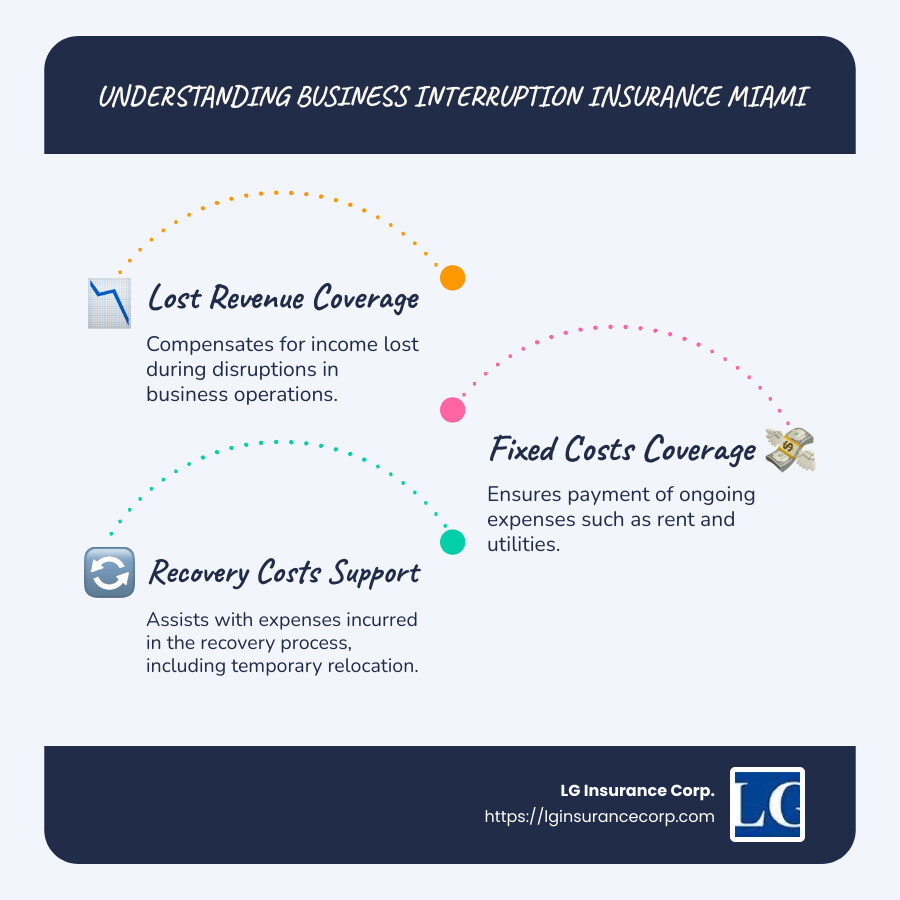
- Lost Revenue Coverage: Compensates for income lost during disruptions.
- Fixed Costs Coverage: Ensures payment of ongoing expenses like rent and utilities.
- Temporary Relocation: Covers costs to set up a temporary business location.
- Recovery Costs: Assists with expenses incurred in the recovery process.
My name is Leonard Garcia, and I am the owner of LG Insurance Agency in Miami, where I leverage over two decades of experience in providing custom insurance solutions. My expertise in business interruption insurance Miami ensures clients receive coverage suited to their unique needs, helping them steer these complex waters with confidence.
Relevant articles related to Business interruption insurance Miami:
– Miami business insurance
– Miami general liability insurance
– business insurance claims miami fl
Understanding Business Interruption Insurance
Business interruption insurance is a lifeline for many companies in Miami, offering crucial protection when unexpected events disrupt normal operations. Let’s break down what this insurance covers and how it can help your business stay afloat during tough times.
Coverage Details
Business interruption insurance, often called business income insurance, is designed to cover the loss of income that a business suffers after a disaster. This insurance kicks in when a covered event, such as a fire or hurricane, causes physical damage that forces your business to close temporarily.
Lost Income
One of the main components of this insurance is lost revenue coverage. It compensates businesses for the income they would have earned if the disruption hadn’t occurred. This is essential for maintaining cash flow and ensuring that your business can continue to operate once the crisis is over.
Fixed Costs
Even when your business is not running, bills keep coming. Fixed costs coverage helps pay for ongoing expenses like rent, utilities, and salaries. This ensures that you can keep your commitments and avoid falling into debt, even when your revenue stream is temporarily halted.
Temporary Relocation
Sometimes, a business needs to move to a new location temporarily. Temporary relocation coverage helps cover the costs of setting up a new site, including rent and moving expenses. This allows you to continue serving your customers with minimal disruption.
Recovery Costs
After a disaster, getting back to normal can be costly. Recovery costs coverage helps with expenses like purchasing new equipment or training staff on new processes. This support is vital for a smooth and swift recovery, enabling your business to return to full operation as soon as possible.
In summary, understanding the components of business interruption insurance is crucial for Miami businesses. By providing coverage for lost income, fixed costs, temporary relocation, and recovery costs, this insurance ensures that companies can weather the storm and emerge stronger on the other side.
Business Interruption Insurance Miami: Key Considerations
When securing Business Interruption Insurance Miami, there are several critical factors to consider to ensure your coverage is both comprehensive and suitable for your business needs.
Coverage Limits
Coverage limits are the maximum amount your insurance will pay for a covered loss. It’s essential to assess your business’s potential risks and choose a limit that reflects your needs. Consider factors like the size of your business, typical revenue, and the cost of maintaining operations during a shutdown. A well-chosen coverage limit can mean the difference between a temporary setback and a financial catastrophe.
Policy Terms
Policy terms outline what is and isn’t covered, as well as the conditions required for a claim. For example, some policies may only cover interruptions caused by specific events like fires or hurricanes. It’s crucial to understand these terms and ensure they align with the risks your business faces in Miami. Reviewing policy terms with a knowledgeable insurance advisor can help you avoid surprises when you need coverage the most.
Financial Records
Accurate financial records are vital for calculating business interruption losses and filing claims. Insurers typically require detailed documentation of your business’s income, expenses, and profits. Keeping thorough and up-to-date records can streamline the claims process, helping you receive compensation more quickly. Consider implementing a reliable accounting system to manage these records efficiently.
Waiting Period
The waiting period is the time between when a business interruption occurs and when your insurance coverage kicks in. This period can vary depending on your policy and is often a critical factor in how soon you can receive financial support. Understanding the waiting period in your policy can help you plan for temporary cash flow needs during this initial phase of disruption.
By considering these key elements—coverage limits, policy terms, financial records, and waiting periods—Miami businesses can make informed decisions about their Business Interruption Insurance Miami policies. This ensures they are prepared for the unexpected and can recover swiftly from interruptions.
Common Causes of Business Interruptions
Business interruptions can happen when you least expect them. Knowing the common causes can help you prepare and minimize downtime. Let’s explore some of the usual suspects:
Fire and Explosion
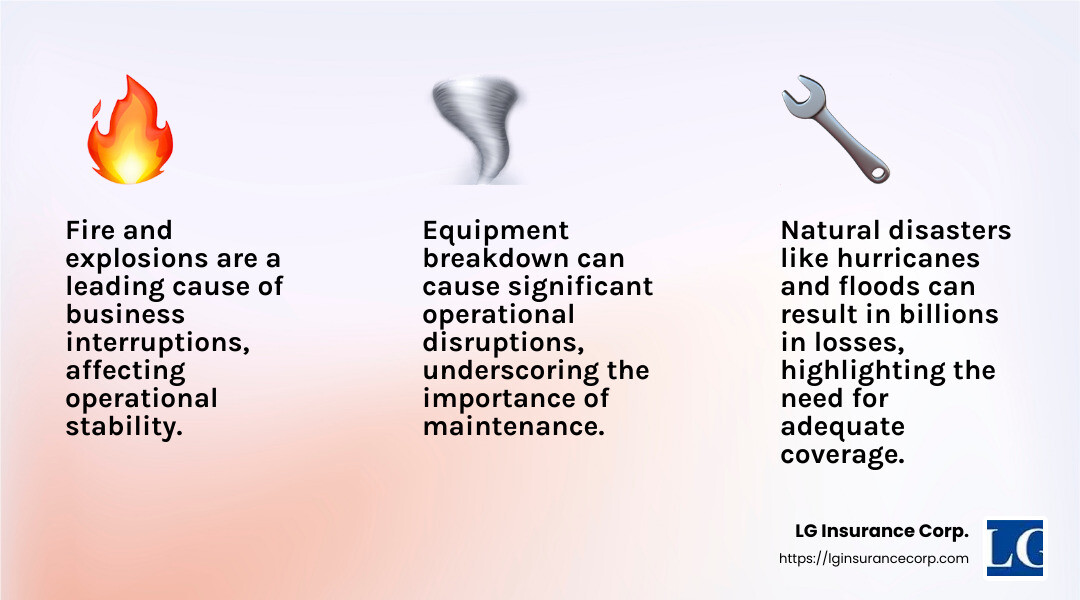
Fires and explosions can cause severe damage, leading to prolonged business closures. Whether it’s due to faulty wiring or a kitchen mishap, the aftermath can be devastating. Business interruption insurance can cover lost income and help with repair costs, allowing you to focus on rebuilding.
Natural Disasters
Miami is no stranger to hurricanes and floods. These natural disasters can wipe out entire businesses overnight. In fact, after Hurricane Ian, insurers reported around $56 billion in losses. Having the right coverage can help you bounce back from such events. It can cover everything from lost revenue to temporary relocation expenses.
Equipment Breakdown
Even minor equipment failures can halt operations. Imagine a bakery without ovens or a tech firm without servers. Equipment breakdown coverage can help you with repair or replacement costs. It ensures that your business can resume operations quickly without a massive financial hit.
Theft
Theft can disrupt your business, leading to unexpected expenses and lost income. While commercial property insurance may cover the physical loss, business interruption insurance can compensate for the downtime and lost sales while you recover.
By understanding these common causes, you can better prepare your business. Make sure your Business Interruption Insurance Miami policy covers these scenarios to protect your livelihood.
Calculating Business Interruption Losses
When your business faces an unexpected halt, understanding how to calculate losses is crucial. Business Interruption Insurance Miami can cover these losses, but knowing the specifics helps you get the most out of your policy.
Projected Sales vs. Actual Sales
Start by comparing what you expected to earn (projected sales) with what you actually earned (actual sales) during the interruption period. This difference highlights your lost revenue. For example, if a bakery forecasted $10,000 in sales but only made $2,000 due to a fire, then the lost revenue is $8,000.
Saved Expenses
Not all costs continue during a business interruption. Identify expenses that you didn’t incur, like utility bills or reduced inventory costs. These are your saved expenses. Subtracting these from your total loss gives a clearer picture of the financial impact. For instance, if the bakery saved $1,000 on electricity and supplies, you would adjust the loss to $7,000.
Financial Analysis
Conducting a thorough financial analysis helps in accurately calculating your claim. This involves examining your financial records and understanding your business’s financial health before and after the interruption. It’s essential for proving the extent of your losses to your insurer.
A detailed financial analysis can also help in identifying trends and patterns, aiding in future risk management.
By understanding these components, you can better steer the claims process and ensure that your business interruption insurance effectively supports your recovery.
Frequently Asked Questions about Business Interruption Insurance
What does business interruption insurance cost?
The cost of business interruption insurance varies widely. It depends on several factors, such as the size of your business, the industry you’re in, and the specific risks you face. For small businesses, the premiums are generally lower, but if you’re in a high-risk industry, like construction or hospitality, expect to pay more. The reason is simple: higher risk means higher chances of interruptions.
Insurance companies will assess your business’s unique situation to determine the premium. They consider factors like location, annual revenue, and existing safety measures. It’s crucial to shop around and get quotes from multiple providers to find a policy that fits your budget and needs.
Does business insurance cover break-ins?
Yes, business insurance can cover break-ins, but it depends on your policy. Commercial property coverage often includes protection against theft and vandalism. However, there are exclusions to be aware of. Some policies might not cover certain types of theft, like employee theft, unless you have specific endorsements.
To ensure you’re covered, review your policy’s terms and conditions carefully. If theft exclusions are present, consider additional coverage options to protect against these risks. It’s better to address these gaps upfront rather than face unexpected expenses after a break-in.
How is business interruption insurance calculated?
Calculating business interruption insurance involves several steps. The primary focus is on loss revenue. First, compare your projected sales with your actual sales during the interruption. The difference gives you the lost revenue.
Next, account for saved expenses—costs you didn’t incur due to the interruption. Subtract these from your lost revenue to refine the loss amount. This might include reduced utility bills or halted supply orders.
Finally, perform a detailed financial analysis. This involves a deep dive into your financial records to substantiate your claim. Insurers will use this data to assess the validity and extent of your losses. A well-documented analysis ensures you receive fair compensation and helps in future risk assessments.
By understanding these elements, you can better prepare for potential interruptions and ensure your business interruption insurance Miami policy provides the necessary support.
Conclusion
At LG Insurance Corp., we understand that navigating business insurance can be daunting. That’s why we are committed to providing customer-centric service that focuses on your unique needs and challenges. Our team of dedicated professionals in Miami and South Florida is here to offer expert advice custom to protect your business from unexpected disruptions.
We believe in supporting our community and helping local businesses thrive, even in the face of adversity. Our comprehensive business insurance solutions, including business interruption insurance Miami, are designed to safeguard your operations and give you peace of mind. Whether you’re recovering from a natural disaster or dealing with other business interruptions, we’re here to ensure you have the coverage you need.
Explore our business insurance solutions to learn more about how we can help protect your business. Together, we can build a resilient future for your company and our community.