Building insurance commercial property is a critical safeguard for businesses, offering protection against unexpected events like fire, theft, and vandalism. This insurance covers the physical assets of a business, from buildings to equipment and inventory, ensuring continuity in the event of damage or loss.
Key aspects include:
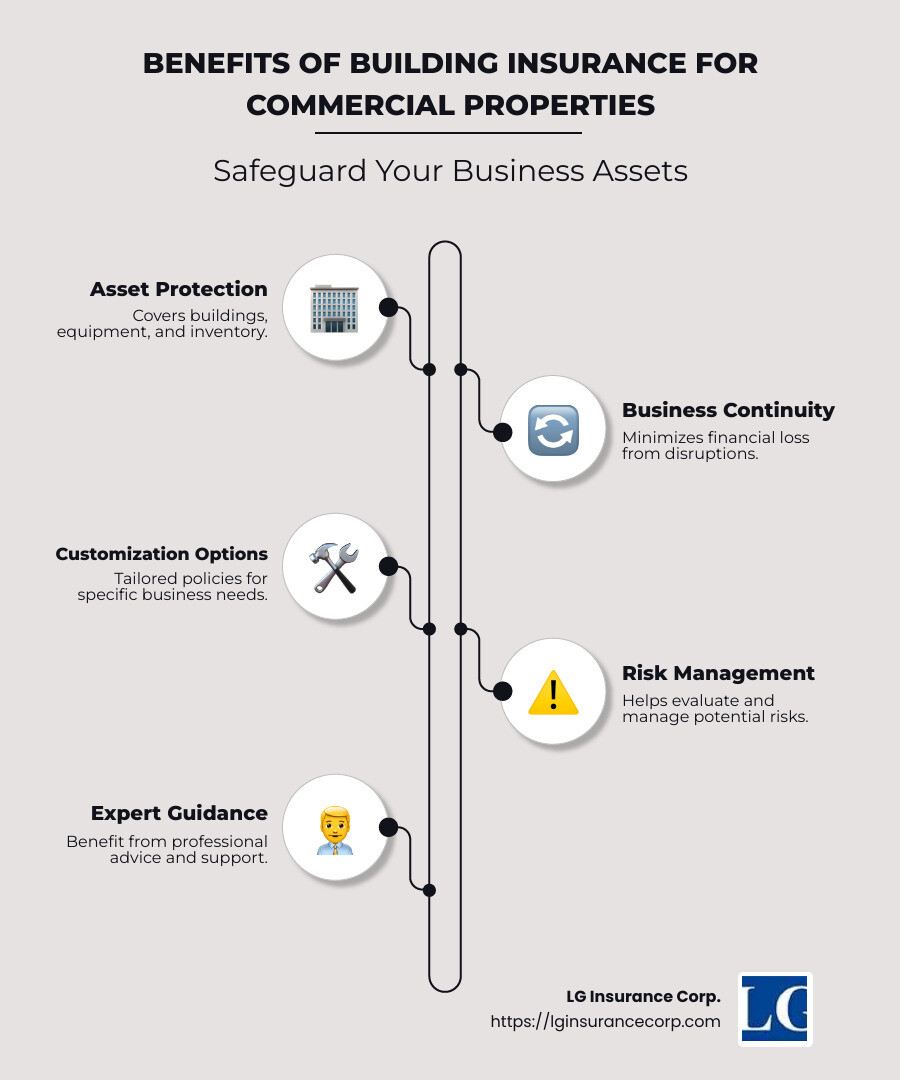
- Protection of physical assets: Covers buildings, equipment, and inventory against various risks.
- Business continuity: Minimizes financial loss due to business disruptions.
- Customization options: Tailor policies to fit business-specific needs, including optional coverages.
Understanding these elements ensures businesses can continue operations smoothly, even when disasters strike.
I’m Leonard Garcia, the owner and founder of LG Insurance Agency. With over 20 years of experience, I specialize in navigating the complexities of building insurance commercial property to protect your business assets effectively. Let’s dig deeper into how you can secure your commercial property.
Building insurance commercial property further reading:
– who pays building insurance for commercial property
– commercial property insurance cost
– commercial property insurance online quote
Understanding Commercial Property Insurance
Commercial property insurance is essential for safeguarding your business’s physical assets. This type of insurance provides coverage against various risks and helps ensure that your business can recover from unexpected events. Let’s break down the key components of this insurance.
Coverage Types
When it comes to commercial property insurance, there are two primary coverage types:
Replacement Cost: This coverage reimburses you for the cost of replacing damaged or destroyed property with new items of similar kind and quality. It’s ideal for businesses that rely heavily on up-to-date equipment.
Actual Cash Value: This option provides compensation based on the current market value of the property, minus depreciation. While it has lower premiums, you may have to pay out-of-pocket to replace older items.
Perils Covered
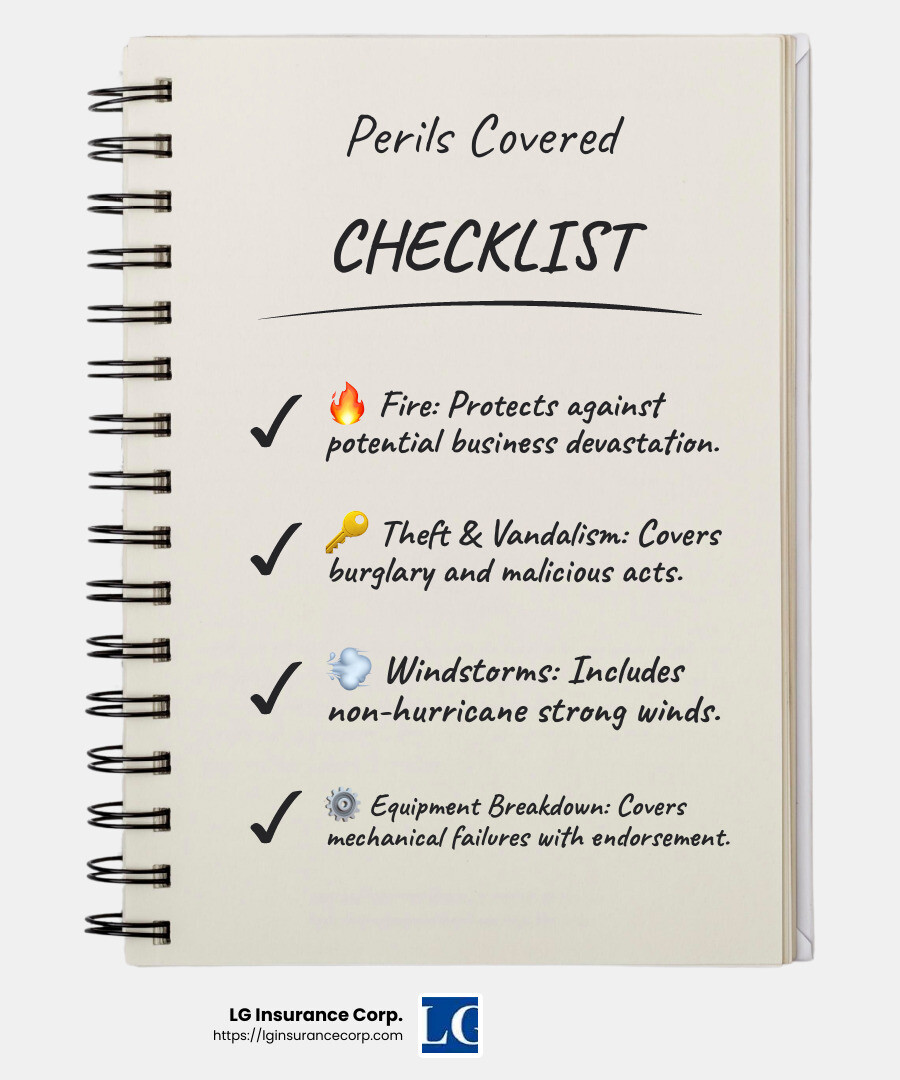
Commercial property insurance typically covers a range of named perils. These include:
- Fire: Protection against damage from fires, which can devastate a business.
- Theft and Vandalism: Coverage for losses due to burglary or malicious acts.
- Windstorms: Includes damage from strong winds, though not always hurricanes.
- Equipment Breakdown: With an endorsement, this covers mechanical failures or electrical surges.
Exclusions
It’s crucial to understand what commercial property insurance does not cover. Common exclusions include:
Natural Disasters: Events like earthquakes, floods, and hurricanes are typically not covered. You may need separate policies or endorsements for these.
Wear and Tear: Normal deterioration of property over time is not covered.
Business Vehicles: These require separate commercial auto insurance policies.
By understanding the coverage types, perils covered, and exclusions, you can better assess your business’s needs and ensure you have the right protection in place. This knowledge is vital for minimizing financial risks and ensuring the continuity of your operations.
Next, we’ll explore how to evaluate your business assets to determine the appropriate level of coverage you need.
Building Insurance for Commercial Property
When you’re insuring a commercial building, it’s important to understand the different ways your property can be valued. This affects how much you’ll receive if you need to make a claim. Let’s explore replacement cost, actual cash value, and how these impact your policy choices.
Replacement Cost vs. Actual Cash Value
Replacement Cost (RC): This is what it would cost to repair, replace, or rebuild your property with similar materials and quality at today’s prices, without deducting for depreciation. It’s like hitting a “reset” button on your damaged property. This type of coverage is typically more expensive but ensures you can fully restore your property without extra financial strain.
Actual Cash Value (ACV): This pays out the replacement cost minus depreciation. So, if your property is older, the payout might be less than what you need to replace it with new items. ACV tends to have lower premiums, which can be attractive if you’re looking to save on insurance costs. However, be prepared for potential out-of-pocket expenses.
Policy Variations
Insurance policies aren’t one-size-fits-all. They can vary widely based on factors like location, building use, and the specific risks your business might face. For instance, a business located in Miami, FL, might consider additional coverage for hurricanes, which are not typically included in standard policies.
Consider these variations when customizing your building insurance for commercial property:
Endorsements: These are add-ons to your policy that provide extra coverage for specific risks, like equipment breakdown or business interruption.
Optional Coverages: Depending on your business needs, you might add protection against risks not covered by standard policies, such as flood insurance or terrorism coverage.
Policy Limits and Deductibles: Higher policy limits offer more coverage but come with higher premiums. Choosing a higher deductible can lower your premium, but you’ll pay more out-of-pocket if you make a claim.
Understanding these aspects helps you tailor your insurance policy to best fit your business needs and budget. It ensures that your business is not only protected but can also bounce back quickly from unexpected events.
Next, we’ll dig into evaluating your business assets to ensure you’re adequately covered.
Evaluating Your Business Assets
Before you can effectively insure your commercial property, you need to understand what you’re insuring. This means creating a detailed asset inventory, conducting a risk assessment, and calculating replacement costs.
Asset Inventory
Start by listing everything your business owns. This includes buildings, furniture, equipment, and inventory. Don’t forget outdoor items like signs and fences. An accurate inventory helps you determine the right amount of coverage.
Use a simple table to organize your assets:
| Asset Type | Description | Estimated Value |
|---|---|---|
| Building | Office space, storage | $500,000 |
| Equipment | Computers, printers | $50,000 |
| Inventory | Retail goods, supplies | $200,000 |
| Outdoor Items | Signage, fencing | $10,000 |
Keep this list updated, especially when you purchase new items or dispose of old ones. This ensures your insurance matches your current needs.
Risk Assessment
Next, evaluate the risks your business faces. Consider natural disasters, theft, and vandalism. For example, a business in South Florida should consider the risk of hurricanes.
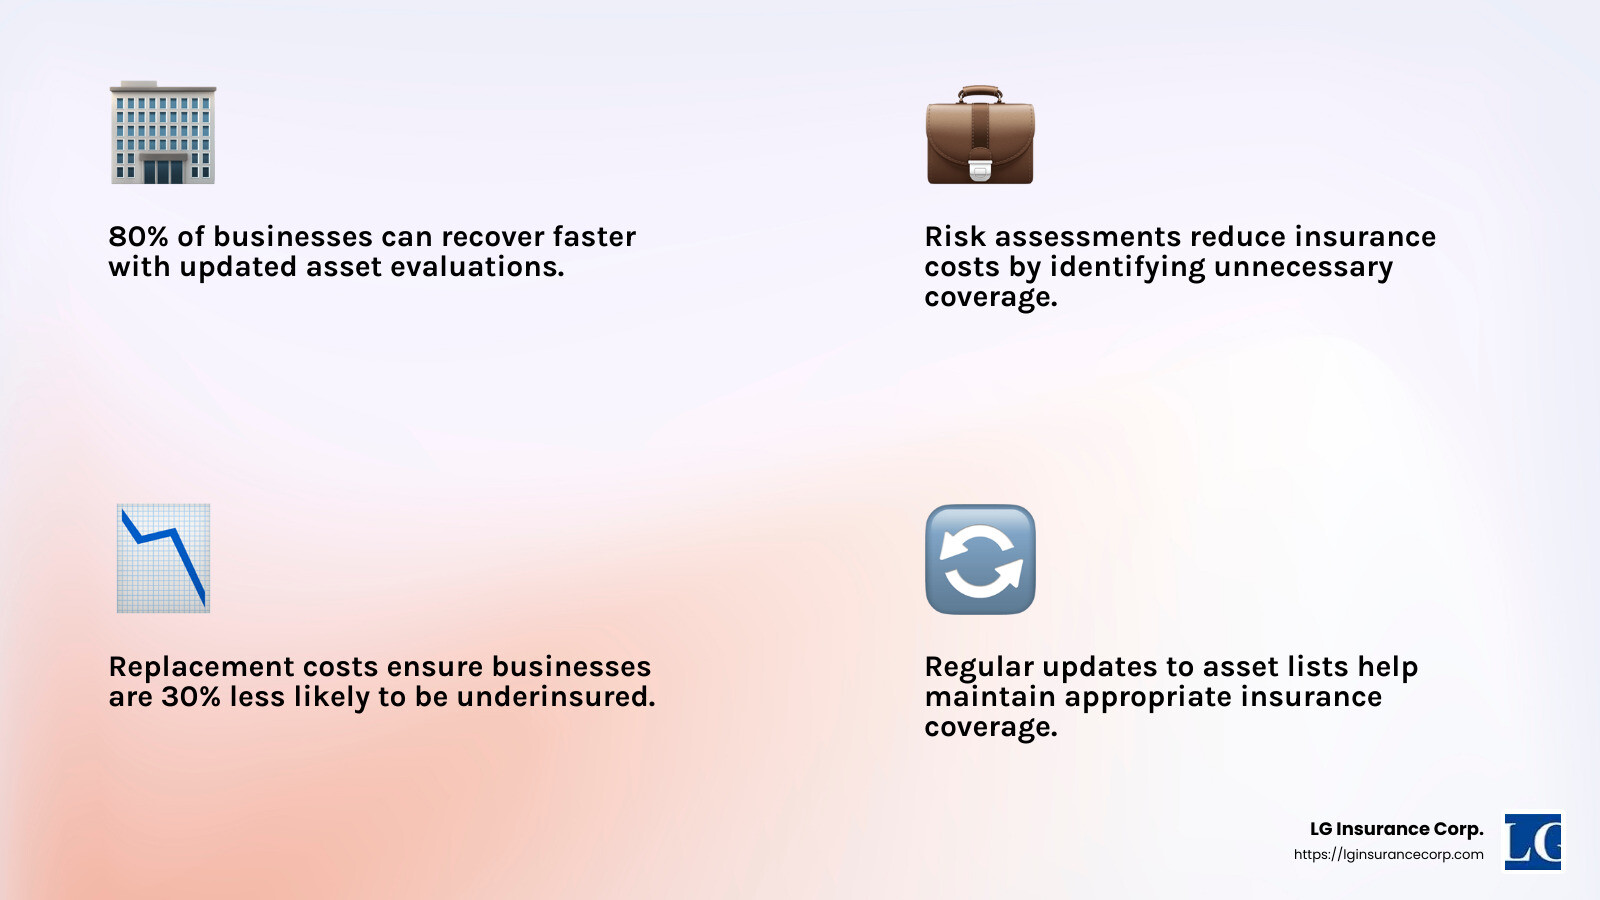
Assessing your risk helps you choose the right coverage. It also highlights areas where you might need additional protection, like flood insurance.
Replacement Costs
Understanding replacement costs is crucial. This is the amount needed to rebuild or replace your assets at current prices. It’s different from actual cash value, which subtracts depreciation.
To calculate replacement costs:
- Research current market prices for similar items.
- Factor in any improvements or upgrades.
- Consider inflation and market trends.
Having accurate replacement costs ensures you’re not underinsured. It also helps you avoid out-of-pocket expenses if you need to make a claim.
By thoroughly evaluating your business assets, you can better tailor your building insurance commercial property to fit your needs. This proactive approach not only safeguards your business but also provides peace of mind.
Now, let’s explore how you can customize your insurance policy to match your unique business requirements.
Customizing Your Insurance Policy
Every business is unique, and so are its insurance needs. Customizing your policy ensures you get the right coverage for your specific situation. This involves adding endorsements, considering optional coverages, and aligning with your business needs.
Endorsements
Endorsements, also known as riders, are additions to your insurance policy that provide extra coverage or modify the terms. They help fill gaps in standard coverage. For instance:
- Equipment Breakdown Endorsement: Protects against damage from power surges or mechanical failures.
- Flood or Earthquake Endorsement: Important for businesses in areas prone to these natural disasters.
By adding endorsements, you can tailor your policy to cover specific risks that are not typically included in standard commercial property insurance.
Optional Coverages
Beyond endorsements, there are optional coverages that can further protect your business. Consider these based on your industry and location:
- Business Interruption Insurance: Covers lost income if your business is temporarily closed due to a covered event, like a fire.
- Inland Marine Insurance: Protects property in transit or stored off-site. Useful for businesses with mobile equipment or goods.
- Cyber Liability Insurance: Essential for businesses that handle sensitive data. It covers costs related to data breaches and cyber attacks.
Discuss these options with your insurance provider to determine which ones are necessary for your business.
Business Needs
Assessing your business needs is key to customizing your policy. Consider the following:
- Industry Risks: Different industries have unique risks. For example, a restaurant might need coverage for kitchen equipment, while a tech company may prioritize data protection.
- Location-Specific Risks: Businesses in Miami, FL, should consider hurricane-related risks and ensure their policy addresses these.
- Asset Value: Ensure your coverage aligns with the value of your assets. This prevents underinsurance and unexpected out-of-pocket costs.
By focusing on your specific business needs, you can create a comprehensive insurance package that offers robust protection.
Customizing your policy might seem complex, but it’s essential for effective protection. Working with an experienced insurance advisor can simplify this process and ensure you’re covered where it counts.
Next, we’ll answer some frequently asked questions about commercial property insurance to help you make informed decisions.
Frequently Asked Questions about Commercial Property Insurance
What does insurance cover for commercial buildings?
Commercial property insurance is designed to protect your business from unexpected events. It typically covers damages from fire, theft, and vandalism. However, there are some exclusions to be aware of. For example, natural disasters like earthquakes and floods generally require additional endorsements.
- Fire: A common risk, especially in areas with older buildings or limited fire protection. Insurance can cover the cost of repairs or rebuilding.
- Theft: This includes stolen inventory or equipment. Having a robust security system might reduce your premium.
- Vandalism: Covers damage caused by malicious acts, such as graffiti or broken windows.
It’s important to understand these coverages and discuss any specific concerns with your insurance provider to ensure you’re fully protected.
How much does commercial property insurance cost?
The cost of commercial property insurance varies widely. Several factors influence the premium:
- Location: Properties in areas with high crime rates or extreme weather conditions, like Miami, FL, may have higher premiums.
- Building Construction: Newer or fire-resistant buildings often cost less to insure.
- Business Type: High-risk businesses, like restaurants, may pay more due to increased risks.
On average, small businesses might pay between $300 and $1,000 annually for their insurance coverage. However, this can change based on the specifics of your business and location.
Who needs commercial property insurance?
Most small businesses would benefit from having commercial property insurance. This is especially true for professions that rely heavily on physical assets, such as:
- Retailers: Protects against inventory loss.
- Contractors: Covers expensive equipment and materials.
- Restaurants: Safeguards kitchen equipment and furnishings.
Even if you rent your space, insurance can protect your assets and provide peace of mind. It’s a crucial part of asset protection, helping businesses recover from incidents that could otherwise lead to significant financial losses.
By understanding these aspects, you can make informed decisions about your commercial property insurance needs. In the next section, we’ll conclude with how LG Insurance Corp. can offer customer-centric service and expert advice to help protect your business.
Conclusion
At LG Insurance Corp., we understand that each business is unique and requires personalized insurance solutions. Our family-owned agency in Miami, FL, is dedicated to providing customer-centric service and expert advice custom to meet your specific needs.
We know that navigating commercial property insurance can be complex. That’s why our team is here to simplify the process for you. We take the time to assess your business, identify potential risks, and offer solutions that make sense for your operations. Whether you’re concerned about protecting your building, equipment, or inventory, we’ve got you covered.
Our commitment to community support means we’re not just here to sell insurance; we’re here to build lasting relationships. We believe in being a trusted partner for businesses across South Florida, helping them safeguard their assets and ensure continued success.
If you’re ready to explore your options or have any questions, we’re just a call away. Let us help you protect what you’ve worked so hard to build.
For more information about our services, visit our Business Property Insurance page. We’re here to help you every step of the way.