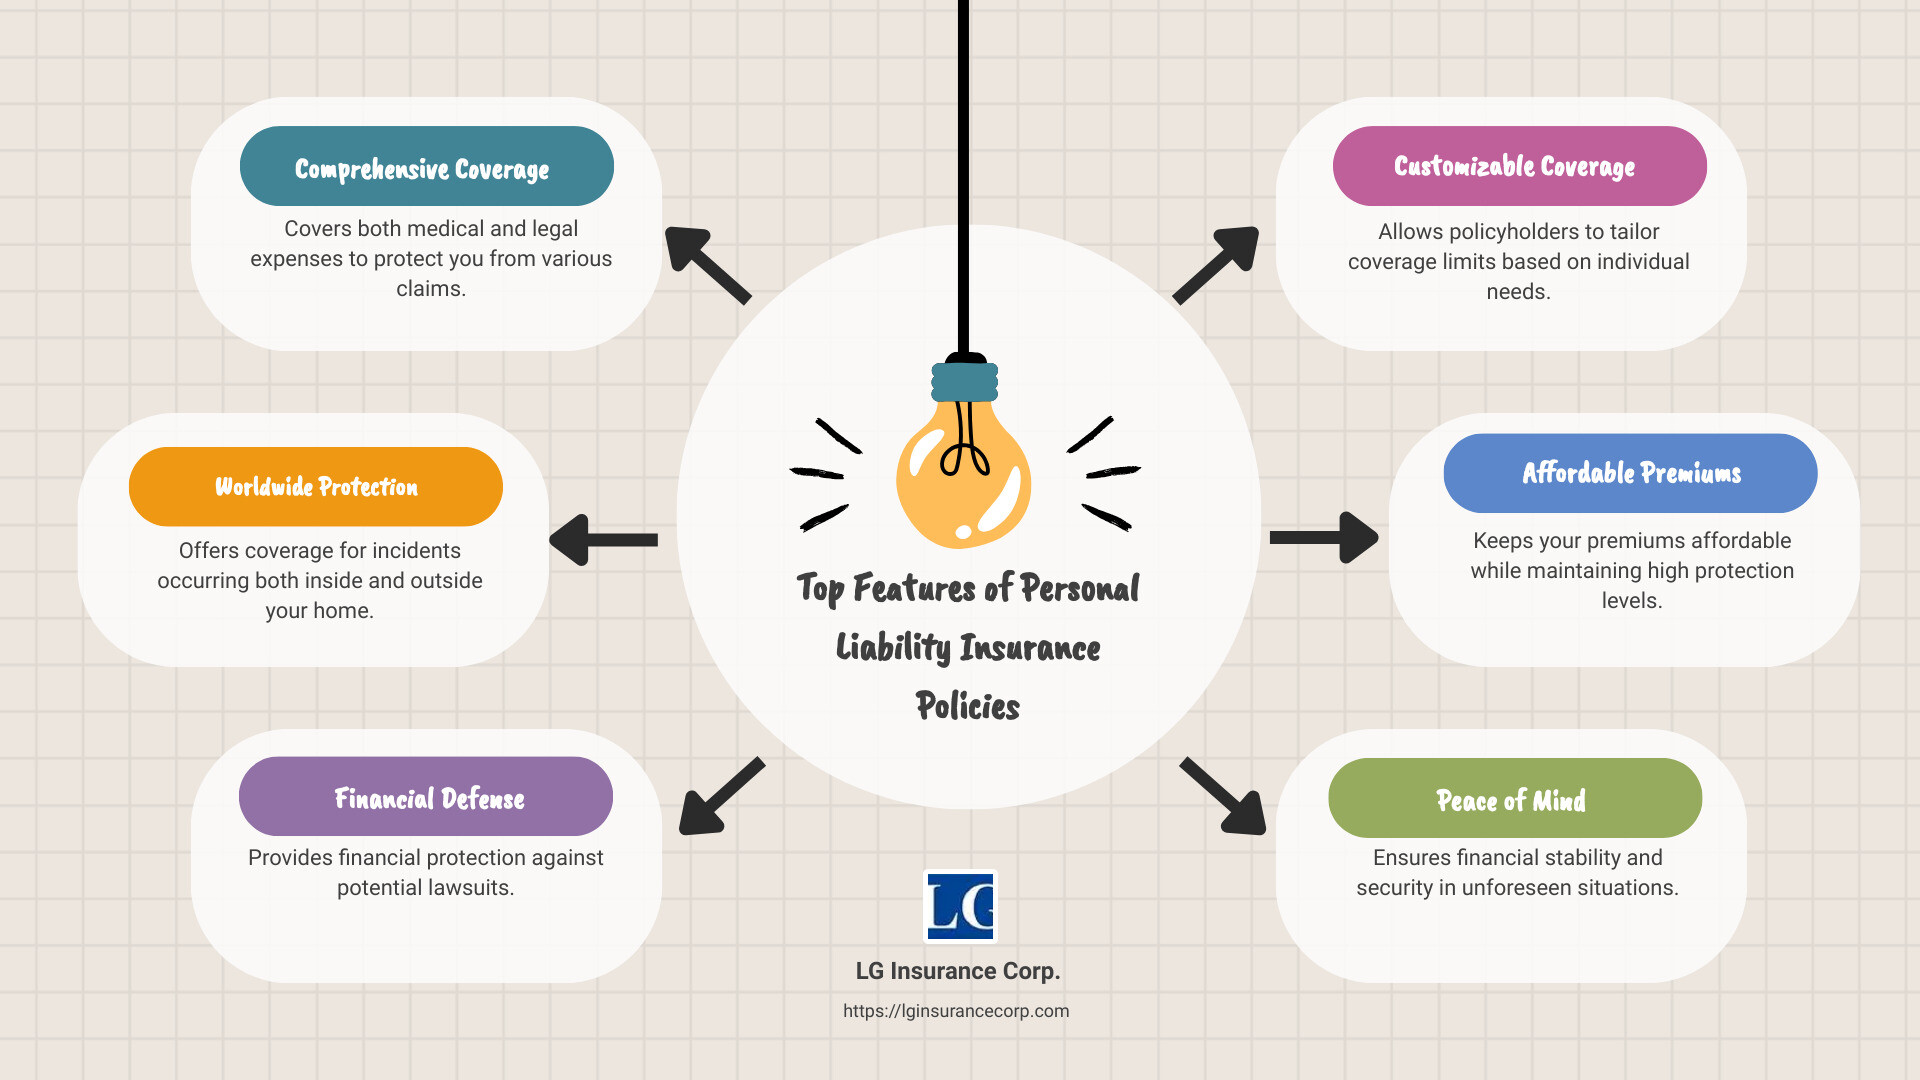
Best personal liability insurance is crucial for protecting yourself and your assets from unexpected events that can lead to costly legal and medical expenses. This coverage is a key component of a well-rounded homeowners insurance policy, safeguarding you from claims of bodily injury or property damage for which you might be held responsible. If you’re in a hurry, here are some standout features of the best personal liability insurance policies:
- Comprehensive coverage for medical and legal expenses
- Protection for incidents both within and outside your home
- Financial defense against potential lawsuits
Taking the time to choose wisely can prevent financial ruin and give you peace of mind.
In today’s world, understanding the significance of personal liability insurance can shield you from unforeseeable liabilities, especially with home-related risks like slip-and-fall accidents. A standout feature of a reliable policy is its ability to protect not just your home but your entire financial landscape.
I’m Leonard Garcia, with over 20 years in the insurance industry, guiding individuals through the intricate world of personal liability insurance. My expertise has equipped numerous clients with the best personal liability insurance options suited to their unique needs. Let’s dig deeper into what you should look for when securing your assets.
Understanding Personal Liability Insurance
Personal liability insurance is an essential part of any comprehensive homeowners insurance policy. It serves as a safety net, offering coverage, protection, and financial security against unexpected events that could lead to costly legal and medical expenses.
Coverage
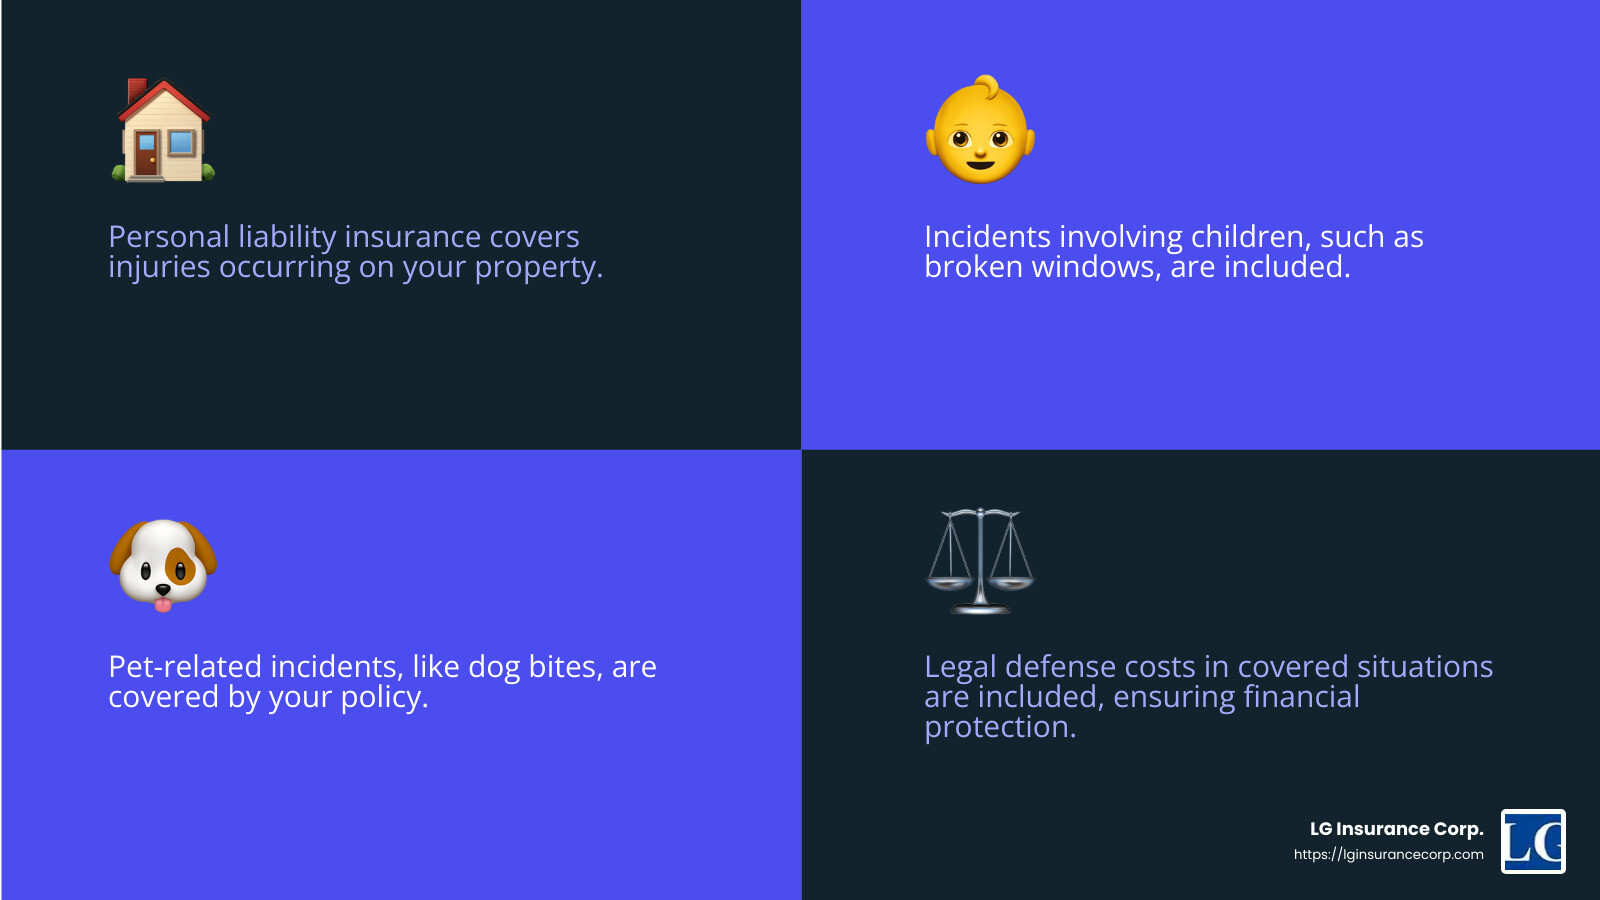
Personal liability insurance provides coverage for claims of bodily injury or property damage that you or your family members may be legally responsible for. This means if someone is injured on your property or if you accidentally damage someone else’s property, your policy can help cover the associated costs.
Here are some typical scenarios this insurance covers:
- A guest slips and falls in your home, requiring medical attention.
- Your child accidentally breaks a neighbor’s window while playing.
- Your dog bites someone, resulting in medical expenses.
Protection
The protection offered by personal liability insurance extends beyond just covering damages. It also includes legal defense costs if you are sued for an incident covered by your policy. This is crucial, as legal fees can quickly add up, even if you are not at fault.
Financial Security
Financial security is a primary benefit of having personal liability insurance. Without it, you could face significant out-of-pocket expenses that could jeopardize your financial stability. The policy acts as a financial shield, ensuring that your assets are protected from potential lawsuits and claims.
Consider the following:
- Asset Protection: Your personal liability insurance should cover the value of your assets, including your home, vehicles, and other valuable possessions.
- Peace of Mind: Knowing that you have a safety net in place allows you to live without the constant worry of financial ruin from unforeseen events.
In summary, personal liability insurance is not just an add-on; it’s a vital component of financial planning. It provides comprehensive coverage, robust protection, and essential financial security, safeguarding your assets and ensuring peace of mind. We’ll explore the best personal liability insurance options available, helping you make informed decisions to protect your future.
Best Personal Liability Insurance Options
When it comes to choosing the best personal liability insurance, understanding the coverage limits, policy features, and customer satisfaction ratings can make all the difference.
Coverage Limits
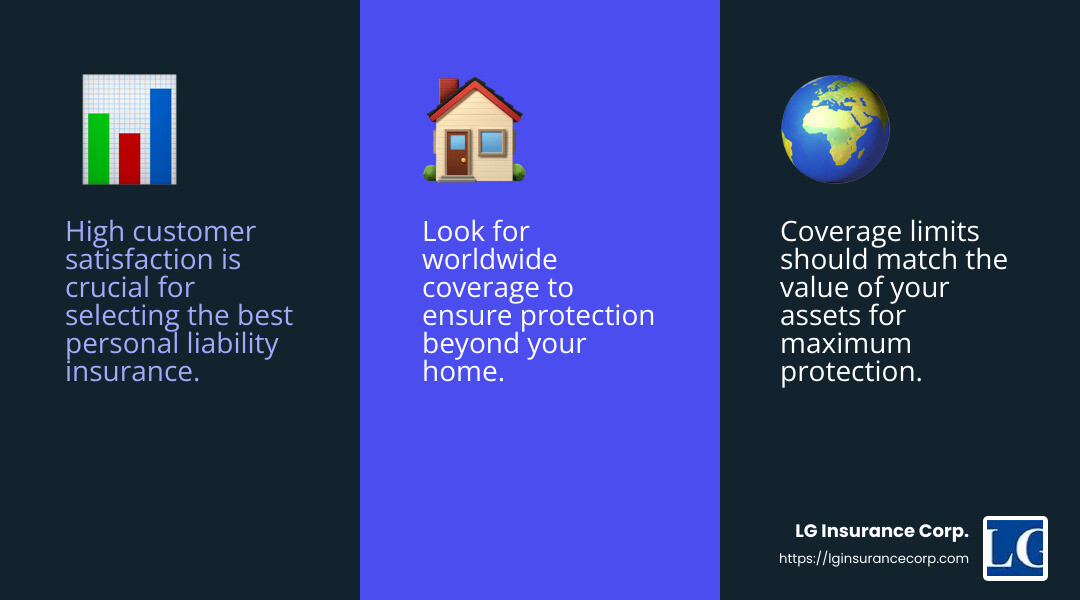
Coverage limits are a crucial factor in personal liability insurance. Most policies start with a minimum coverage of $100,000, but many experts recommend higher limits to better protect your assets. For instance, if you have a high-value home or significant savings, you might consider increasing your coverage to $300,000 or even $500,000. The goal is to match your coverage to the value of your assets to ensure complete protection.
Policy Features
The features of a personal liability insurance policy can vary, but some common elements include:
- Medical Payments: Coverage for medical expenses if someone is injured on your property.
- Legal Defense: Payment of legal fees if you’re sued for an incident covered by your policy.
- Worldwide Coverage: Protection that extends beyond your home, covering incidents that happen anywhere in the world.
Some policies also offer additional perks, such as identity theft protection or coverage for libel and slander. It’s essential to review these features and choose a policy that aligns with your specific needs.
Customer Satisfaction
Customer satisfaction is a key indicator of the quality of an insurance provider. Look for companies with high ratings in customer service, claims processing, and overall satisfaction. According to a recent study by J.D. Power, top-rated insurers excel in these areas, providing peace of mind that your claims will be handled efficiently and fairly.
In conclusion, selecting the right personal liability insurance involves balancing coverage limits, policy features, and customer satisfaction. By carefully considering these factors, you can find a policy that offers the best protection for your needs. Up next, we’ll dive into how to choose the best personal liability insurance by evaluating your assets, assessing risk, and determining your coverage needs.
How to Choose the Best Personal Liability Insurance
Choosing the best personal liability insurance involves more than just picking a policy off the shelf. Let’s break it down into three key steps: asset evaluation, risk assessment, and understanding your coverage needs.
Asset Evaluation
Start by taking a close look at your assets. This includes your home, savings, investments, and any other properties you own. The goal is to ensure that your insurance coverage matches the total value of these assets. Why? Because in a lawsuit, your assets could be at risk. If your policy’s coverage limit is too low, you might have to pay out of pocket for any damages that exceed your policy.
For example, if your assets total $500,000, you should consider a policy with at least that much in coverage. This ensures that you’re fully protected and won’t face unexpected financial burdens.
Risk Assessment
Next, assess the risks associated with your lifestyle and property. Do you have a swimming pool, trampoline, or any other “attractive nuisances” that might increase the likelihood of accidents on your property? These features can raise your liability risk and may require higher coverage limits.
Also, consider your family’s activities. Do you frequently host parties or have pets that might accidentally cause harm? Each of these factors can influence the level of risk you face and, consequently, the amount of coverage you need.
Coverage Needs
Finally, determine your specific coverage needs. Personal liability insurance typically covers bodily injury and property damage claims that you or your family are legally responsible for. However, you might want additional features such as legal defense costs or worldwide coverage.
Think about your lifestyle and any unique risks you might encounter. For instance, if you travel often, a policy with worldwide coverage could be beneficial. Or, if you have a high-profile job, coverage for libel and slander might be a wise addition.
By evaluating your assets, assessing your risk, and understanding your coverage needs, you can choose a personal liability insurance policy that provides the right level of protection. Up next, we’ll answer some frequently asked questions to help clarify any lingering doubts about personal liability insurance.
Frequently Asked Questions about Personal Liability Insurance
What is personal liability insurance?
Personal liability insurance is a safeguard for your financial well-being. It offers protection against claims of bodily injury or property damage that you or your family members might be legally responsible for. Imagine a guest slipping on your icy driveway and getting injured. This insurance helps cover medical expenses and legal fees, so you don’t have to pay out of pocket.
This kind of insurance is essential because it shields your assets from claims that could otherwise lead to significant financial loss. Coverage typically includes medical costs, legal defense fees, and compensation for damages you’re found liable for. It’s a simple way to ensure financial security in a world where accidents happen.
How much personal liability coverage do I need?
Determining the right amount of personal liability coverage involves assessing your assets and evaluating your risk. Here’s how:
Asset Evaluation: Add up the value of your home, savings, investments, and other properties. Your coverage should be at least equal to this total to protect you from losing these assets in a lawsuit.
Risk Assessment: Consider factors that might increase your liability risk. Do you own a pool or a dog? Do you frequently host events at your home? These elements can increase the likelihood of accidents, suggesting a need for higher coverage limits.
In general, a standard policy might start at $100,000, but many experts recommend at least $300,000 to $500,000, especially if you have substantial assets.
Is personal liability insurance the same as umbrella insurance?
While both types of insurance provide liability protection, they are not identical. Here’s a breakdown:
Personal Liability Insurance: This is typically included in your homeowner’s policy and covers claims related to bodily injury and property damage up to a certain limit.
Umbrella Insurance: This offers additional coverage beyond the limits of your existing policies. It kicks in when your personal liability insurance is maxed out. Umbrella insurance also covers some claims that personal liability insurance does not, such as libel, slander, and certain legal fees.
Think of umbrella insurance as an extra layer of security, especially valuable if you have significant assets or face higher risks. It’s an ideal choice for those seeking comprehensive protection against large claims or lawsuits.
By understanding these key points, you can make informed decisions about your personal liability insurance needs, ensuring you have the right protection in place.
Conclusion
At LG Insurance Corp., we understand the importance of protecting what matters most to you. Our team is committed to providing expert advice custom to your unique needs, ensuring that you have the best personal liability insurance coverage possible. Whether it’s safeguarding your home, your savings, or your peace of mind, we’re here to help you steer the complexities of insurance with ease.
We pride ourselves on being a family-owned agency that puts our community first. Our roots in Miami, FL, have taught us the value of strong relationships and personalized service. We believe in supporting our community through comprehensive insurance solutions that offer security and confidence.
When you choose LG Insurance Corp., you’re not just getting an insurance policy; you’re gaining a partner in protection. We invite you to explore our comprehensive liability insurance options and find how we can help you cover your bases with confidence.
Your financial security is our priority, and with our guidance, you can rest easy knowing you’re well-protected. Let’s work together to ensure you have the coverage you need for a worry-free future.