The average cost of homeowners insurance in Miami is a pressing concern for many residents, given the city’s unique blend of beauty and risk. Miami is not just vibrant and diverse in culture, but it also faces serious threats from hurricanes and floods, which significantly affect home insurance premiums. On average, Miami homeowners can expect to pay higher than the state average of $2,100 per year, with actual costs potentially soaring due to the high-value properties and increasing weather-related risks.
Understanding these costs is essential for anyone living in Miami. Homeowners insurance in Miami is shaped by several factors, including the city’s susceptibility to hurricanes and floods, which lifts both the likelihood of damage and insurance costs.
As Leonard Garcia, owner of LG Insurance Agency with over 20 years in Miami’s insurance industry, I am committed to explaining the average cost of homeowners insurance in Miami for you. My expertise is founded on personalization and thorough understanding, aiming to provide you with the most relevant insurance solutions.
Average cost of homeowners insurance in miami word roundup:
– Miami home insurance rates
– affordable homeowners insurance miami florida
– home insurance companies miami fl
Average Cost of Homeowners Insurance in Miami
Miami is a city known for its vibrant culture and stunning landscapes, but it also comes with its share of risks. Understanding the average cost of homeowners insurance in Miami is crucial for homeowners looking to protect their investments. On average, homeowners in Miami pay around $8,617 per year for insurance coverage on a $300,000 dwelling. This figure can rise significantly depending on various factors.
Factors Affecting Insurance Costs
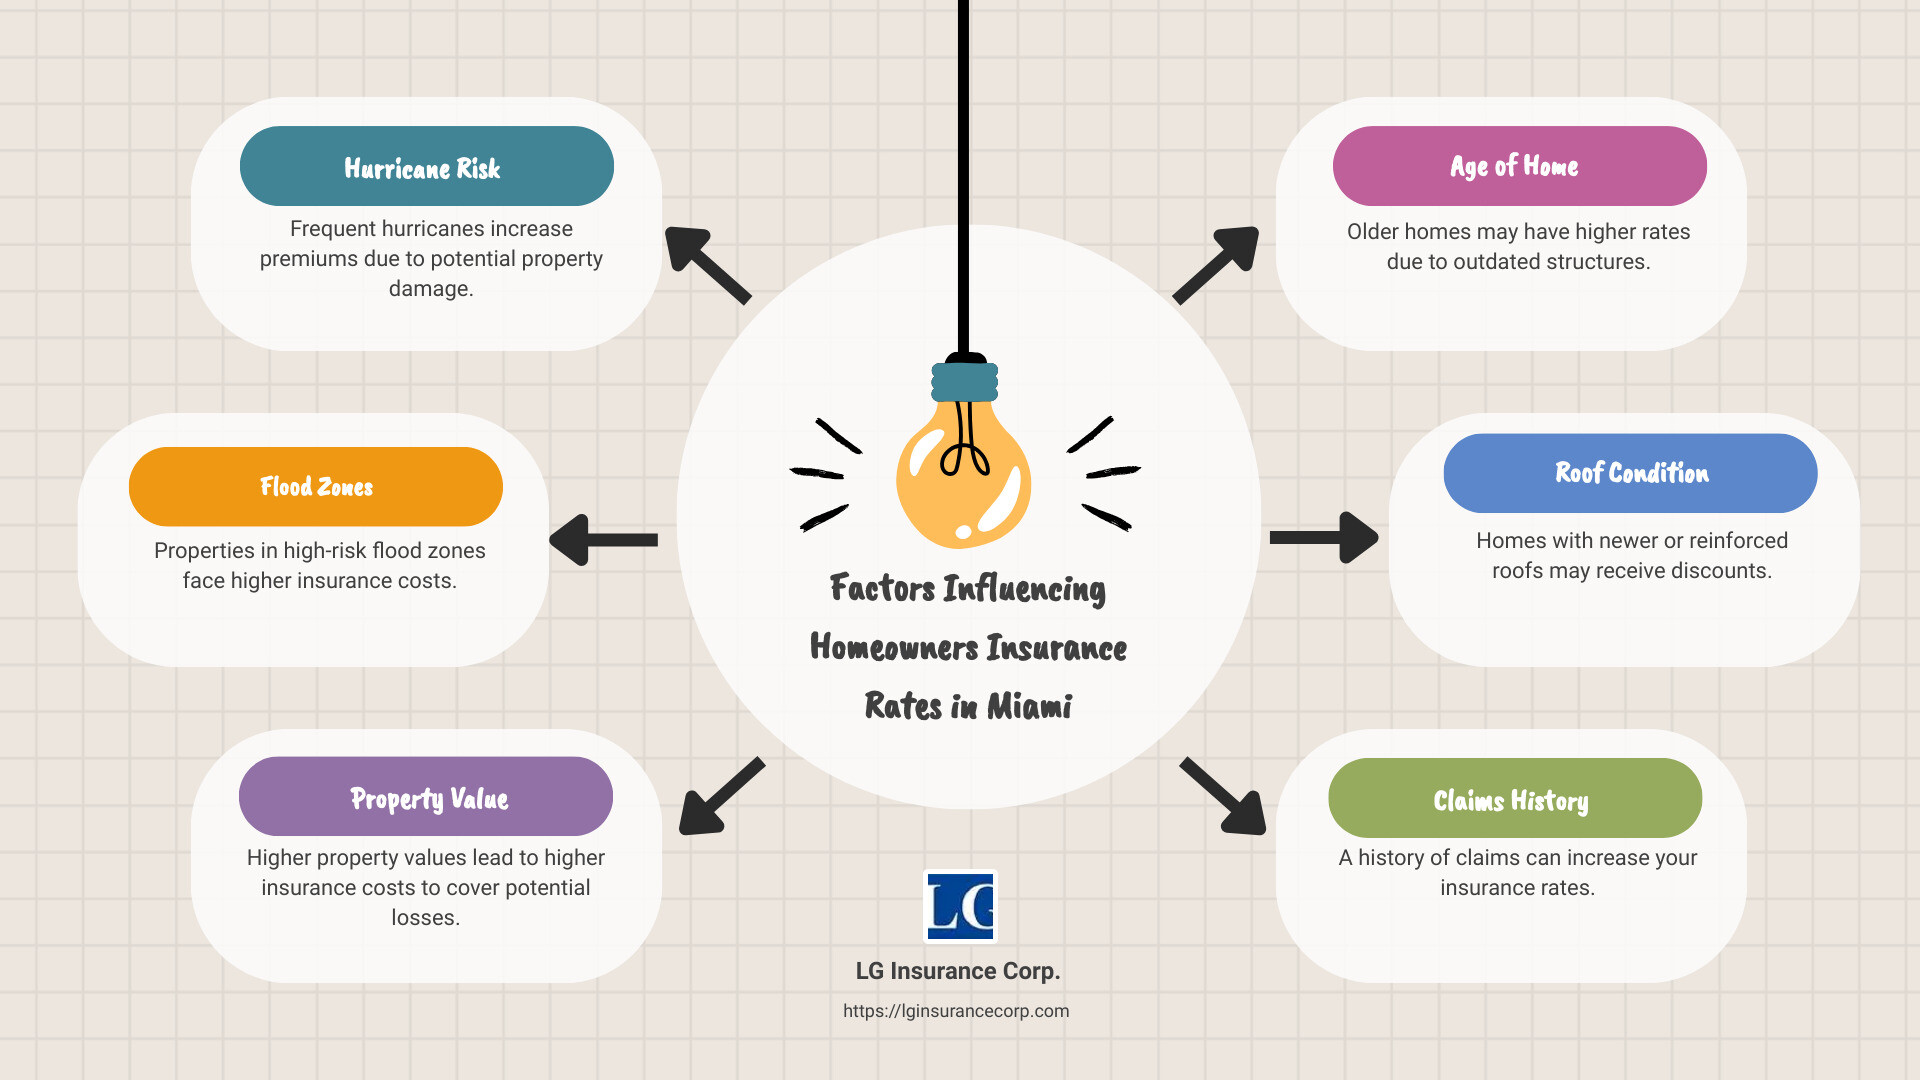
Several elements influence insurance costs in Miami:
Natural Disasters: Miami’s vulnerability to hurricanes and floods is a major factor driving up insurance premiums. The city’s location on the Atlantic coast increases the risk of weather-related claims.
Property Characteristics: The age of your home and the condition of its roof can impact your premium. Older homes or those with outdated roofing materials may face higher costs due to increased risk of damage.
Financial History: Your credit and claims history also play a role. A poor credit rating or a history of frequent claims can lead to higher premiums.
Coverage and Deductibles: The extent of coverage you choose and your deductible amount can affect your costs. Opting for higher deductibles can lower your premium but increases out-of-pocket expenses during a claim.
Comparison of Average Costs
When comparing insurance costs, consider the value of your home:
$150,000 House: Homeowners insurance for these properties varies significantly based on construction date and wind mitigation features. For example, homes built before 2001 without wind mitigation can face premiums as high as $14,156 on average, while those with such features can see costs drop to $6,125.
$300,000 House: The average annual premium for a $300,000 house in Miami is approximately $15,602. This cost reflects the need for adequate coverage against potential disasters like hurricanes and floods.
$450,000 House: For larger homes valued at $450,000, the average insurance cost rises to $22,398. These homes typically require more extensive coverage due to their higher replacement costs.
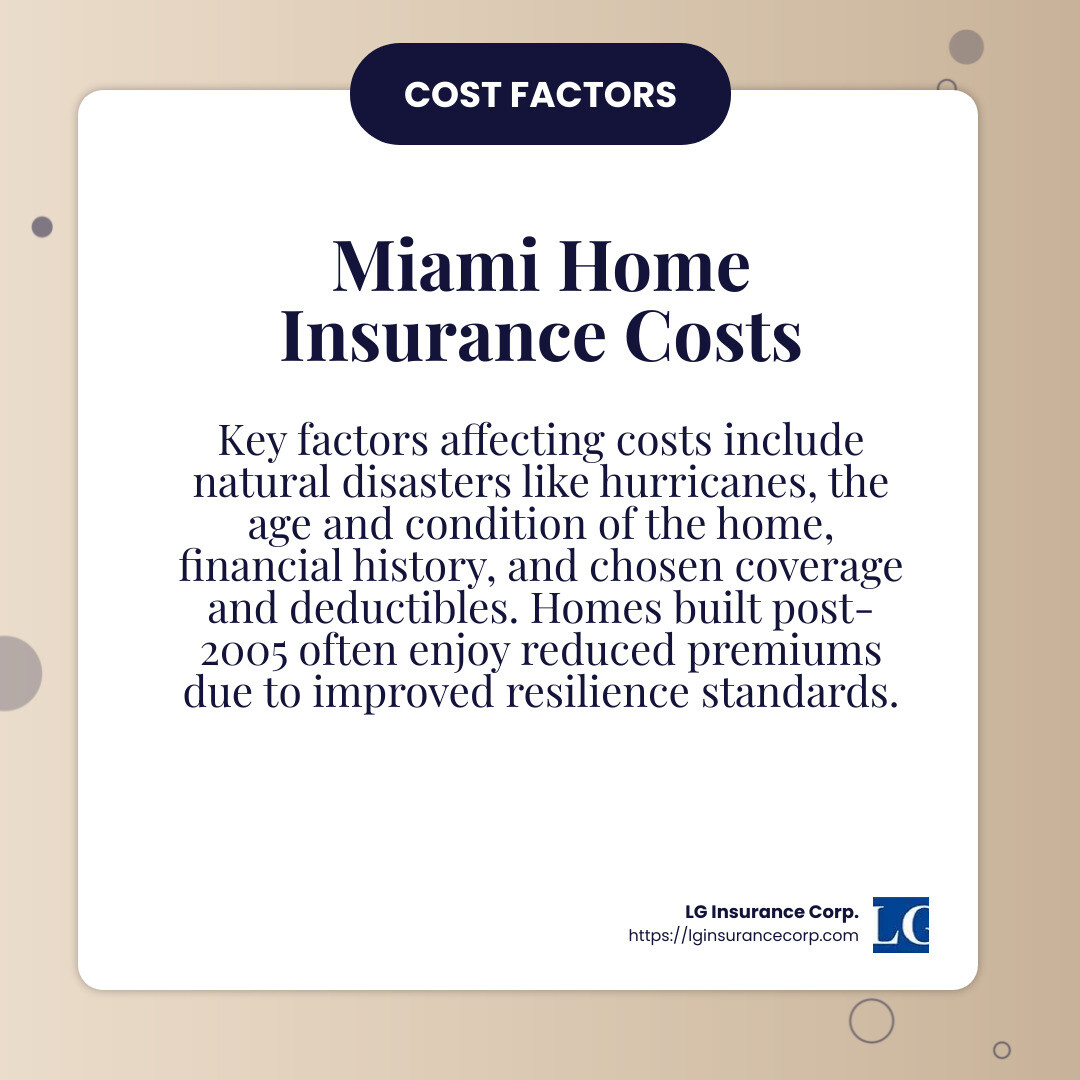
Wind Mitigation and Construction Date are critical components in determining insurance costs. Homes built after 2005, adhering to updated building codes, generally have lower premiums due to better resilience against hurricanes. Incorporating wind mitigation measures, such as reinforced roofs and impact-resistant windows, can also lead to significant savings.
Understanding these factors and average costs can empower Miami homeowners to make informed decisions about their insurance needs. With the right coverage, you can safeguard your home against the unique challenges posed by living in this beautiful yet risk-prone city.
How to Save on Homeowners Insurance in Miami
Finding ways to reduce your homeowners insurance costs in Miami can make a big difference in your budget. Here are some effective strategies:
Wind Mitigation and Construction Date
Wind Mitigation involves measures that strengthen your home against hurricane-force winds, such as using impact-resistant doors and windows or reinforcing roof construction methods. Homes built before 2001 without these features often face higher premiums. However, adding wind mitigation can cut those costs significantly. For instance, a $300,000 house built before 2001 with wind mitigation can see savings of over $10,000 per year, which is about a 56% reduction.
Construction Date also plays a crucial role. Homes constructed after 2005 benefit from stricter building codes designed to withstand hurricanes better. These homes often have lower insurance premiums compared to older homes, even without extensive wind mitigation features. Investing in new construction or upgrading your existing home to meet these standards can lead to substantial savings.
Bundling Policies
Another smart way to save is by bundling your home and auto insurance policies with the same provider. Many insurers offer discounts for bundling, which can simplify your payments and potentially lower your overall insurance costs. This approach not only provides convenience but can also result in significant savings over time.
Higher Deductibles and Discounts
Opting for a higher deductible can also reduce your premium. While this means you’ll pay more out of pocket in the event of a claim, it can lower your annual insurance costs. Additionally, taking advantage of available discounts is essential. Some insurers offer discounts for installing modern security systems, smoke detectors, or even being a long-term customer.
Technology and Surveys
Utilizing technology, such as apps or online tools from your insurance provider, can help you monitor your policy and find additional savings opportunities. According to the Kin Customer Savings Survey, homeowners have saved an average of $977 by optimizing their coverage and taking advantage of available discounts.
By understanding these strategies and how they relate to factors like construction date and wind mitigation, Miami homeowners can better steer the complexities of insurance costs. This knowledge empowers you to make informed decisions and secure the best possible rates for your home insurance needs.
Additional Coverage Options for Miami Homeowners
Living in Miami comes with its unique set of challenges, especially when it comes to protecting your home. Flood insurance and hurricane deductibles are crucial considerations for homeowners in this vibrant city. Here’s a closer look at these essential coverage options:
Flood Insurance
In Miami, standard homeowners insurance policies do not cover flood damage. Given the city’s susceptibility to flooding, especially in high-risk areas designated by FEMA flood zones, it is vital to have a separate flood insurance policy.
FEMA Flood Zones: Areas in Miami marked with letters A or V are considered high-risk flood zones. Homeowners in these areas may be required by their mortgage lender to purchase flood insurance. FEMA’s flood maps help determine your risk level and the necessary insurance requirements.
Separate Policy: Flood insurance must be purchased separately from your standard homeowners policy. This additional coverage can protect you from the financial burden of flood-related damages, which can be significant.
Hurricane Deductibles
Miami’s location along the Atlantic coast makes it prone to hurricanes. As a result, insurance policies in the area often include a hurricane deductible. Unlike standard deductibles, hurricane deductibles are percentage-based, typically ranging from 1% to 10% of your dwelling coverage.
Percentage-Based Deductible: For a house with $300,000 in dwelling coverage, a 2% hurricane deductible means you’re responsible for the first $6,000 in hurricane-related repairs. This deductible is higher than the standard one but applies only once per hurricane season, regardless of the number of storms.
Once Per Hurricane Season: The benefit of this deductible structure is that it only applies once per season. So, if multiple hurricanes hit, you only pay the deductible for the first event.
Sinkhole Coverage
While Miami is less prone to sinkholes compared to other parts of Florida, the risk still exists, especially with new developments. Homeowners should consider adding specific sinkhole coverage to their policy. This coverage can protect against damages that do not meet the criteria for catastrophic ground collapse but still require expensive repairs.
These additional coverage options are essential for Miami homeowners to consider. They provide peace of mind and financial protection against the unique risks posed by living in this coastal city. Understanding and investing in the right coverage can safeguard your home from the unexpected challenges of Miami’s weather and geography.
Frequently Asked Questions about Homeowners Insurance in Miami
Why is home insurance so expensive in South Florida?
Home insurance in South Florida, particularly in Miami, is notoriously expensive due to several key factors. Hurricanes are a major threat, with Miami sitting in a high-risk zone for these devastating storms. The potential for flooding, especially in low-lying coastal areas, further lifts insurance costs. Additionally, Miami’s susceptibility to sinkholes, though less than other parts of Florida, still contributes to the overall risk profile. These elements combined mean that homeowners face higher premiums to adequately protect their properties from these natural disasters.
How much is the average homeowners insurance bill in Florida?
The average cost of homeowners insurance in Florida is about $2,100 per year. However, this figure can vary significantly based on location and risk factors. Miami, with its high exposure to hurricanes and floods, tends to have much higher premiums. In fact, Miami homeowners often pay well above the state average due to these increased risks. It’s essential for homeowners to understand that living in a high-risk area necessitates more comprehensive coverage, which naturally drives up the cost.
How can I reduce my homeowners insurance costs in Miami?
Despite the high costs, there are several strategies Miami homeowners can use to reduce their insurance premiums:
Wind Mitigation: Implementing wind mitigation measures, such as installing storm shutters or reinforcing your roof, can lead to significant discounts on your insurance policy. These improvements make your home more resilient to hurricane damage, which insurers favor.
Bundling Policies: Consider bundling your home insurance with other policies, like auto insurance, through the same provider. Many insurers offer discounts for customers who consolidate their insurance needs.
Higher Deductibles: Opting for a higher deductible can lower your premium. While this means you’ll pay more out-of-pocket in the event of a claim, it reduces your regular insurance costs.
Discounts: Look out for any available discounts. Some insurers offer savings for policyholders with good credit, security systems, or loyalty to their company.
By taking these steps, Miami homeowners can better manage the average cost of homeowners insurance and find a balance between comprehensive coverage and affordability.
Conclusion
Understanding the average cost of homeowners insurance in Miami is crucial for anyone living in this vibrant yet high-risk area. With unique challenges like hurricanes, floods, and occasional sinkholes, Miami homeowners face some of the highest insurance premiums in the country.
At LG Insurance Corp., we recognize the importance of providing custom solutions that address these specific risks while remaining affordable. Our team is committed to offering expert advice and crafting custom policies that fit your unique needs and budget.
We believe in supporting our community by helping you safeguard your most valuable asset—your home. Our family-owned agency takes pride in delivering customer-centric service, ensuring you receive the right coverage without breaking the bank.
For personalized assistance and to explore how we can help you save on your homeowners insurance, visit our Home Insurance page. Let us guide you in securing a policy that offers both peace of mind and financial protection.